What Is Uniswap v4?
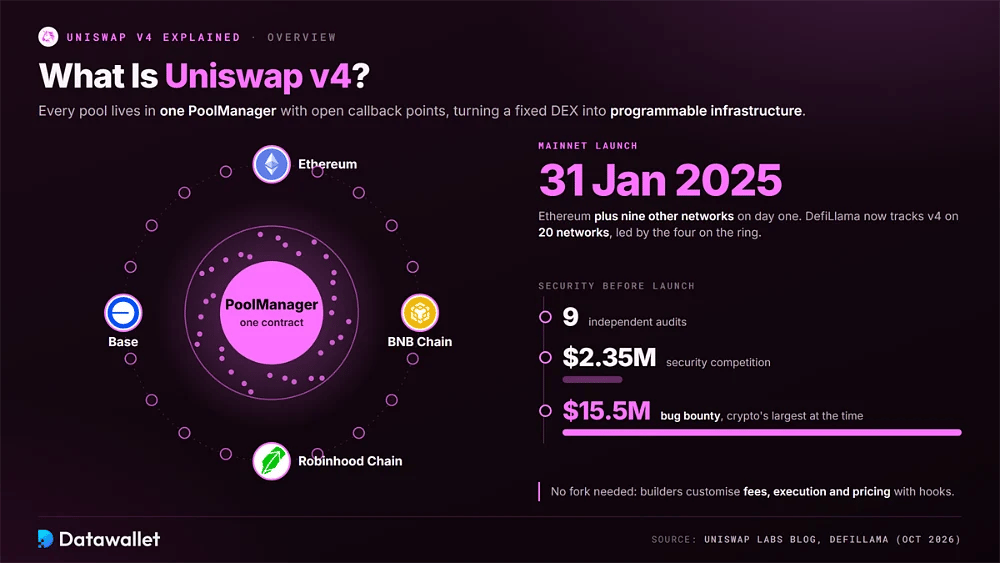
Uniswap v4 is the fourth major release of the Uniswap protocol. It went live on Ethereum and nine other networks on 31 January 2025, after nine independent audits, a $2.35 million security competition, and a $15.5 million bug bounty that was the largest ever offered in crypto at the time.
Its defining change is structural rather than cosmetic. Previous versions deployed a new contract for every pool, whereas v4 holds all pools inside a single PoolManager and exposes callback points that outside contracts can use. That turned Uniswap from a fixed product into programmable infrastructure where builders customise fees, execution, and pricing without forking.
By October 2026, DefiLlama tracks v4 on 20 networks, led by Ethereum, BNB Chain, Robinhood Chain, and Base. It is now the default target for new decentralised exchange experiments, from tokenised stock venues to MEV-resistant pools, and it competes with v3 for the largest share of Uniswap's total value locked.
How Uniswap v4 Works
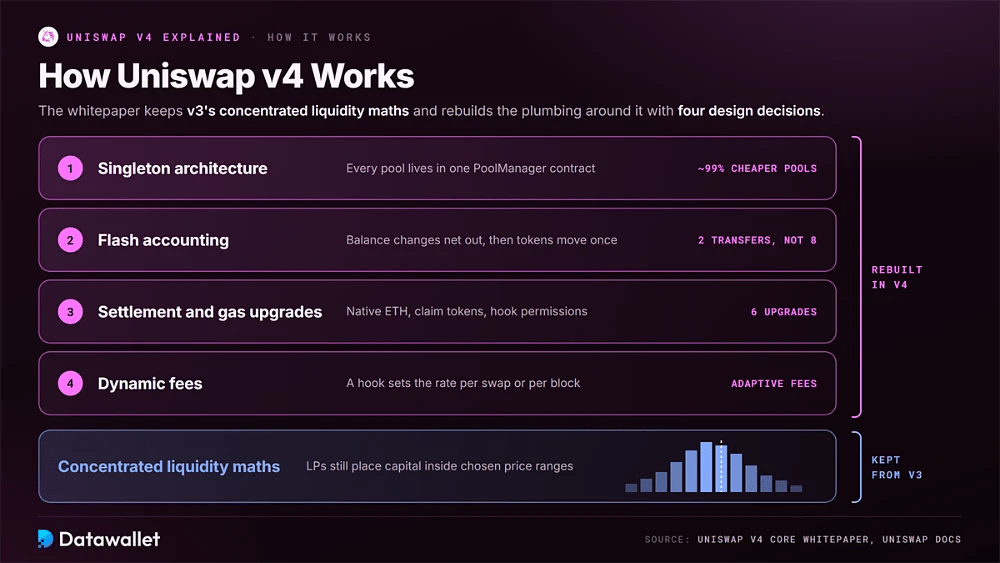
The v4 core whitepaper retains the concentrated liquidity maths introduced in v3, then rebuilds the plumbing around it. Four design decisions explain most of the gains traders and liquidity providers have seen since launch, from cheaper routing to adaptive fees.
1. Singleton Architecture
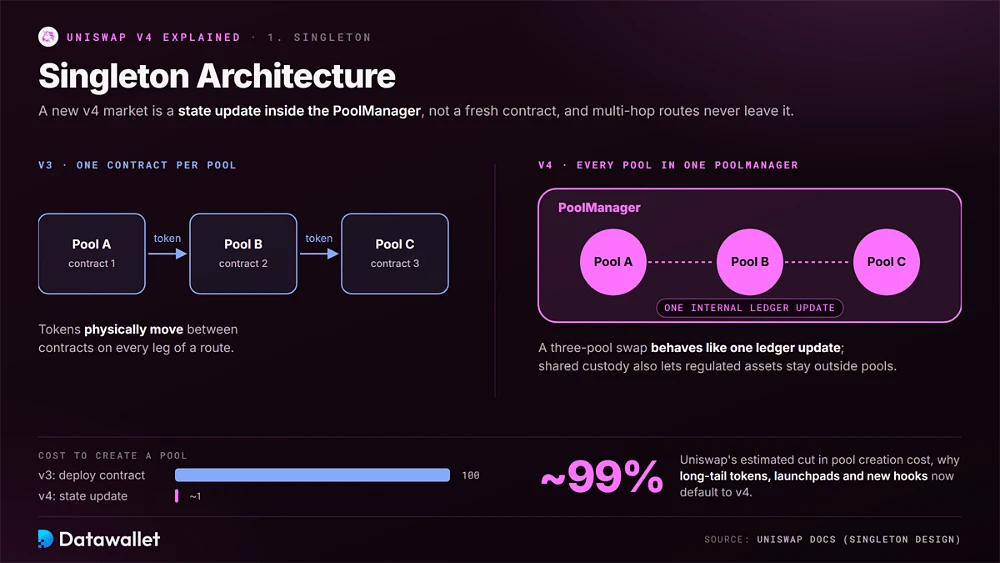
Every v4 pool lives inside the PoolManager contract, so launching a new market is a state update instead of a fresh contract deployment. Uniswap estimates this cuts pool creation costs by roughly 99%, which is why long-tail tokens, launchpads, and experimental hooks now default to v4 rather than earlier versions.
Holding every balance in one place also changes multi-hop trading. Tokens no longer travel between separate pool contracts on each leg of a route, so a swap through three pools behaves like one internal ledger update. That shared custody is also what lets newer features, such as permissioned pools, keep regulated assets outside the pool.
2. Flash Accounting
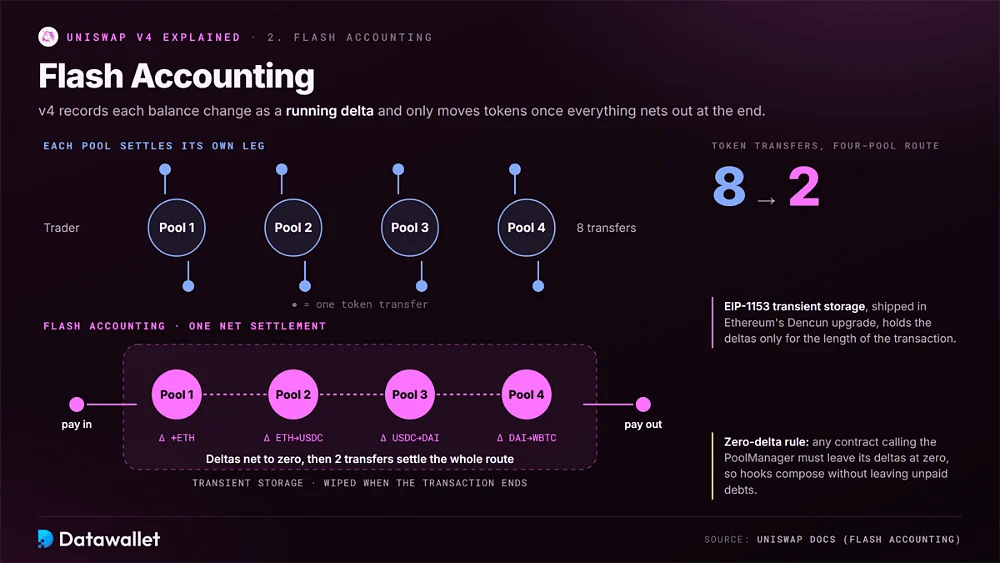
Flash accounting records each balance change as a running delta during a transaction and only moves tokens once everything nets out at the end. It relies on transient storage from EIP-1153, which arrived with Ethereum's Dencun upgrade and lets contracts hold temporary data that is wiped once the transaction completes.
The practical effect is fewer token transfers. A route touching four pools settles with two transfers instead of eight, and any contract that interacts with the PoolManager must leave its deltas at zero before the call ends. That rule is what makes complex hook logic composable without exposing the singleton to unpaid debts.
3. Settlement and Gas Upgrades
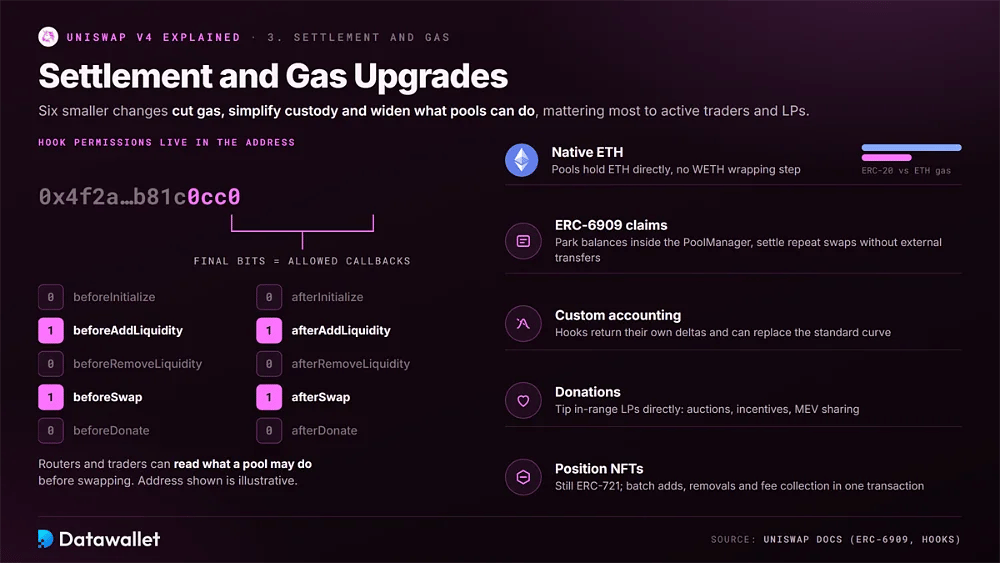
Beyond the singleton and flash accounting, v4 ships several smaller changes that reduce gas, simplify custody, and widen what pools can do. Each one matters most to active traders and liquidity managers.
The upgrades worth knowing before you trade or provide liquidity are:
- Native ETH: Pools can hold ETH directly instead of WETH, removing the wrapping step from v2 and v3 and roughly halving transfer gas compared with a standard ERC-20 token.
- ERC-6909 Claims: Traders and market makers can park balances inside the PoolManager as claim tokens, then settle repeated swaps against them without paying for an external transfer every time.
- Hook Permissions: A hook's allowed callbacks are encoded in the final bits of its contract address, so routers and traders can verify what a pool may do before swapping.
- Custom Accounting: Hooks can return their own balance deltas, letting a pool replace the standard curve entirely, which is how aggregator hooks and permissioned pools reuse v4's settlement layer.
- Donations: A dedicated donate function lets anyone tip in-range liquidity providers directly, a building block for auctions, incentive programmes, and MEV-sharing schemes that pay LPs.
- Position NFTs: Liquidity positions are still minted as ERC-721 NFTs through the PositionManager, but unlocked calls let LPs batch adds, removals, and fee collection into one transaction.
4. Dynamic Fees
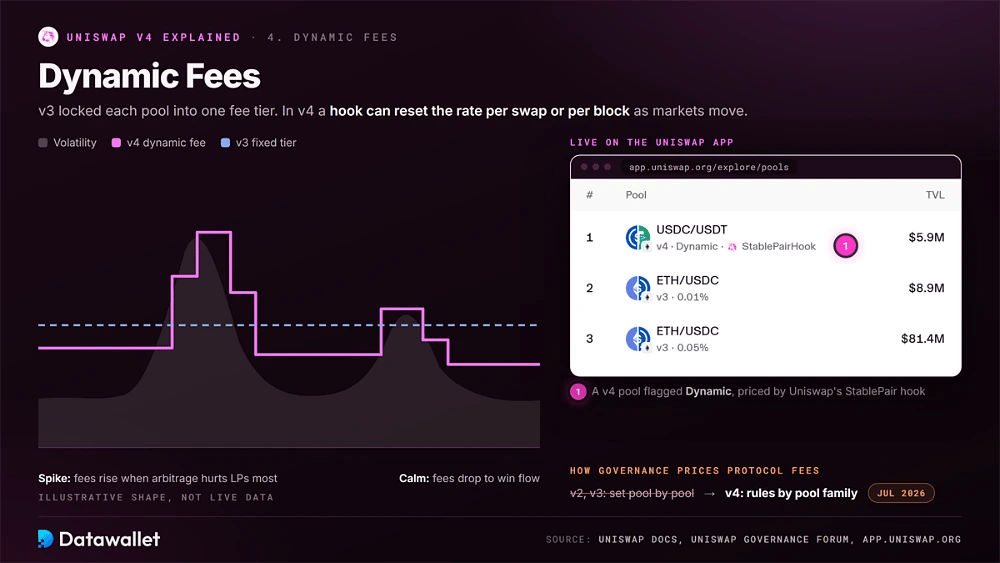
Version 3 locked every pool into a fixed fee tier chosen at creation. In v4, a pool flagged for dynamic fees lets its hook set the rate per swap or per block, so liquidity providers can charge more when volatility spikes and arbitrage is most damaging, then cut fees when markets calm.
Dynamic fees also forced governance to rethink protocol revenue. Because a v4 pool can have effectively unlimited fee settings, the July 2026 fee framework sorts pools into families and calculates the protocol cut from rules, rather than configuring each pool by hand as governance did for v2 and v3.
Uniswap v4 Hooks Explained
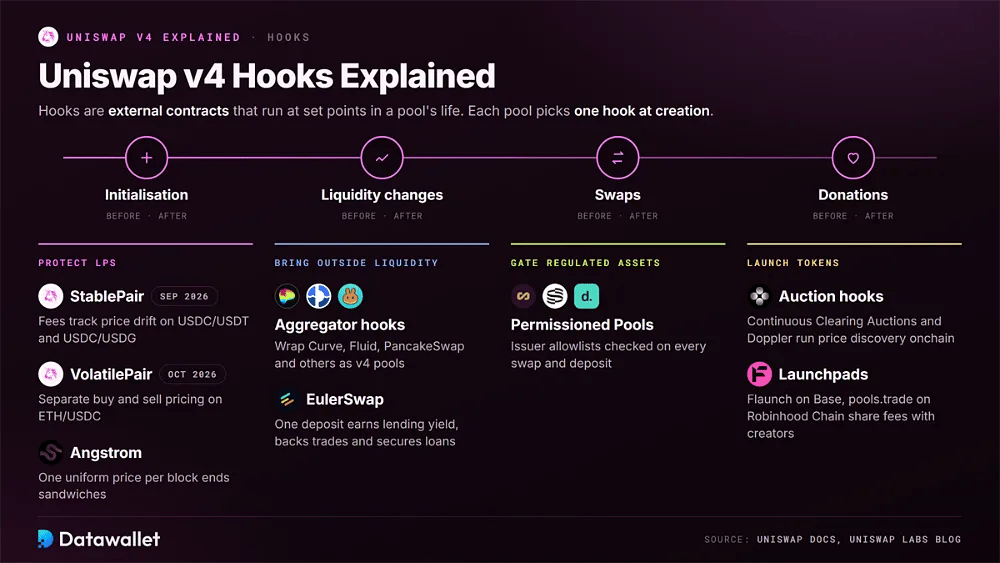
Hooks are external contracts that run at set points in a pool's lifecycle: initialisation, swaps, liquidity changes, and donations. Each pool picks one hook at creation, and that choice defines how the pool behaves.
The hooks shaping Uniswap v4 activity in 2025 and 2026 include:
- StablePair: Launched by Uniswap Labs in September 2026 for USDC/USDT and USDC/USDG, it ties fees to price drift and auctions parity-restoring trades so LPs keep more arbitrage value.
- VolatilePair: Live on Ethereum since 14 October 2026, starting with ETH/USDC, this hook prices buys and sells separately and adds a temporary surcharge after sharp moves to blunt arbitrage.
- Permissioned Pools: An open standard released in July 2026 that lets issuers enforce allowlists on every swap and deposit, built with Superstate, Securitize, and Dowgo for tokenised securities.
- Aggregator Hooks: Wrappers that present Curve, Fluid, PancakeSwap, and other external venues as v4 pools, so Uniswap routes through outside liquidity while still collecting a protocol fee on that flow.
- EulerSwap: Connects swap execution to Euler's lending vaults, so a single deposit earns lending yield, backs trades, and serves as borrowing collateral, making it one of 2025's busiest hooks.
- Angstrom: Sorella Labs' hook clears each block's trades at one uniform price, making sandwich attacks structurally impossible and returning arbitrage value to liquidity providers instead of searchers.
- Auction Hooks: Continuous Clearing Auctions and Doppler run token price discovery fully onchain, and governance now treats pools seeded by Uniswap's clearing auctions as a separate fee family.
- Launchpads: Flaunch on Base and pools.trade on Robinhood Chain launch tokens straight into v4 pools, using hooks to share trading fees with creators and lock launch liquidity.
Aggregator Hooks: Uniswap v4 Becomes an Aggregator
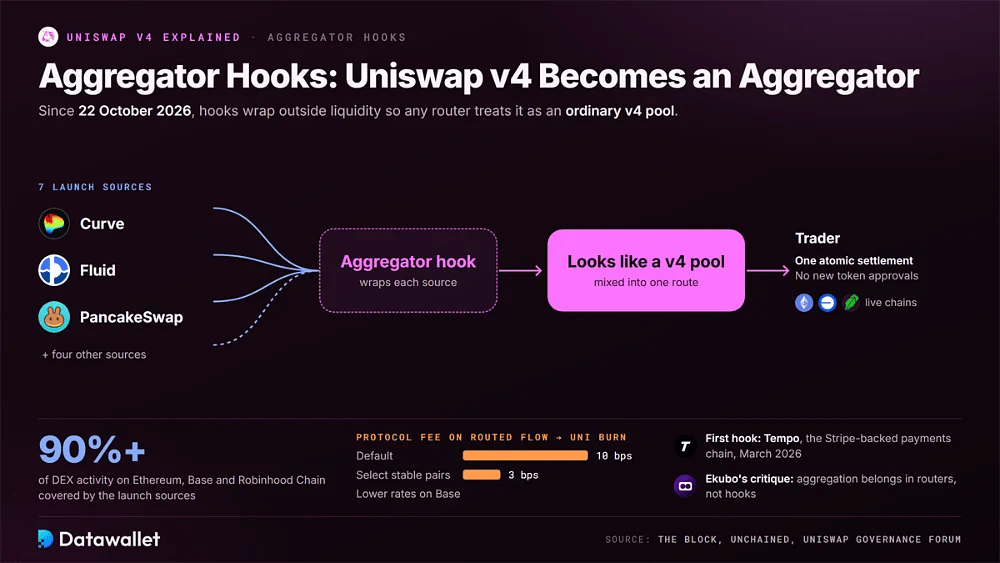
On 22 October 2026, Uniswap Labs switched on aggregator hooks for the web app and API on Ethereum, Base, and Robinhood Chain. Each hook wraps an external liquidity source so any router treats it as an ordinary v4 pool, and the seven launch venues cover over 90% of DEX activity on those chains.
For traders, the change is invisible but useful. A single route can mix native Uniswap pools with Curve, Fluid, or PancakeSwap liquidity, settle atomically in one transaction, and require no new token approvals. The first aggregator hook went live on Tempo, the Stripe-backed payments chain, in March 2026.
For UNI holders, it matters economically. Flow routed through these wrappers pays protocol fees that feed the burn, which governance's July framework sets at 10 basis points by default and 3 bps on select stable pairs, with lower rates on Base. Critics such as Ekubo argue aggregation belongs in routers, not hooks.
How Trades Execute on Uniswap v4
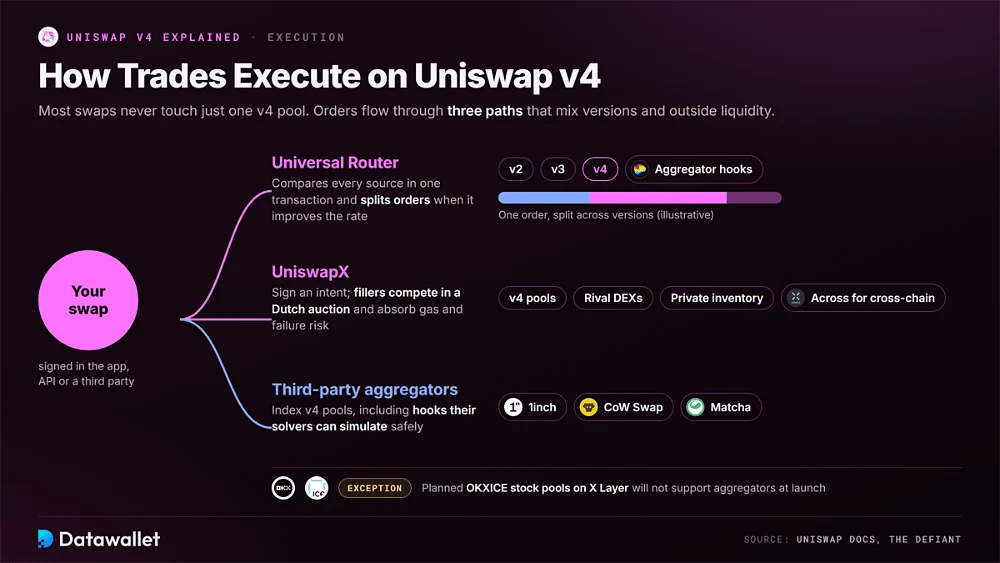
Most swaps on the Uniswap app never touch just one v4 pool. The Universal Router compares prices across v2, v3, v4, and now aggregator-hook liquidity in a single transaction, splitting orders between versions whenever that improves the final rate. This is why v4 gained volume gradually rather than through a forced migration.
Larger orders increasingly settle through UniswapX, the intent-based system where users sign an order and competing fillers execute it via a Dutch auction. Fillers draw on v4 pools, rival DEXs, and private inventory, absorbing gas and failure risk. The same design powers cross-chain swaps through an integration with the Across bridge.
Third-party aggregators such as 1inch, CoW Swap, and Matcha index v4 pools, including hook-enabled ones their solvers can simulate safely, so competitive pools win volume from any DEX aggregator. The exception is closed venues: the planned OKXICE stock pools on X Layer will not support aggregators at launch.
Uniswap v4 Adoption: The October 2026 Numbers
Adoption was slow at first. v4 launched without incentives and blue-chip liquidity stayed on v3 through early 2025. Growth then came in waves: aggregator integrations in mid-2025, the Robinhood Chain launch in July 2026, and Labs-built hooks for stablecoins and tokenised assets in the third quarter.
As of 24 October 2026, DefiLlama shows $484 billion in cumulative v4 volume, including $245 billion on Ethereum, $71 billion on Unichain, and $40 billion each on Robinhood Chain and BNB Chain. Thirty-day volume sits near $33.6 billion, and liquidity providers have earned about $540 million in cumulative swap fees.
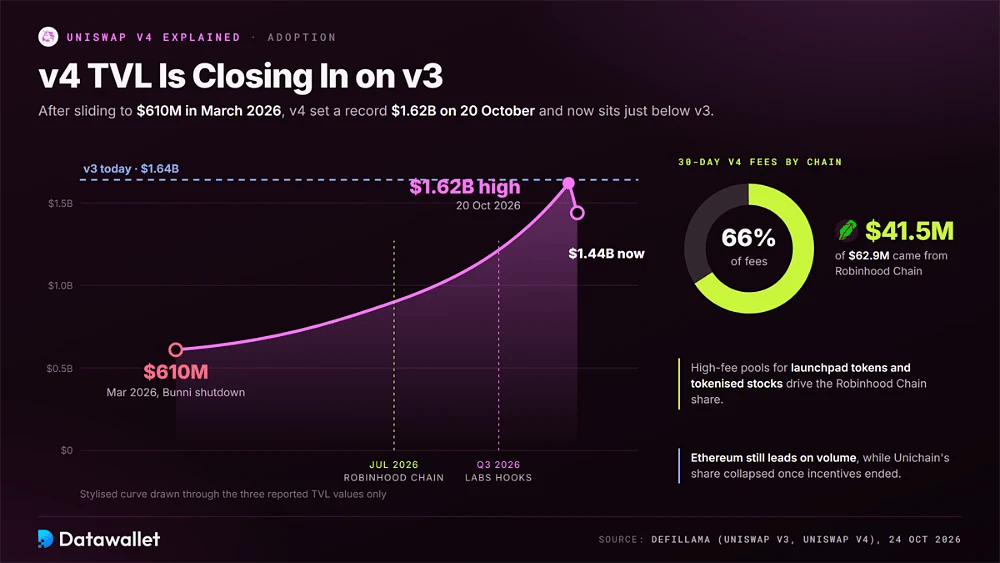
TVL has recovered sharply. After sliding to about $610 million in March 2026, partly reflecting the Bunni shutdown, v4 set an all-time high of $1.62 billion on 20 October and now holds $1.44 billion, close to v3's $1.64 billion. Track the gap on our TVL dashboard.
Fee data shows where new activity comes from. Robinhood Chain generated roughly $41.5 million of v4's $62.9 million in 30-day fees, about two-thirds of the total, reflecting high-fee pools for launchpad tokens and tokenised stocks. Ethereum still leads on volume, while Unichain's share has collapsed since incentives ended.
Tokenised Stocks and Permissioned Pools on Uniswap v4
Tokenised equities became v4's most significant new market in 2026. Robinhood Chain supplied the first wave of real stock-token volume, Permissioned Pools gave issuers compliance tools, and OKXICE plans to run regulated trading through v4 hooks.
Robinhood Chain: v4's New Growth Engine
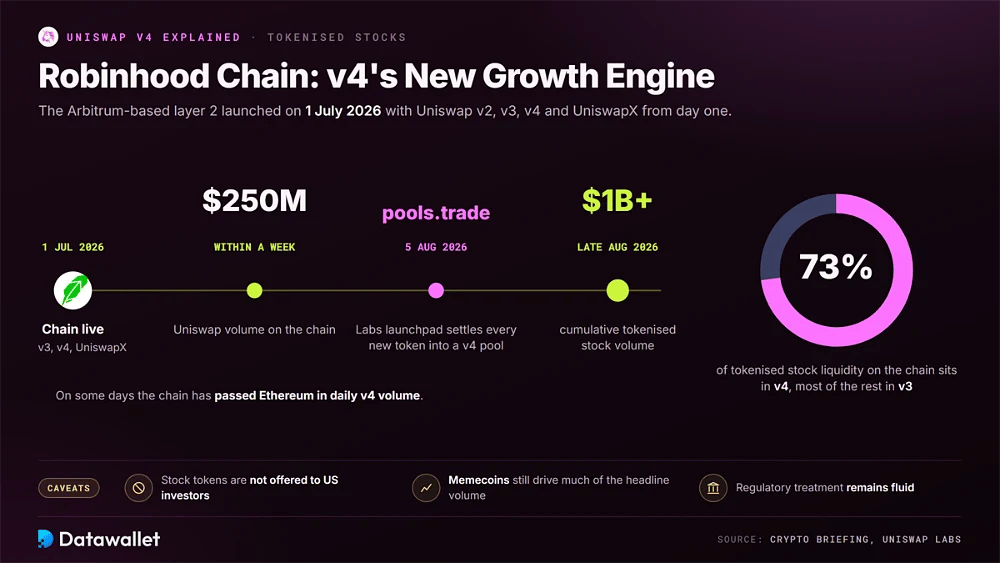
Robinhood Chain, an Arbitrum-based layer 2, went live on 1 July 2026 with Uniswap v2, v3, v4, and UniswapX available from day one. Uniswap passed $250 million in volume there within a week, and by late August its cumulative tokenised stock volume on the chain had crossed $1 billion.
v4 holds roughly 73% of tokenised stock liquidity on Robinhood Chain, with v3 holding most of the rest. Uniswap Labs also launched pools.trade on 5 August 2026, a launchpad that settles every new token into a v4 pool, which helped push the chain past Ethereum in daily v4 volume on some days.
There are caveats. Robinhood's stock tokens are not offered to US investors, memecoins still drive much of the chain's headline volume, and regulatory treatment of tokenised securities remains fluid. Anyone moving funds there should follow our guide to bridging to Robinhood Chain and confirm which assets they can legally hold.
Permissioned Pools and the OKXICE Venue
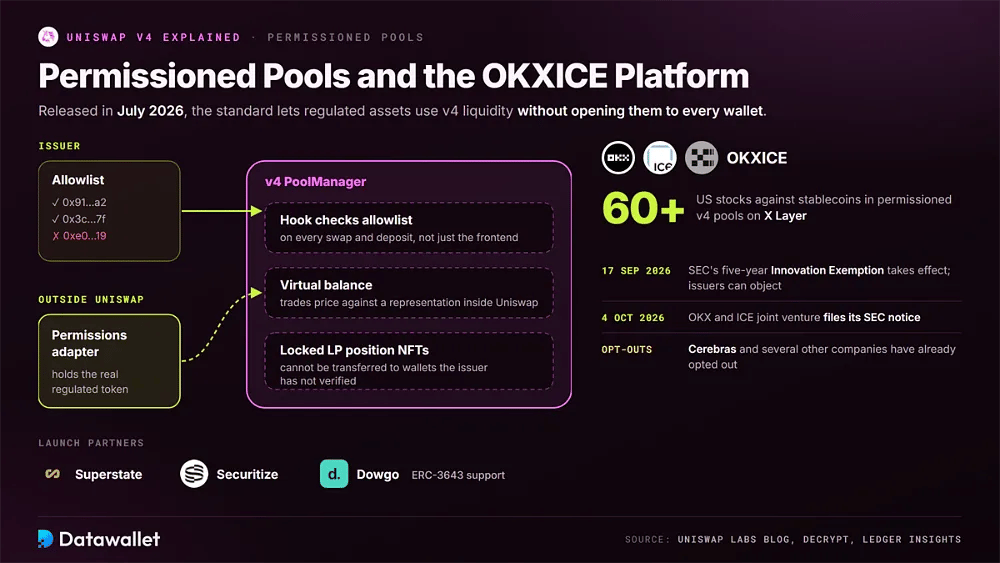
Permissioned Pools, released in July 2026, let regulated assets use v4 liquidity without opening them to every wallet. The design matters because the same approach shapes institutional venues, including the planned OKX and ICE stock platform.
Here is how the permissioned model works in practice:
- Issuer Allowlists: The issuer controls which wallets may trade or provide liquidity, and a hook checks that allowlist on every swap and deposit rather than relying on frontend restrictions.
- Virtual Balances: The regulated token never enters the PoolManager; a permissions adapter holds it while v4's accounting prices trades against a virtual representation that exists only inside Uniswap.
- Locked Positions: Liquidity position NFTs in permissioned pools cannot be transferred, which stops approved LPs from passing regulated exposure to wallets the issuer has not verified.
- Launch Partners: Superstate, Securitize, and Dowgo helped design the standard, with Dowgo adding ERC-3643 support and Securitize extending its earlier work with Uniswap on DS Protocol tokens.
- OKXICE Venue: The OKX and ICE joint venture filed an SEC notice on 4 October 2026 to trade 60-plus US stocks against stablecoins in permissioned v4 pools on X Layer.
- Regulatory Basis: The venue relies on the SEC's five-year Innovation Exemption from 17 September 2026, which lets issuers object; Cerebras and several other companies have already opted out.
Unichain: The Layer 2 Built Around v4
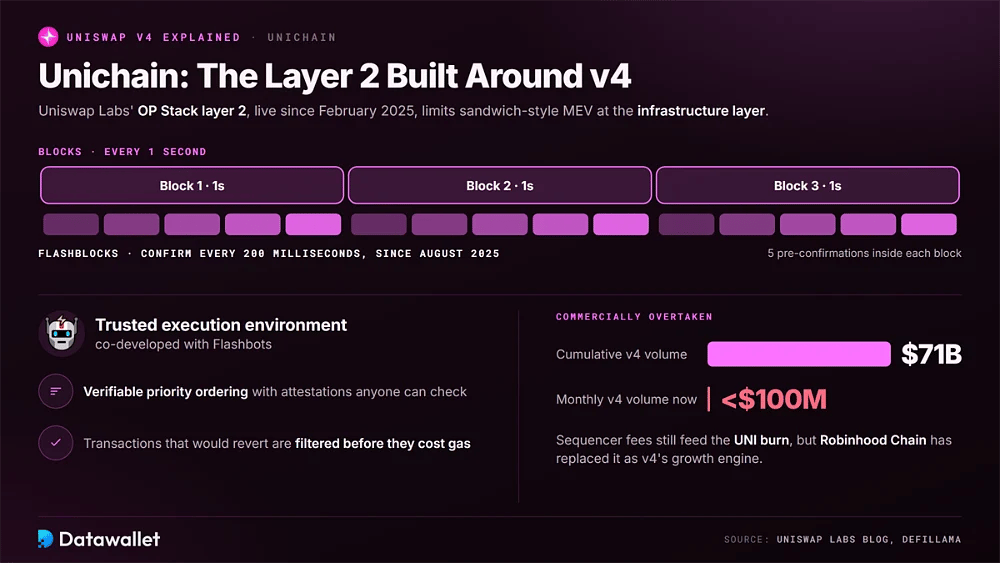
Unichain is Uniswap Labs' OP Stack layer 2, launched on mainnet in February 2025 as a settlement venue built around the protocol. It produces one-second blocks and, since August 2025, Flashblocks that confirm transactions every 200 milliseconds inside a trusted execution environment co-developed with Flashbots.
That hardware environment enforces verifiable priority ordering, with attestations anyone can check, and filters transactions that would revert before they cost users gas. Few rollups expose their sequencing to audit this way, which is why Unichain remains the cleanest example of limiting sandwich-style MEV at the infrastructure layer rather than inside pools.
Commercially, Unichain has been overtaken. It still accounts for about $71 billion of v4's cumulative volume, yet DefiLlama now records under $100 million in monthly v4 volume there. Its sequencer fees still feed the UNI burn, but Robinhood Chain has replaced it as v4's growth engine. Add it to MetaMask with our Unichain network guide.
MEV and LP Economics on Uniswap v4
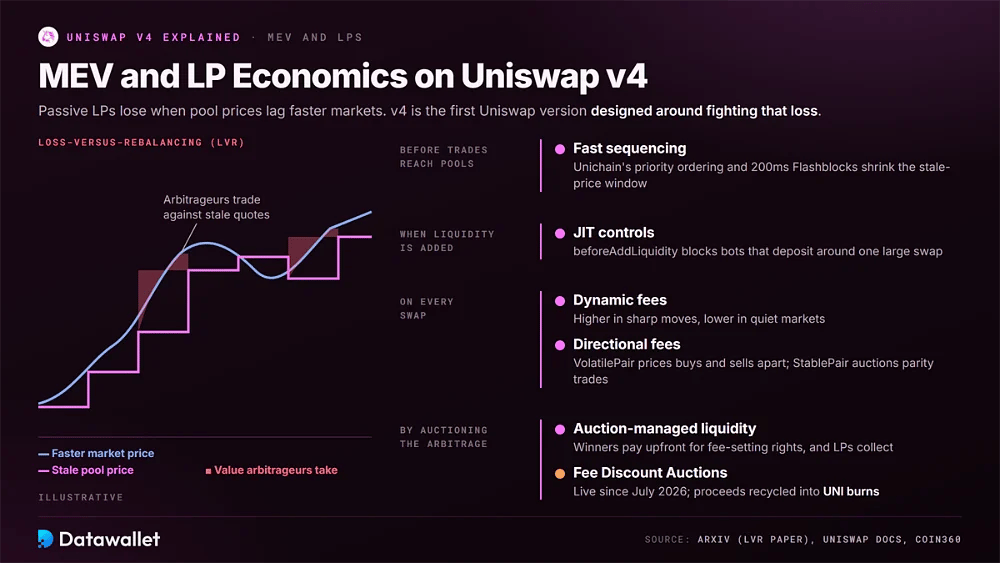
Passive LPs lose money when pool prices lag faster venues and arbitrageurs trade against stale quotes. Research calls this loss-versus-rebalancing, and v4 is the first Uniswap version designed around fighting it.
The mitigation tools now running in production include:
- Dynamic Fees: Hooks raise fees during sharp price moves and lower them in quiet markets, taxing arbitrage when it is most profitable while staying competitive for ordinary trading flow.
- Directional Fees: VolatilePair charges buys and sells separately, and StablePair waives fees on trades pushing price further from parity while auctioning the trades that restore it.
- Auction-Managed Liquidity: Some hooks auction the right to set a pool's fee and capture its arbitrage, turning loss-versus-rebalancing into an upfront payment that flows back to liquidity providers.
- JIT Controls: The beforeAddLiquidity callback lets pools block just-in-time liquidity, where bots deposit around one large swap to skim fees and withdraw before resident LPs benefit.
- Fee Auctions: Protocol Fee Discount Auctions, which ran their first live auctions in July 2026, sell short windows of fee-free swapping and recycle the proceeds into UNI burns.
- Fast Sequencing: On Unichain, hardware-enforced priority ordering and 200-millisecond Flashblocks shrink the window in which stale prices can be picked off, cutting LVR before trades reach pools.
UNIfication and the v4 Fee Switch
The biggest Uniswap story since launch happened in governance. UNIfication passed in December 2025 with 125.3 million UNI in favour, and Proposal 100 extended protocol fees to v4 pools on 27 July 2026.
The fee rollout now affecting v4 traders and LPs includes:
- Treasury Burn: UNIfication burned 100 million UNI from the treasury, roughly what fees would have destroyed had the switch been active since the token launched in 2020.
- Legacy Pools: Protocol fees went live on v2 and v3 pools from 28 December 2025 and reached 11 chains by mid-2026, funding about 7.5 million UNI in burns by July.
- Proposal 100: Passed 46.6 million UNI to 1.27 million, it switched on v4 fees simultaneously across Ethereum, Arbitrum, Base, BNB Chain, Polygon, OP Mainnet, and Robinhood Chain.
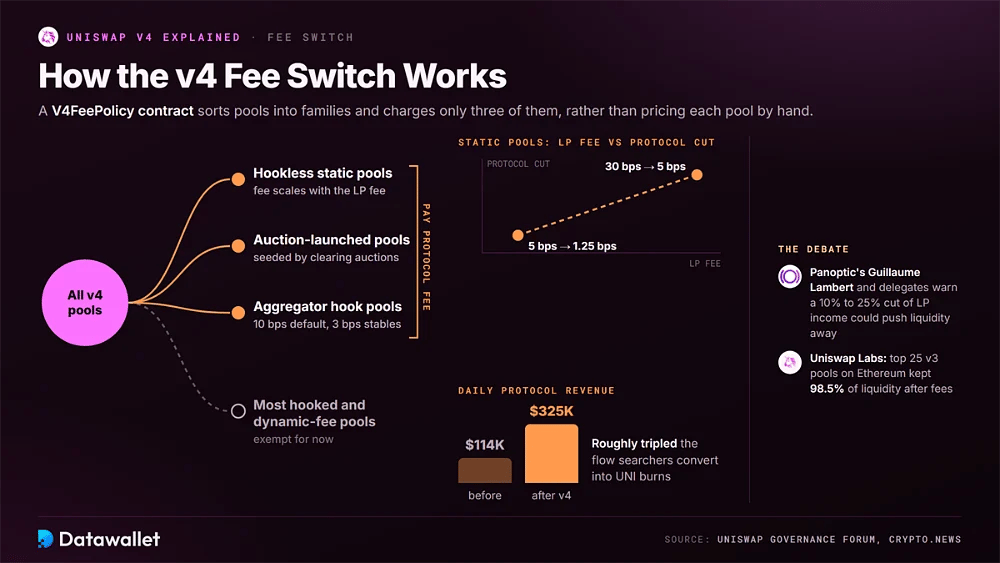
- Fee Families: Rather than pricing each pool, a V4FeePolicy contract sorts pools into families, applying fees only to hookless static pools, auction-launched pools, and aggregator hook pools.
- Fee Curve: Static pools pay a protocol cut that scales with the LP fee, so a 30 bps pool contributes 5 bps and a 5 bps pool contributes 1.25 bps.
- Revenue Impact: Daily protocol revenue rose from about $114,000 to $325,000 after v4 fees went live, roughly tripling the flow that searchers convert into UNI burns.
- Hooked Pools: Most hook-based and dynamic-fee pools remain exempt, while a companion Part 2 vote was planned to carry v4 fees to the remaining fee-enabled chains.
The rollout has not been frictionless. Panoptic founder Guillaume Lambert and several delegates warned that taking 10% to 25% of LP income on v4 could push liquidity elsewhere. Uniswap Labs countered that the 25 largest v3 pools on Ethereum kept 98.5% of their liquidity after fees, and promised to adjust if v4 suffers.
Uniswap v4 vs v3
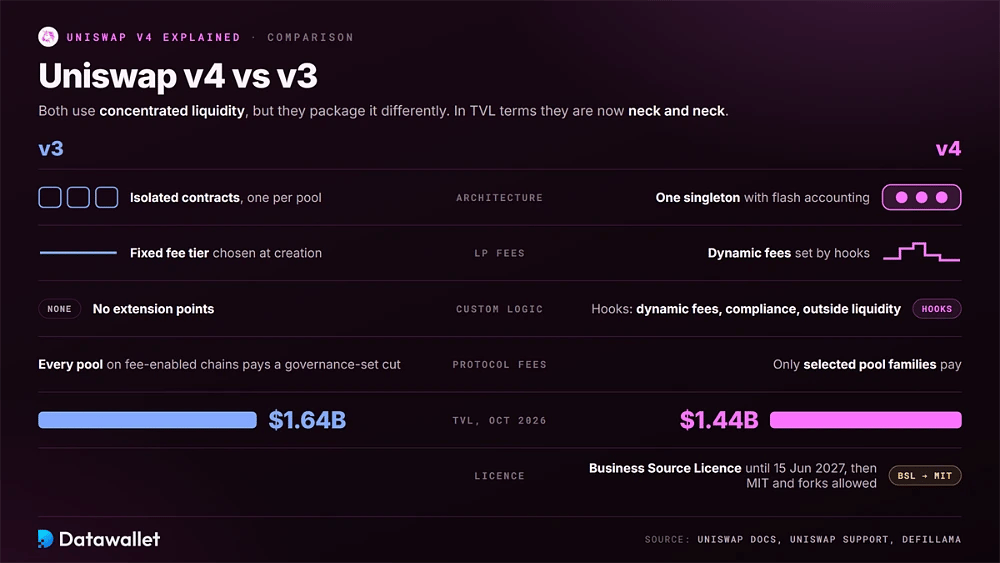
Both versions use concentrated liquidity, but they package it differently. v3 pools are isolated contracts with fixed fee tiers and no extension points, while v4 pools share a singleton, settle through flash accounting, and can attach hook logic ranging from dynamic fees to compliance checks and external liquidity wrappers.
Traders see cheaper multi-hop routes and access to pools v3 cannot host, such as permissioned securities and MEV-resistant markets. LPs gain new strategies but must understand each hook. In TVL terms the versions are now neck and neck, with v3 at $1.64 billion and v4 at $1.44 billion.
Fees now apply to both, though differently. Every v3 pool on fee-enabled chains pays a governance-set cut, whereas v4 charges only selected pool families. v4's code also sits under a Business Source Licence until 15 June 2027, when it converts to MIT and direct forks become possible.
Hook Risk: The Bunni Lesson
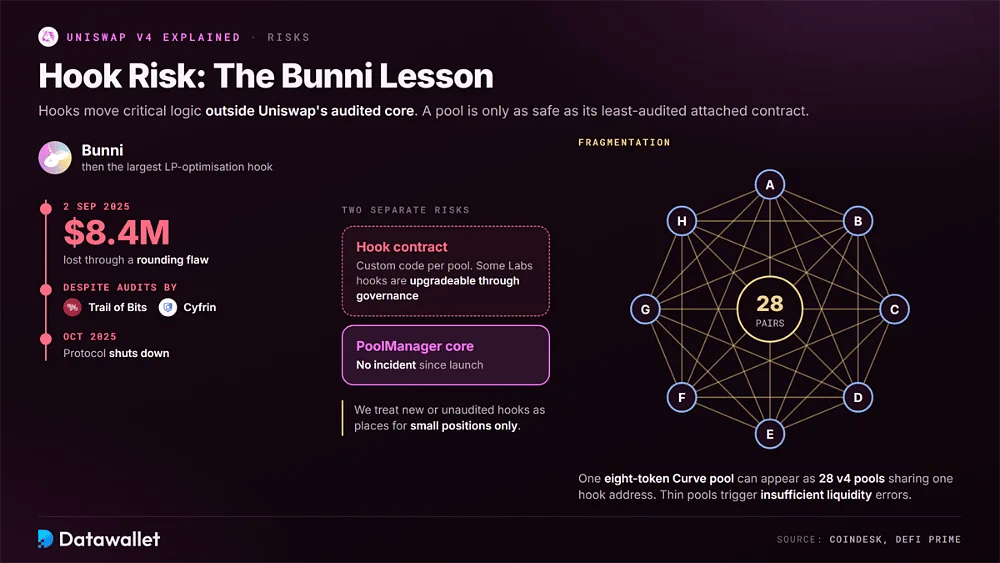
Hooks move critical logic outside Uniswap's audited core, and 2025 showed the cost. Bunni, then the largest LP-optimisation hook, lost about $8.4 million on 2 September 2025 through a rounding flaw, despite audits from Trail of Bits and Cyfrin. The team shut the protocol down that October.
The PoolManager itself has operated without incident since launch, so protocol risk and hook risk are separate questions. A pool is only as safe as its least-audited attached contract. We treat new or unaudited hooks as venues for small positions, and some Labs-built hooks are now upgradeable through governance, adding a different trust assumption.
Fragmentation is the second cost. One pair can exist across many v4 pools with different hooks, plus v3 and v2, and aggregator hooks can show one eight-token Curve pool as 28 v4 pools sharing a hook address. Thin pools can trigger insufficient liquidity errors, so routing matters more than ever.
Final Thoughts
Uniswap v4 set out to stop competing on features and start competing as infrastructure, and 2026 largely validated that bet. Tokenised stock venues, stablecoin markets, launchpads, and even rival DEX liquidity now plug into v4 through hooks, while cumulative volume has climbed past $484 billion in under two years.
The open question has shifted from whether v4 earns revenue to how much it can take without driving LPs away. Fees now flow from selected v4 pools and aggregator routes into UNI burns, but hooked pools remain mostly exempt. For the protocol's origins, see our guide to what Uniswap is.