
Decentralized exchanges now handle a meaningful slice of global spot trading, and Uniswap remains the venue most other DEXs measure themselves against. Its automated market maker design became the template for much of DeFi.
No year since launch has reshaped the protocol like 2026. Fee burns expanded to v4 pools, Robinhood Chain became its busiest network, tokenized stocks went live in its apps, and CME prepared regulated UNI futures.
For investors and researchers, the challenge is separating durable usage from short-lived token narratives. Below is what matters before forming a view on Uniswap. 👇
What is Uniswap?
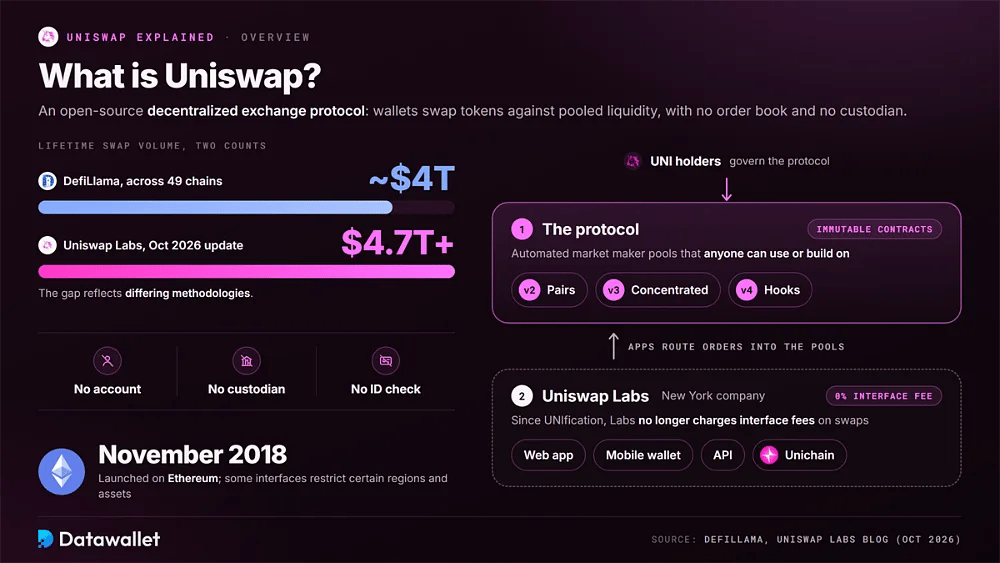
Uniswap is an open-source decentralized exchange protocol that lets people trade digital tokens directly from wallets they control. It began on Ethereum, and swapping against its smart contracts requires no account, no deposit into a custodian and no identity check, although some interfaces restrict certain regions and assets.
Instead of pairing buyers with sellers in an order book, Uniswap relies on an automated market maker (AMM). Traders swap against pools of tokens deposited by liquidity providers, and a pricing formula updates the exchange rate after every trade based on how the balance between the pool's two assets shifts.
Launched in November 2018, it is the reference point among decentralized exchanges. DefiLlama tracks nearly $4 trillion in cumulative swaps across 49 chains, while Uniswap Labs cites more than $4.7 trillion in lifetime protocol volume in an October 2026 update. The gap reflects differing methodologies.
Two layers are worth keeping apart. The protocol is a set of immutable contracts anyone can use or build on, governed by UNI holders. Uniswap Labs is the New York company behind the web app, mobile wallet, API and Unichain, and since UNIfication it no longer charges interface fees on swaps.
How Does Uniswap Work?
Uniswap swaps settle against pooled capital rather than a matching counterparty. Four building blocks explain nearly everything users touch: the pool formula, concentrated liquidity, the apps and routing layer above it, and the governance system that sets its rules.
1. Liquidity Pools and the AMM
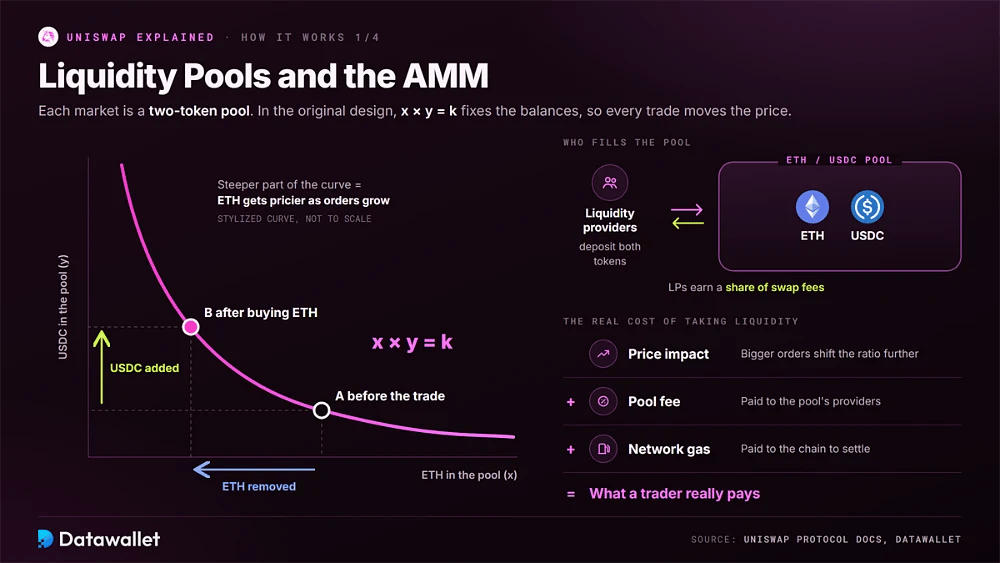
Each market is a pool containing two tokens, such as ETH and USDC. Liquidity providers deposit both assets and collect a share of swap fees. In the original design, a constant-product rule (x × y = k) fixes the relationship between the two balances, so the price moves whenever one side changes.
Buying ETH from that pool adds USDC and removes ETH, pushing the ETH price higher along the curve. Bigger orders shift the ratio further, which shows up as price impact. That impact, plus the pool fee and network gas, is the real cost a trader pays to take liquidity.
2. Concentrated Liquidity
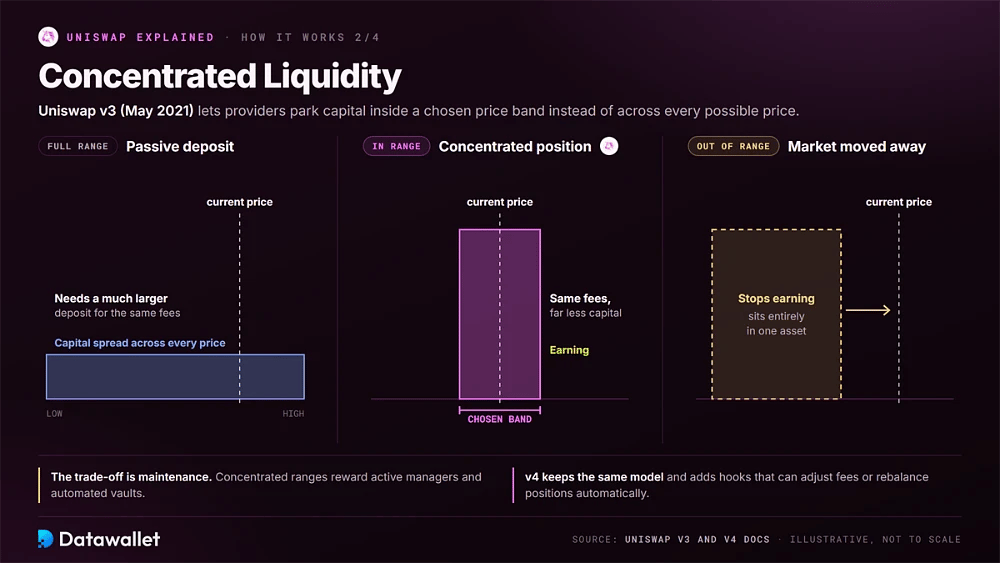
Uniswap v3 arrived in May 2021 with concentrated liquidity, allowing providers to place capital inside a chosen price band instead of across every possible price. A position covering only the range where a pair usually trades can earn the same fees as a much larger passive deposit.
The trade-off is maintenance. Once the market moves outside a provider's band, that position stops earning and sits entirely in one asset. Concentrated ranges therefore reward active managers and automated vaults, and v4 keeps the same model while adding hooks that can adjust fees or rebalance positions automatically.
3. Uniswap Apps and Products
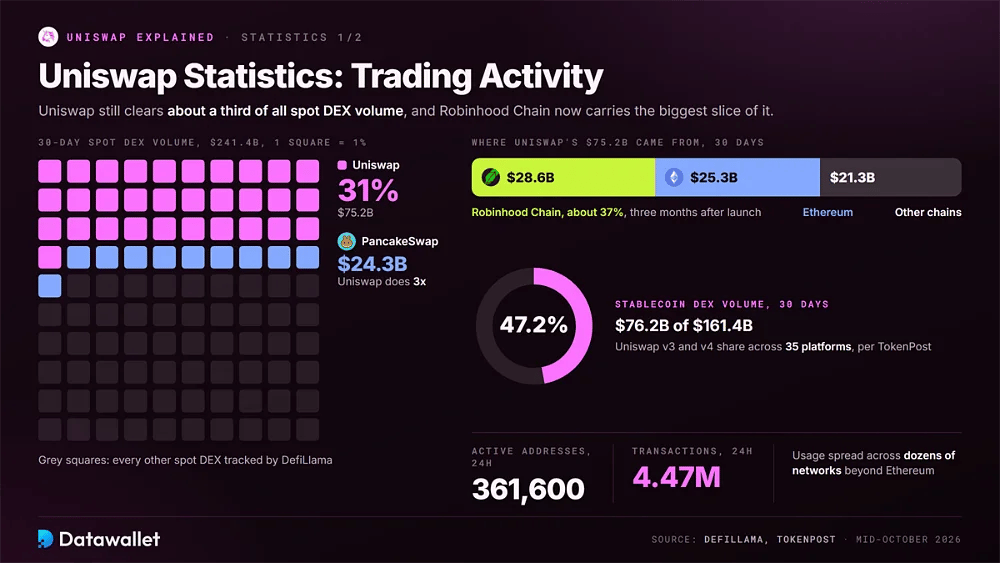
Most people never touch the raw contracts. They reach Uniswap through apps and services built by Uniswap Labs, which route orders across versions and chains while adding features that a basic pool cannot provide alone.
The main ways users interact with Uniswap in 2026:
- Web App: The app.uniswap.org interface searches v2, v3 and v4 pools for the best route, then shows price impact, network fees and minimum output before each swap is signed.
- Mobile Wallet: A self-custodial wallet for iOS and Android stores keys on the device, supports major EVM networks, and puts swaps, token discovery and portfolio balances in one screen.
- UniswapX: Users sign an intent describing the outcome they want, and competing fillers settle it through a Dutch auction, covering gas and sourcing liquidity across pools and chains.
- Earn: Launched in July 2026, Earn lets users deposit USDC, USDT or ETH into Morpho-powered vaults from the web app or wallet, adding passive yield without managing pool ranges.
- Tokenized Stocks: Since June 2026, eligible users can find tokenized versions of shares such as Apple, Tesla and NVIDIA on the Explore page, subject to issuer KYC and jurisdiction rules.
- Launches: A launch aggregator tab and onchain token auctions let projects run price discovery on Uniswap, with partner launchpads such as Pools.trade serving new tokens on Robinhood Chain.
- Uniswap API: Wallets, fintech apps and agents can plug into the same routing engine through the developer API, gaining access to crypto, stablecoin and tokenized asset liquidity without extra infrastructure.
4. Governance and DUNI
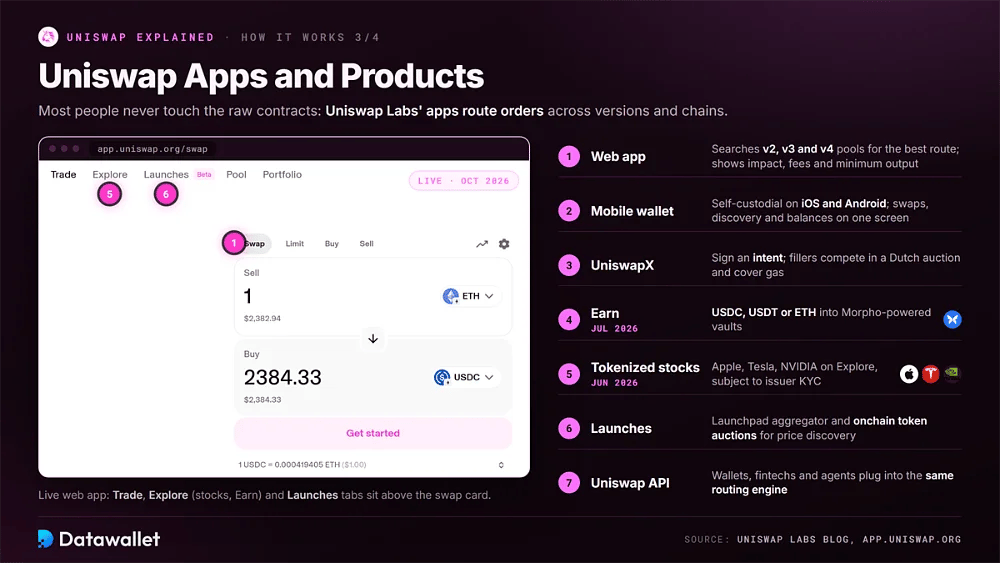
UNI holders steer the protocol by voting on fee parameters, treasury grants, new chain deployments and contract upgrades. Ideas start on the governance forum, move through a temperature check, and pass on-chain through a timelock. Fee expansions now follow a faster track that UNIfication created for routine parameter changes.
In 2025 the DAO adopted DUNI, a Wyoming decentralized unincorporated nonprofit association, as its legal wrapper. The structure gives tokenholders a recognized entity for signing agreements, handling taxes and limiting personal liability, which mattered once governance began directing real protocol revenue and Unichain sequencer income toward UNI burns.
Uniswap Statistics and Trends
Uniswap enters late October 2026 with about $3.9 billion in TVL, its strongest fee quarter since 2021 and a shifting chain mix. The figures below draw on DefiLlama, Uniswap Labs and TokenPost data.
Key Uniswap protocol and UNI metrics as of mid-October 2026:
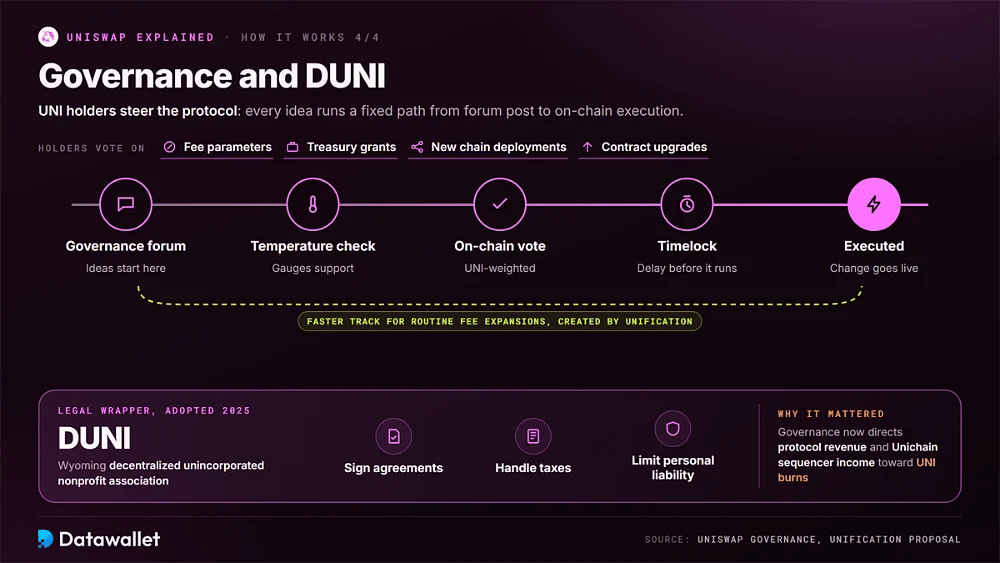
- Market Share: Uniswap processed about $75.2 billion in 30-day DEX volume, roughly 31% of the $241.4 billion tracked across all spot DEXs and triple PancakeSwap's $24.3 billion.
- Robinhood Chain: Robinhood Chain generated $28.6 billion of Uniswap's 30-day volume, about 37% of the total, edging past Ethereum's $25.3 billion only three months after its July launch.
- Fees and Revenue: Swappers paid $120.3 million in fees over 30 days, of which $9.56 million went to the protocol, implying roughly $947 million in annualized fees and $72 million in revenue.
- Record Quarter: Q3 2026 produced $420.2 million in gross swap fees, the best quarter since late 2021, while September alone delivered a record $15.5 million in protocol revenue for burns.
- Liquidity: Uniswap held about $3.93 billion in TVL on October 17, up 8.4% in 30 days, with Ethereum accounting for 63.8% despite most volume now settling elsewhere.
- UNI Supply: UNI supply stands near 887 million after the 100 million treasury burn and ongoing fee burns, with about 625 million tokens circulating and a $4.4 billion market cap.
- Stablecoin Trading: Uniswap v3 and v4 handled $76.2 billion of $161.4 billion in 30-day stablecoin DEX volume, a 47.2% share across 35 venues, according to TokenPost.
- Tokenized Assets: Real-world asset pools on Uniswap had cleared more than $9.1 billion in swaps across 2.6 million transactions from over 140,000 wallets by June 2026.
- Daily Activity: DefiLlama recorded roughly 361,600 active addresses and 4.47 million transactions across Uniswap deployments in a single 24-hour window, showing usage spread across dozens of networks beyond Ethereum.
What is Uniswap V4?
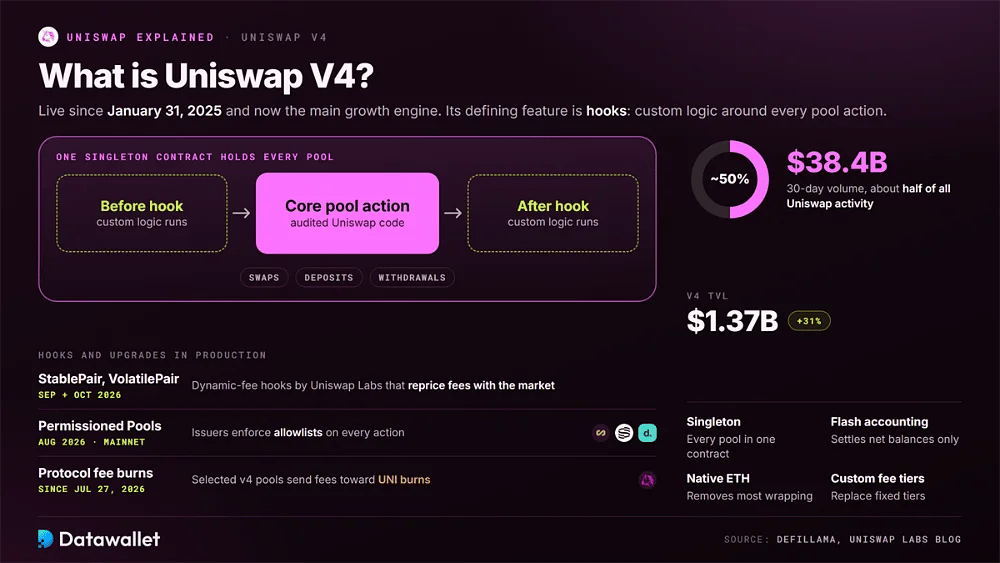
Uniswap v4 went live on January 31, 2025 and is now the protocol's main growth engine. Our Uniswap v4 explainer covers the architecture in depth. DefiLlama shows v4 processing $38.4 billion in 30-day volume, about half of all Uniswap activity, with TVL rising 31% to $1.37 billion.
Its defining feature is hooks, external contracts that run custom logic before or after swaps, deposits and withdrawals. Uniswap Labs has shipped its own, including the StablePair and VolatilePair dynamic-fee hooks released in September and October 2026, which reprice fees with market conditions so liquidity providers retain more value.
Hooks also opened Uniswap to regulated assets. The Permissioned Pools standard, detailed in August 2026, lets issuers enforce allowlists on every swap and liquidity action while the restricted token sits in a dedicated adapter. Superstate, Securitize and Dowgo are building on it, and it is live on Ethereum mainnet.
Architecturally, v4 places every pool inside one singleton contract and settles net balances through flash accounting, cutting gas on pool creation and multi-hop routes. Native ETH removes most wrapping, and custom fee tiers replace fixed ones. Since July 27, 2026, selected v4 pools also contribute protocol fees toward UNI burns.
What is Unichain?
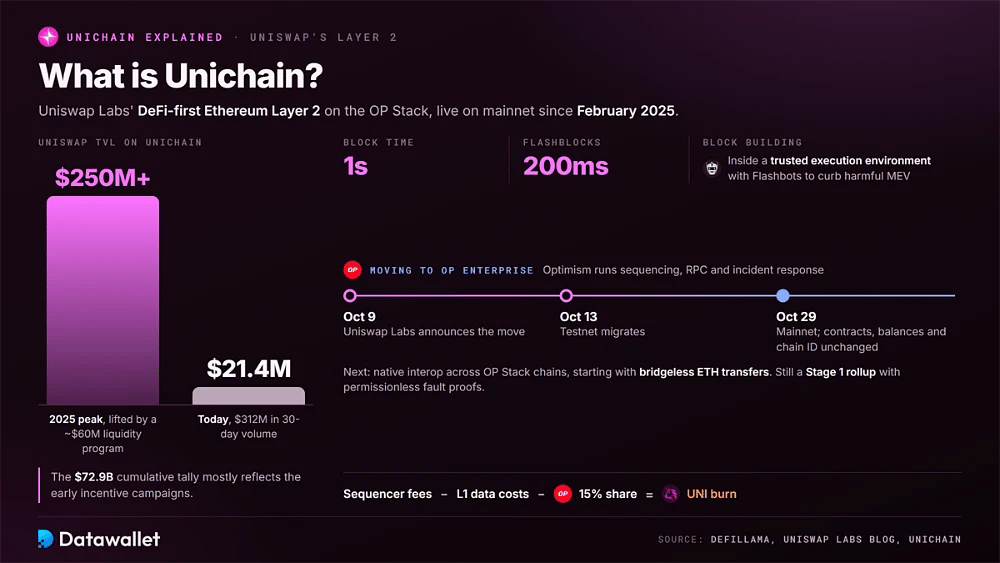
Unichain is Uniswap Labs' Ethereum Layer 2, live on mainnet since February 2025. Built on the OP Stack, it was designed as a DeFi-first rollup with one-second blocks, 200-millisecond Flashblocks and block building inside a trusted execution environment developed with Flashbots to curb harmful MEV.
Usage has cooled since its incentive-fueled start. A roughly $60 million liquidity program lifted TVL above $250 million in 2025, but DefiLlama now shows Uniswap pools there holding about $21.4 million and $312 million in 30-day volume. Unichain's $72.9 billion cumulative tally mostly reflects those earlier campaigns.
The chain is changing operators. Uniswap Labs announced on October 9 that Unichain is moving to OP Enterprise, with testnet migrating October 13 and mainnet on October 29. Optimism will run sequencing, RPC and incident response, while contracts, balances and the chain ID stay unchanged for users.
The upgrade prepares Unichain for native interoperability across OP Stack chains, starting with bridgeless ETH transfers. It remains a Stage 1 rollup with permissionless fault proofs. Economically, net sequencer fees after L1 data costs and Optimism's 15% share flow into the UNI burn, linking chain activity to tokenholders.
UNI Tokenomics
UNI is Uniswap's governance token, and its economics have changed more since late 2025 than in the prior five years. The original allocation still shapes supply, but protocol fees and burns now drive the token's value story.
Token Distribution
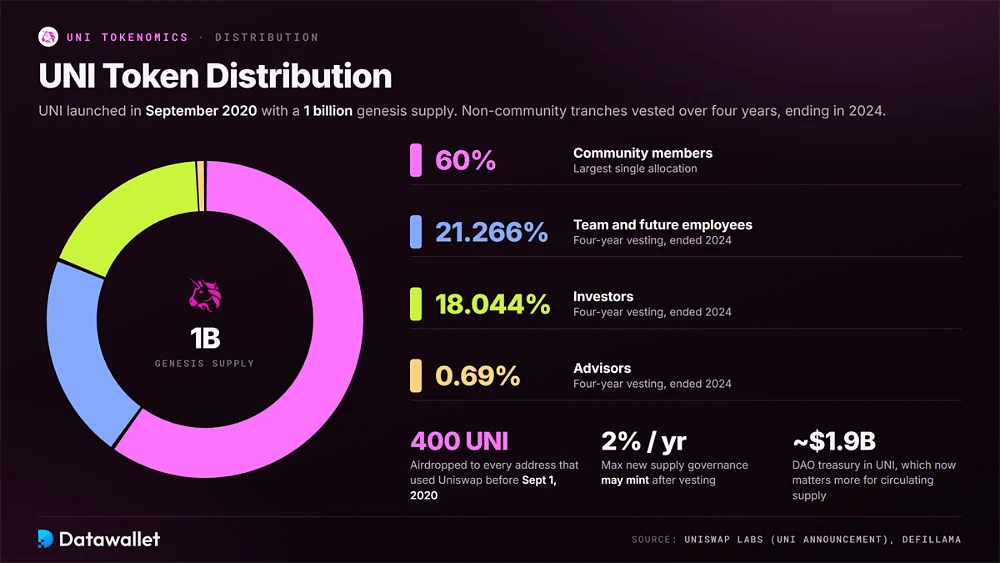
UNI launched in September 2020 with a genesis supply of one billion tokens. The official allocation assigned 60% to community members, 21.266% to team members and future employees, 18.044% to investors and 0.69% to advisors, with non-community tranches vesting over four years that ended in 2024.
Its launch is remembered for a 400 UNI airdrop to every address that used Uniswap before September 1, 2020. After vesting finished, governance gained the option to mint up to 2% new supply each year, although the DAO treasury, worth about $1.9 billion in UNI per DefiLlama, now matters more for circulating supply.
The UNIfication Fee Switch and Burn
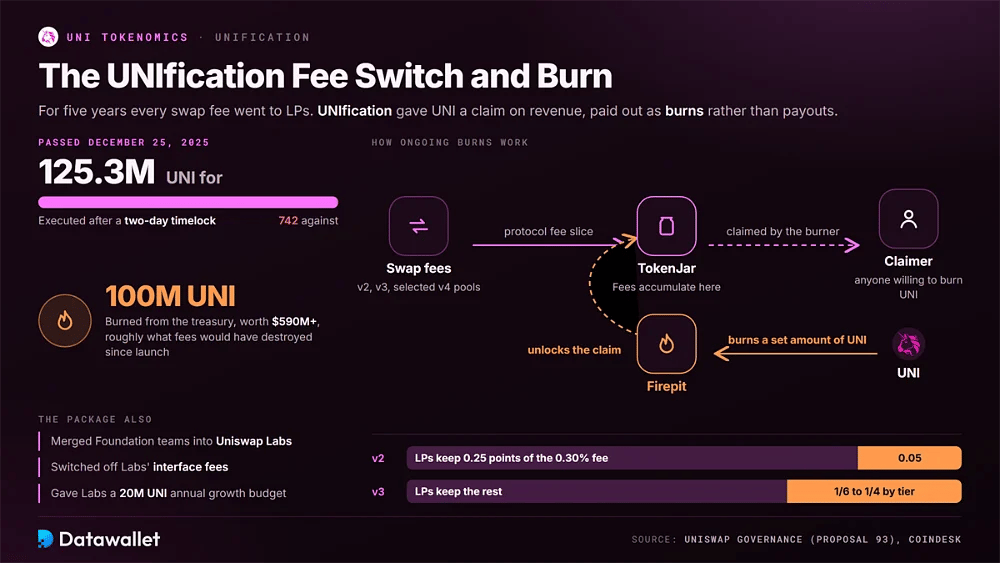
For five years every swap fee went to liquidity providers, leaving UNI with votes but no claim on revenue. The UNIfication proposal changed that, passing on December 25, 2025 with about 125.3 million UNI in favor and only 742 against, then executing after a two-day timelock.
The package burned 100 million UNI from the treasury, roughly what fees would have destroyed since launch, and worth more than $590 million at the time per CoinDesk. It also merged Foundation teams into Uniswap Labs, which switched off its interface fees and received a 20 million UNI annual growth budget.
Ongoing burns work through two contracts. Protocol fees accumulate in TokenJar and can only be claimed by someone who burns a set quantity of UNI through Firepit. On v2, the protocol takes 0.05 percentage points of the 0.30% fee, while on v3 its share ranges from one-quarter to one-sixth, depending on tier.
Fee Switch Rollout Timeline
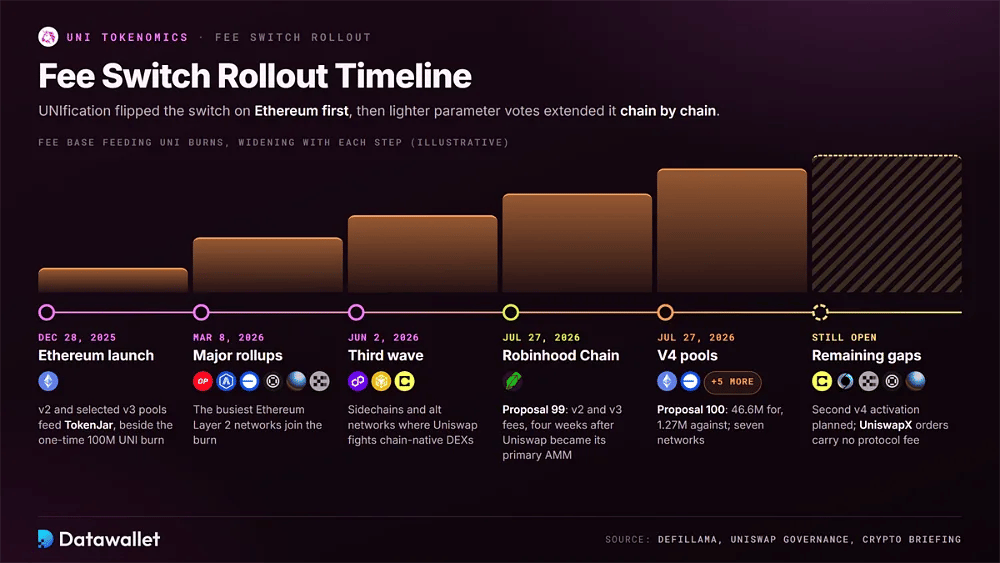
UNIfication flipped the switch on Ethereum first, then governance extended it chain by chain through lighter parameter votes. Each expansion widened the fee base feeding UNI burns, though protocol revenue remains a small slice of swap fees.
How protocol fees spread across Uniswap deployments, according to DefiLlama:
- Ethereum Launch: From December 28, 2025, v2 and selected v3 pools on Ethereum began sending a fee slice to TokenJar, starting continuous buybacks alongside the one-time 100 million UNI burn.
- Major Rollups: On March 8, 2026, protocol fees went live on Optimism, Arbitrum, Base, World Chain, Zora and X Layer, bringing the busiest Ethereum Layer 2 networks into the burn.
- Third Wave: From June 2, 2026, Polygon, BNB Chain and Celo joined the program, extending fee capture to sidechains and alternative networks where Uniswap competes directly with chain-native exchanges.
- Robinhood Chain: Proposal 99 activated v2 and v3 fees on Robinhood Chain on July 27, 2026, about four weeks after Uniswap became the network's primary public AMM at launch.
- V4 Pools: Proposal 100 executed the same day with 46.6 million UNI for and 1.27 million against, switching on fees for selected v4 pools across seven networks, including Ethereum and Base.
- Remaining Gaps: UniswapX orders still carry no protocol fee, and a second v4 activation covering Celo, Soneium, X Layer, World Chain and Zora was planned as a separate step.
Token Utility
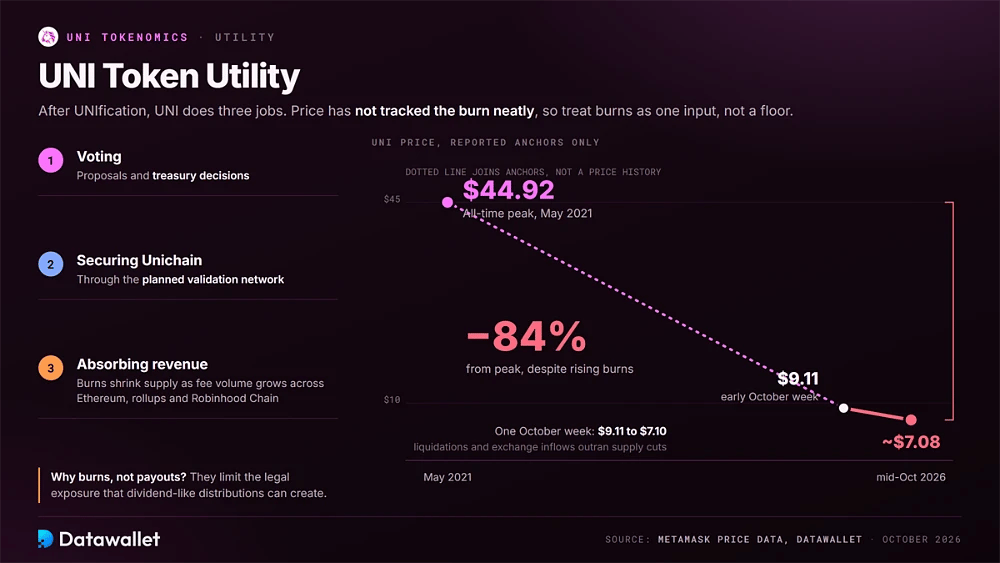
After UNIfication, UNI serves three purposes. It remains the voting token for proposals and treasury decisions, it can secure Unichain through the planned validation network, and it absorbs protocol revenue through burns that shrink supply as fee-generating volume grows across Ethereum, rollups and Robinhood Chain.
Burns were chosen over direct payouts, which limits the legal exposure that dividend-like distributions can create. Price has not tracked the mechanism neatly: UNI traded near $7.08 in mid-October 2026, about 84% below its May 2021 peak of $44.92. Investors should treat burns as one input, not a price floor.
Uniswap Ecosystem and Institutional Adoption
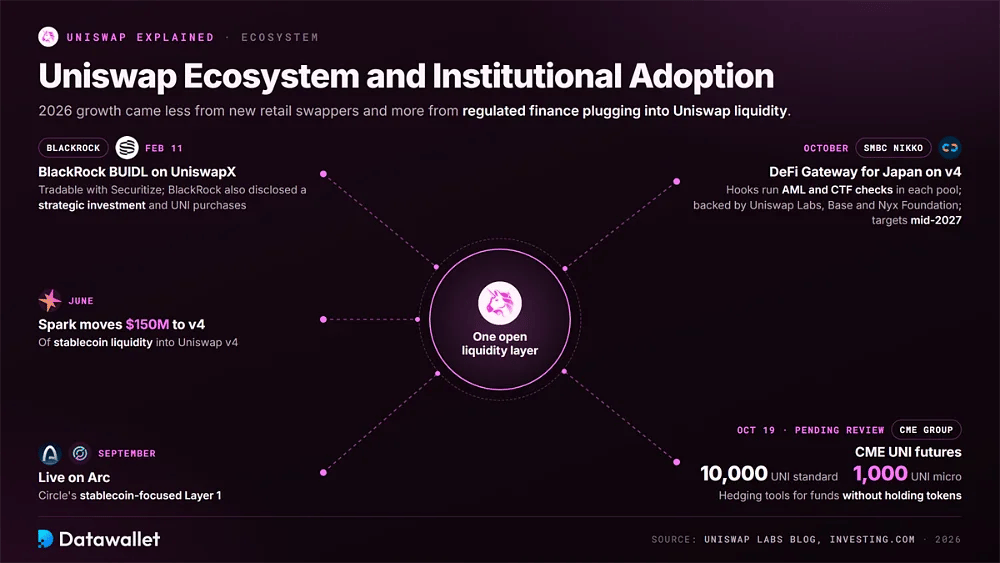
Uniswap's 2026 growth came less from new retail swappers and more from regulated finance plugging into its liquidity. The first signal arrived on February 11, when BlackRock's BUIDL fund became tradable through UniswapX with Securitize, and BlackRock disclosed a strategic investment in the Uniswap ecosystem alongside purchases of UNI.
Japan followed in October. SMBC Nikko and Nethermind are building a DeFi Gateway on Uniswap v4 for Japanese investors, using hooks to run AML and counter-terrorist-financing checks inside each pool. Uniswap Labs, Base and the Nyx Foundation are supporting the venue, which targets completion in mid-2027.
Traditional derivatives markets are also taking notice. CME Group scheduled UNI futures for October 19, 2026, pending regulatory review, offering standard contracts of 10,000 UNI and micro contracts of 1,000 UNI. The listing gives funds hedging tools without holding tokens and places UNI beside CME's existing altcoin futures.
Infrastructure partnerships widened the footprint. Uniswap went live on Arc, Circle's stablecoin-focused Layer 1, in September 2026, while Spark moved $150 million of stablecoin liquidity into v4 in June. These deals point to a model where tokenized funds, stablecoins and equities share the same open liquidity layer rather than walled venues.
Robinhood Chain and Tokenized Stocks on Uniswap
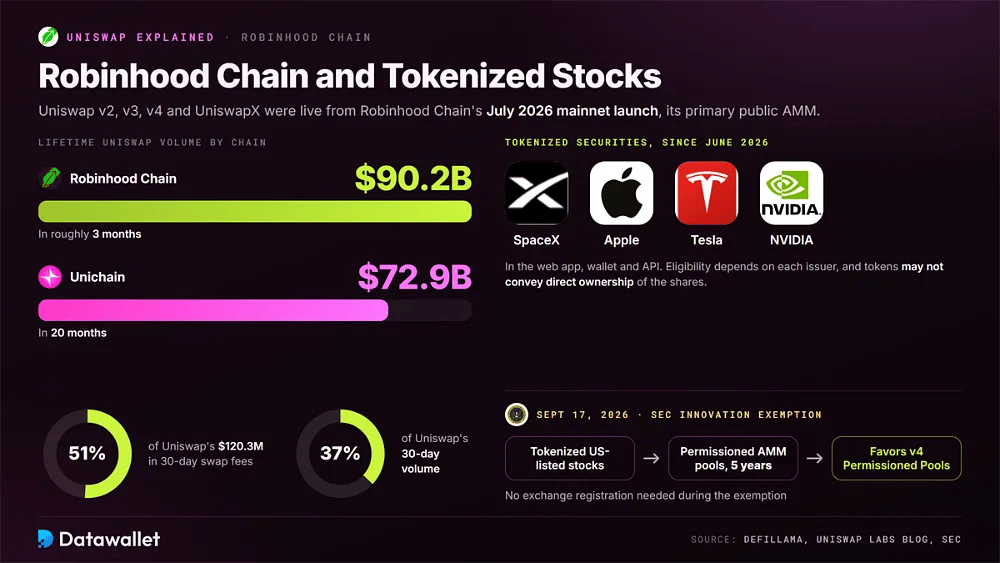
Robinhood Chain became the biggest new source of Uniswap activity in 2026. Uniswap v2, v3, v4 and UniswapX were live from the network's July 2026 mainnet launch, making Uniswap its primary public AMM. Our Robinhood Chain explainer covers how the Layer 2 connects to Robinhood's brokerage users.
The flow arrived fast. Within roughly three months, DefiLlama credited Robinhood Chain with $90.2 billion in lifetime Uniswap volume, already more than Unichain recorded in 20 months. Over the latest 30 days, the chain generated about 51% of Uniswap's $120.3 million in swap fees across all networks.
Tokenized equities are a central theme. In June, Uniswap Labs added tokenized securities such as SpaceX, Apple, Tesla and NVIDIA exposure to its web app, wallet and API. Eligibility depends on each issuer, and the tokens may not convey direct ownership of underlying shares, as Uniswap's own disclaimer states.
Regulation is moving the same way. On September 17, 2026, the SEC set out a five-year Innovation Exemption letting tokenized US-listed stocks trade in permissioned AMM pools without exchange registration. That structure favors Uniswap v4's Permissioned Pools, and our guide to tokenized stock exchanges compares venues competing for this flow.
How Does Uniswap Compare to Other DEXs?
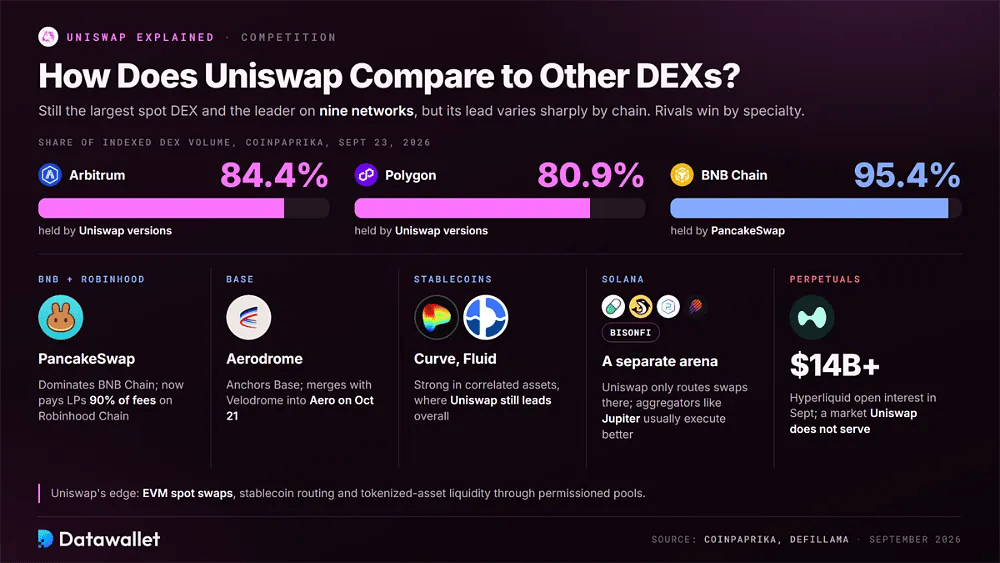
Uniswap remains the largest spot DEX, but its lead varies sharply by chain. A CoinPaprika snapshot from September 23, 2026 showed Uniswap versions carrying 84.4% of indexed DEX volume on Arbitrum and 80.9% on Polygon, while PancakeSwap controlled 95.4% of BNB Chain. Uniswap led nine networks overall.
Rivals now compete by specialty. PancakeSwap dominates BNB Chain and has started paying liquidity providers 90% of fees on Robinhood Chain. Aerodrome anchors Base and merges with Velodrome into Aero on October 21. Curve and Fluid remain strong in stablecoin and correlated-asset markets, where Uniswap still leads overall.
Solana is a separate arena. Pump, Orca, Raydium, Meteora and proprietary AMMs such as BisonFi capture most of its spot flow, and Uniswap's Solana presence is limited to routing swaps in its apps. For that ecosystem, a DEX aggregator like Jupiter usually offers better execution than any single venue.
Perpetual futures are a different category. Hyperliquid dominates on-chain perps, with open interest above $14 billion in September 2026, a market Uniswap does not serve directly. Traders wanting leverage should compare decentralized perpetuals exchanges, while Uniswap's edge stays in EVM spot swaps, stablecoin routing and tokenized-asset liquidity through permissioned pools.
Uniswap Founders and History
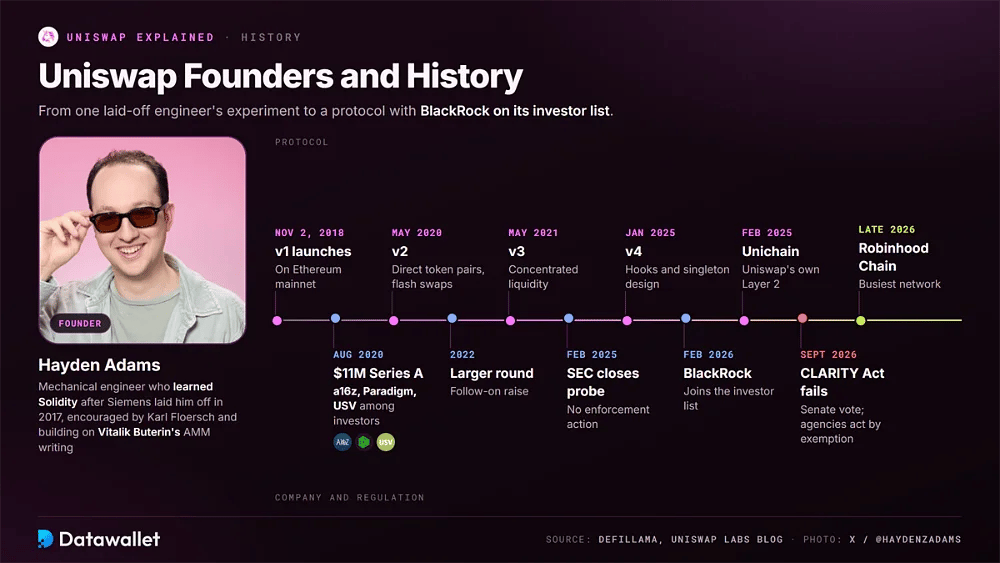
Uniswap was created by Hayden Adams, a mechanical engineer who learned Solidity after Siemens laid him off in 2017. Encouraged by Ethereum researcher Karl Floersch, he built on Vitalik Buterin's writing about on-chain market makers, and the first version launched on Ethereum mainnet on November 2, 2018.
Development moved quickly afterward. V2 in May 2020 added direct token pairs and flash swaps, v3 in May 2021 introduced concentrated liquidity, and v4 in January 2025 brought hooks and the singleton design. Unichain followed in February 2025, and Robinhood Chain became the protocol's busiest venue by late 2026.
Uniswap Labs raised an $11 million Series A in August 2020 from investors including a16z, Paradigm and Union Square Ventures, as DefiLlama records, followed by a larger 2022 round. In February 2026, BlackRock appeared on that investor list, a notable shift for a protocol that began as one developer's experiment.
Regulatory pressure eased in February 2025, when the SEC closed its investigation into Uniswap Labs without enforcement action. The wider US framework remains unfinished, however, after the CLARITY Act failed a Senate vote in September 2026, leaving agencies to act through exemptions and guidance rather than statute.
Risks of Using Uniswap
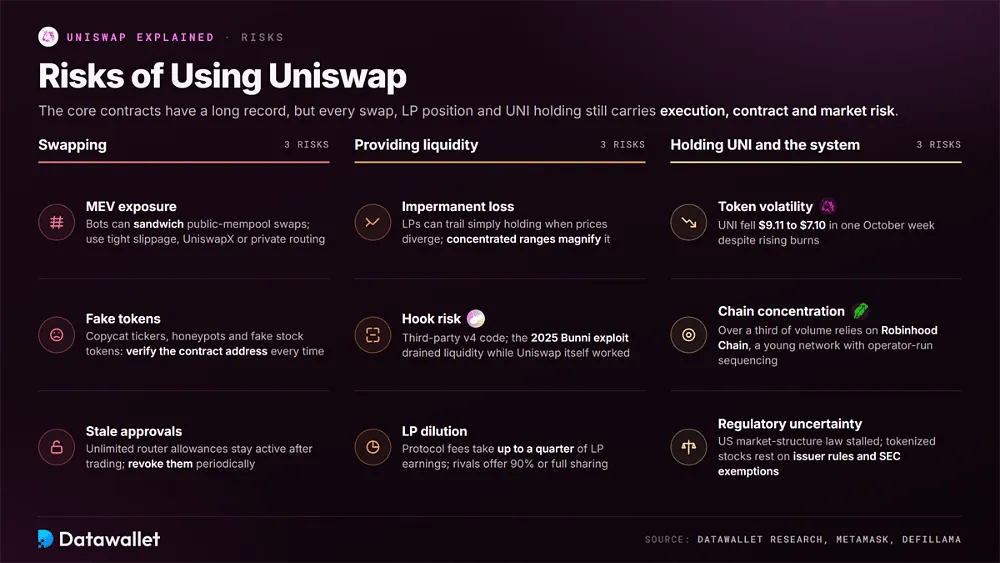
Uniswap's core contracts have a long record, but every swap, liquidity position and UNI holding still carries execution, contract and market risk. Protocol strength and token performance should be judged separately, as 2026 price action showed.
Key risks to weigh before swapping, providing liquidity or buying UNI:
- Impermanent Loss: Liquidity providers can finish behind simply holding both tokens when prices diverge, and concentrated positions magnify the effect once the market exits their chosen range entirely.
- MEV Exposure: Public mempool swaps on Ethereum can be sandwiched by bots, so traders should use tight slippage, UniswapX or private routing to avoid paying hidden execution costs.
- Hook Risk: V4 hooks run third-party code beside the audited core, and the 2025 Bunni exploit showed a flawed hook can drain liquidity even when Uniswap itself works.
- Fake Tokens: Anyone can open a pool for any asset, so copycat tickers, honeypots and fake stock tokens appear constantly, making contract-address verification essential before every purchase.
- Stale Approvals: Unlimited allowances granted to Uniswap routers stay active after trading stops, so periodically revoking token permissions limits damage if a wallet or contract is compromised later.
- LP Dilution: Protocol fees now take up to a quarter of LP earnings on affected pools, and providers could migrate to rivals offering 90% or full fee sharing.
- Token Volatility: UNI fell from about $9.11 to $7.10 in one October week despite rising burns, showing that liquidations and exchange inflows can overwhelm supply reduction in the short term.
- Chain Concentration: Over a third of Uniswap volume now depends on Robinhood Chain, a young network with operator-controlled sequencing, so an outage or policy change there would hit fees quickly.
- Regulatory Uncertainty: US market-structure legislation stalled in 2026, and tokenized stocks depend on issuer rules and SEC exemptions that could change, restricting which assets interfaces may list.
Final Thoughts
Uniswap has evolved from a single Ethereum swap contract into a multichain liquidity layer spanning 49 tracked networks, an intent-based order system, its own Layer 2 and a hook platform others build on. Its constant-product and concentrated-liquidity designs still underpin a large share of decentralized trading today.
The 2026 story is distribution plus value capture. Robinhood Chain, tokenized stocks, BlackRock's BUIDL and CME futures pulled Uniswap closer to traditional finance, while fee burns finally tied UNI to protocol revenue. Annualized protocol revenue near $72 million, however, remains small relative to a $6.3 billion fully diluted valuation.
Several questions remain open: whether liquidity providers accept thinner fee shares, whether Robinhood Chain volume proves durable, and how US rules settle for tokenized assets. Uniswap reads as mature, revenue-producing infrastructure with real execution and market risks, so position sizing and self-custody discipline matter more than headline narratives.