

What is Hyperliquid Improvement Proposal 3 (HIP-3)?
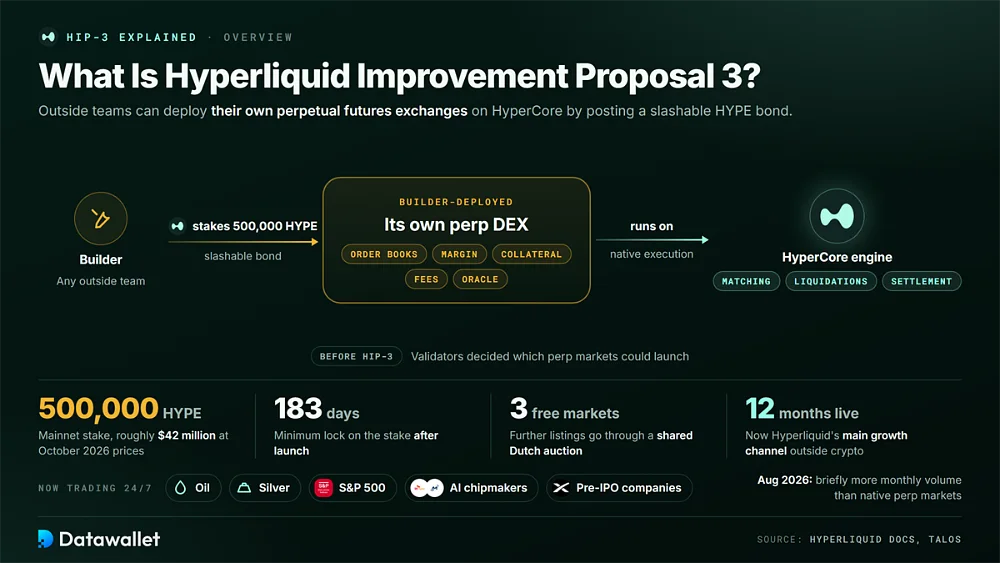
Hyperliquid Improvement Proposal 3, or HIP-3, allows outside teams to deploy their own perpetual futures exchanges on Hyperliquid's HyperCore. Previously, validators determined which perp markets could launch. HIP-3 shifted that listing authority to builders prepared to post a large, slashable HYPE bond.
A deployment operates as a self-contained perp DEX with its own order books, margin settings, collateral token and fee configuration. Builders choose contract specifications and oracle inputs. Hyperliquid's engine handles matching, liquidations and settlement, giving traders native execution infrastructure for assets the core team has not listed.
Mainnet deployers must stake 500,000 HYPE, worth roughly $42 million at October 2026 prices, and leave the stake locked for at least 183 days after launch. The first three markets can be listed for free. Further listings are allocated through a Dutch auction shared across all HIP-3 deployers.
Twelve months after activation, HIP-3 has become Hyperliquid's main growth channel outside crypto. Builder markets now cover oil, silver, the S&P 500, AI chipmakers and pre-IPO companies around the clock. In August 2026, they briefly produced more monthly volume than Hyperliquid's native perpetual markets.
How Does HIP-3 on Hyperliquid Work?
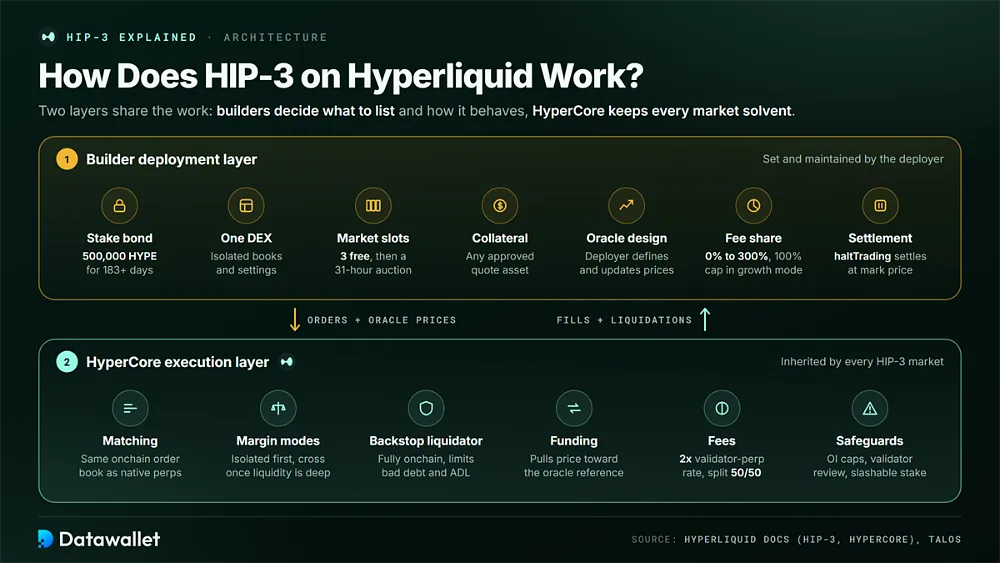
HIP-3 divides responsibility across two layers. Builders determine what to list and configure how each market functions. HyperCore provides the common matching engine, margin system and liquidation machinery that keeps builder-deployed markets solvent and aligned with the infrastructure behind native perps.
1. Builder Deployment Layer
The builder layer covers the decisions and obligations controlled by a deployer before and after launch. These include capital commitments, listing rights, oracle design, fee settings and the continuing responsibility to keep markets accurately priced.
Core deployer responsibilities and settings under the current HIP-3 specification:
- Stake Bond: Deployers lock 500,000 HYPE for at least 183 days. The protocol notes that this requirement should decline as infrastructure matures, with any stake above the required amount available for withdrawal.
- One DEX: A qualifying deployer currently operates one perp DEX with isolated order books and settings. The specification anticipates a future upgrade allowing one stake to support multiple DEXs.
- Market Slots: The first three assets require no auction. Additional assets enter a shared 31-hour Dutch auction, while reserve slots let deployers bypass the timer.
- Collateral Choice: Builders can select any approved quote asset as margin collateral. A validator vote that removes quote status can disable the DEX, although this does not trigger slashing.
- Oracle Design: Deployers define and update oracle prices. The reference feed should follow a liquid, manipulation-resistant underlying because mark prices, funding and liquidations depend on it.
- Fee Share: Deployers may add a fee share from 0% to 300%, capped at 100% in growth mode. When the share exceeds 100%, the protocol fee rises to match it.
- Settlement Control: The haltTrading action cancels orders and settles positions at mark price. Deployers can use it to retire assets or recycle them for dated contracts without buying new auction slots.
2. HyperCore Execution Layer
Execution comes from shared infrastructure. Each HIP-3 market inherits the same onchain order book, margin engine and solvency protections used by native Hyperliquid perps. That common foundation is one reason builder markets can compete with centralized venues on spreads.
Protocol-side functions that every HIP-3 market inherits from HyperCore:
- Matching: HyperCore routes HIP-3 orders through the same onchain central limit order book as native markets. Trading APIs are unified, so integrators only need to change the asset ID.
- Margin Modes: Markets begin with isolated margin. Validators now allow deployers to enable irreversible cross margin on assets that have deep liquidity, dependable external oracles and demonstrated manipulation resistance.
- Backstop Liquidator: Every DEX includes a fully onchain backstop liquidator for underwater positions on cross-margin assets, reducing bad debt and limiting reliance on auto-deleveraging during severe moves.
- Funding: Standard perpetual funding payments pull contract prices toward the deployer's oracle reference. Positions held through weekends or closed trading sessions therefore continue paying or receiving periodic funding.
- Fees: HIP-3 fees are twice the validator-perp rate and are split 50/50 with the deployer. Growth mode reduces all-in costs by more than 90% on participating markets.
- Safeguards: Open interest caps, validator review when cross-margin assets experience a 50% daily oracle move, and slashable stake constrain the damage that a faulty or malicious deployer can cause.
HIP-3 Statistics and Trends
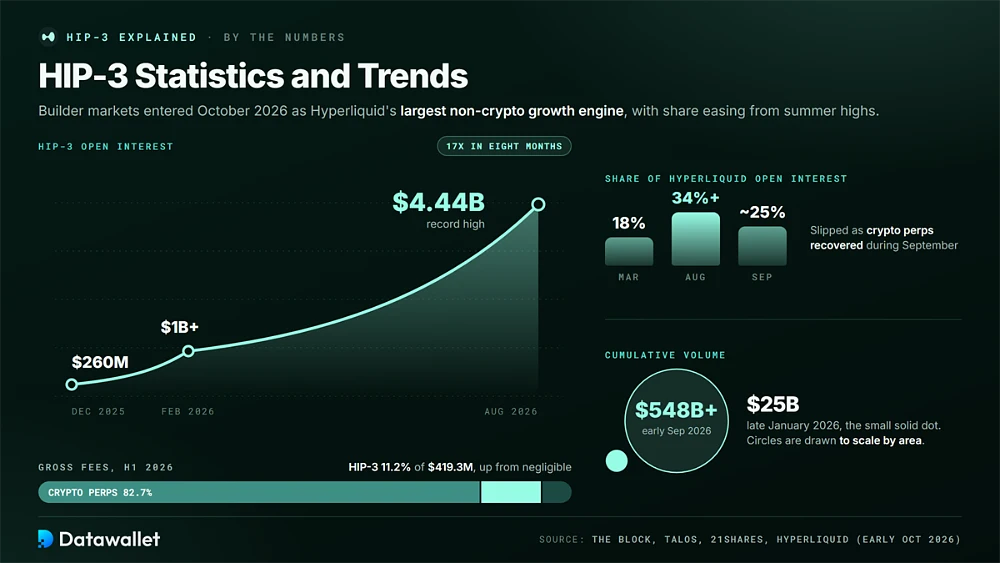
HIP-3 entered October 2026 as Hyperliquid's largest non-crypto growth engine, though its share of overall activity had eased from summer highs. The figures below come from research published by The Block, Talos and 21Shares.
Key HIP-3 metrics as of early October 2026:
- Open Interest: HIP-3 open interest reached a record above $4.44 billion in August 2026, up from about $260 million in late December 2025. That was a seventeen-fold increase in eight months.
- OI Share: HIP-3's share of Hyperliquid open interest rose from 18% in March to more than 34% in August, then slipped to about 25% as crypto perps recovered during September.
- Cumulative Volume: Builder-deployed markets had processed more than $548 billion in cumulative volume by early September 2026, versus roughly $25 billion in late January.
- Volume Share: Trade.xyz markets alone produced about 55% of Hyperliquid's monthly perp volume in August 2026. They overtook native validator-listed markets, showing that non-crypto demand was no longer marginal.
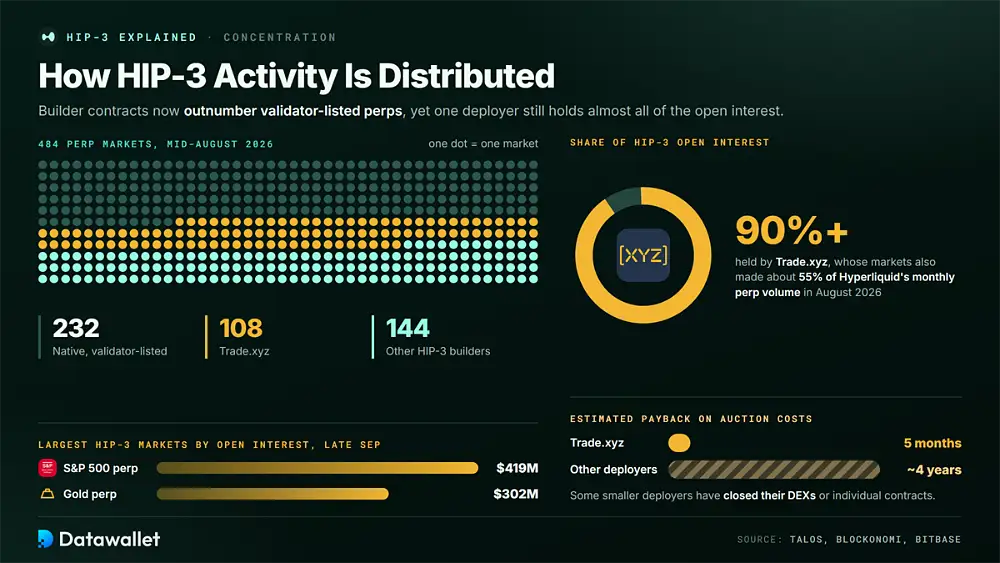
- Market Count: Hyperliquid had 484 perp markets by mid-August: 232 native, 108 from Trade.xyz and 144 from other HIP-3 builders. Builder-deployed contracts therefore outnumbered validator-listed markets.
- Fee Share: HIP-3 went from negligible fee contribution to 11.2% of Hyperliquid's gross fees during the first half of 2026. Crypto perps still represented 82.7% of the $419.3 million total.
- Builder Fees: Trade.xyz generated about $5.0 million in fees during the month through mid-August, divided evenly with the protocol, despite operating in growth mode with heavily reduced trading costs.
- Concentration: Trade.xyz has maintained more than 90% of HIP-3 open interest. Analysts estimate that auction costs imply payback periods of roughly four years for other deployers, compared with five months for Trade.xyz.
- Top Market: An S&P 500-linked perpetual carried roughly $419 million in open interest in late September. Gold was near $302 million, putting both in range of many large-cap crypto perpetual markets.
How HIP-3 Activity Is Distributed
HIP-3's headline growth is spread unevenly across builders and markets. Builder contracts now outnumber validator-listed perps, yet Trade.xyz still holds more than 90% of HIP-3 open interest. Its markets also accounted for about 55% of Hyperliquid's monthly perp volume in August 2026.
The same concentration appears in market economics. Smaller deployers face longer estimated payback periods on auction costs, while some have closed their DEXs or individual contracts. At the same time, non-crypto products such as index, commodity, stock and pre-IPO perps have become substantial sources of volume and open interest.
Latest HIP-3 Developments and Emerging Themes
HIP-3's first year delivered rapid growth while revealing structural pressure points. Activity has become highly concentrated under one deployer. Regulators are still deciding how equity perps should be classified, and newer product designs continue testing how far permissionless market deployment can extend safely.
1. Trade.xyz Dominance and Deployer Consolidation
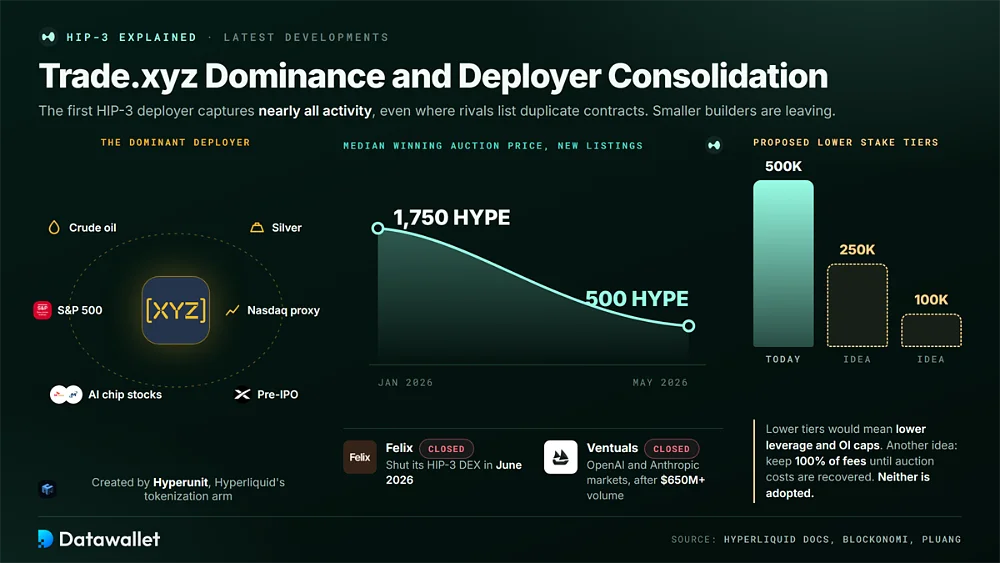
Trade.xyz, created by Hyperliquid's tokenization arm Hyperunit, was the first HIP-3 deployer and remains the dominant venue. Its crude oil, silver, Nasdaq and S&P 500 proxies, AI chip stocks and pre-IPO listings capture nearly all activity, including in markets where competing deployers offer duplicate contracts.
Competition has proved difficult for smaller builders. Felix closed its HIP-3 DEX in June 2026. Ventuals closed its OpenAI and Anthropic markets after processing more than $650 million in volume. Median winning auction prices for new listings also dropped from 1,750 HYPE in January to 500 HYPE by May.
Analysts have proposed tiered stakes of 100,000 or 250,000 HYPE for builders that accept lower leverage and open interest caps. Another proposal would allow new markets to retain up to 100% of fees until auction costs are recovered. Neither has become a protocol change, although Hyperliquid's documentation already indicates that the 500,000 HYPE bond is expected to fall eventually.
2. Regulation, Competition and Other Emerging Themes
Several newer issues now shape how builders, traders and regulators assess HIP-3. They range from Washington's debate over perpetual contracts to oracle failures elsewhere on Hyperliquid that show why price-feed design remains critical.
Emerging HIP-3 themes worth tracking through late 2026:
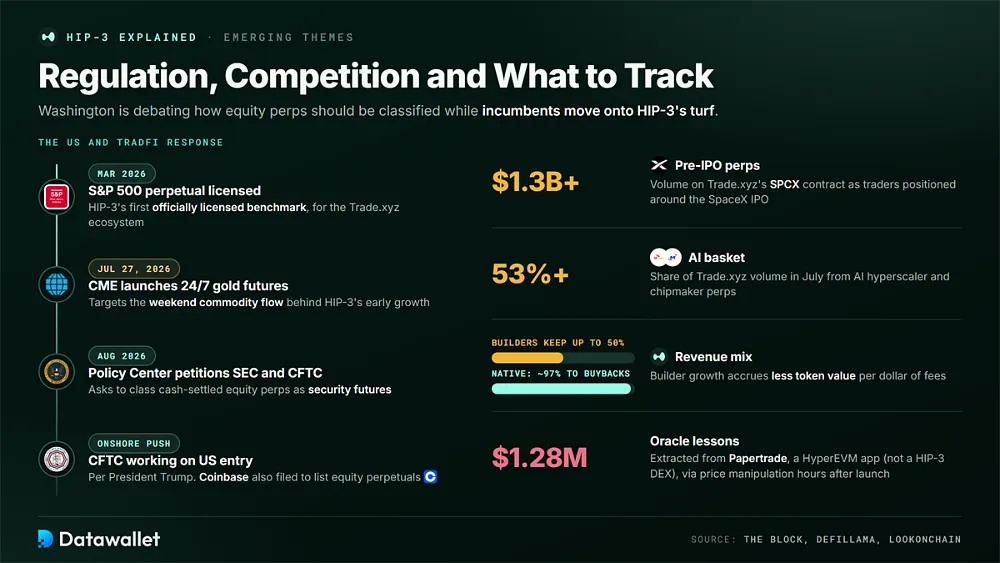
- US Regulation: In August 2026, the Hyperliquid Policy Center asked the SEC and CFTC to classify cash-settled equity perps as security futures, potentially creating a path toward regulated US access.
- Onshore Push: President Trump said the CFTC was working to bring Hyperliquid into the US. Coinbase also filed with the SEC to list equity perpetuals, pointing to incoming domestic competition.
- CME Response: CME introduced 24/7 gold futures on July 27, 2026, targeting the weekend commodity flow that helped drive HIP-3's early growth. Its leadership has also publicly criticized crypto perps.
- Pre-IPO Perps: Trade.xyz's pre-IPO markets allow speculation on private-company valuations. Its SPCX contract generated more than $1.3 billion in volume as traders positioned around the SpaceX IPO.
- AI Basket: AI hyperscaler and chipmaker perps, led by SK Hynix and Micron, represented more than 53% of Trade.xyz volume in July, showing how closely HIP-3 activity can follow equity-market narratives.
- Index Licensing: S&P Dow Jones Indices licensed an S&P 500 perpetual for the Trade.xyz ecosystem in March 2026. It became HIP-3's first officially licensed benchmark and strengthened its intellectual-property footing.
- Revenue Mix: Builders retain as much as half of HIP-3 fees, whereas native crypto perps direct roughly 97% toward HYPE buybacks. Builder growth therefore accrues less token value per dollar of fees.
- Oracle Lessons: Papertrade, a HyperEVM synthetic perps app rather than a HIP-3 DEX, saw a trader extract about $1.28 million by manipulating its order-book-based pricing within hours of launch.
HIP-3 Slashing Explained
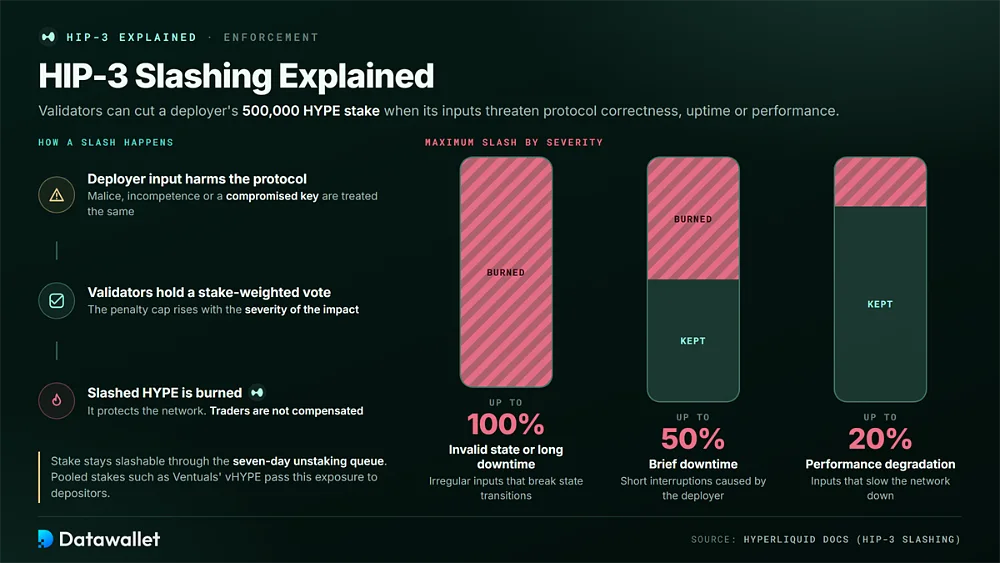
HIP-3 slashing provides the enforcement backstop for builder-deployed markets. Through a stake-weighted vote, validators can cut a deployer's 500,000 HYPE stake when its inputs threaten protocol correctness, uptime or performance. The stake remains slashable during the seven-day unstaking queue, including after withdrawal has started.
Penalty limits rise with the severity of the impact. Irregular inputs that create invalid state transitions or prolonged downtime can result in slashing of up to 100%. Brief downtime can incur up to 50%, while performance degradation carries a maximum of 20%. The rules do not distinguish malicious behavior from incompetence or a compromised deployer private key.
Any slashed HYPE is burned rather than distributed to affected traders. Slashing protects the network rather than individual positions. Liquid staking providers that pool deployer stakes, including Ventuals' vHYPE model, transfer this exposure to depositors, which is why the documentation explicitly recommends careful due diligence.
How to Use HIP-3 Markets
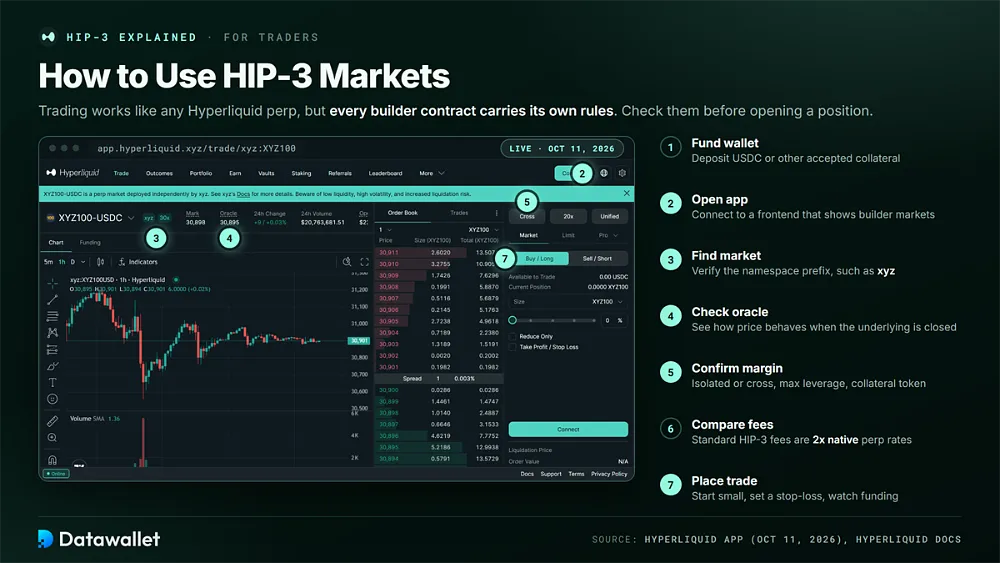
Traders usually access HIP-3 through the Hyperliquid app, integrated wallets or third-party frontends. Builders instead interact directly with deployer actions. Execution resembles native perpetuals, but deployer reputation, oracle design, margin mode and fees require additional review.
1. For Traders
The trading process is similar to any Hyperliquid perp, although every HIP-3 contract can have deployer-specific rules. Checking those settings before opening a position reduces the chance of unexpected behavior around pricing or liquidation.
Follow these steps before opening your first HIP-3 position:
- Fund Wallet: Deposit USDC or another accepted collateral into a Hyperliquid-compatible wallet. Use a bridge if your funds are on another chain, and verify that your country is not restricted.
- Open App: Connect to the Hyperliquid app or another frontend that supports builder markets. Not every interface shows every HIP-3 DEX or namespace automatically.
- Find Market: Search for the asset and verify its namespace prefix, such as xyz for Trade.xyz. Duplicate tickers from different deployers can have materially different rules and liquidity.
- Check Oracle: Examine the deployer's oracle source and how the price behaves while the underlying exchange is closed. Weekend gaps can produce liquidations when traditional markets reopen.
- Confirm Margin: Verify whether the contract uses isolated or cross margin, along with maximum leverage and the collateral token. These settings may differ substantially from native Hyperliquid pairs.
- Compare Fees: Review taker and maker rates and check whether growth mode is enabled. Standard HIP-3 fees are twice native perp rates, which matters for frequent traders.
- Place Trade: Begin with a modest position, set a stop-loss and monitor funding, liquidation price and open interest caps. Pay particular attention around earnings, macro data releases and weekly market opens.
2. For Builders
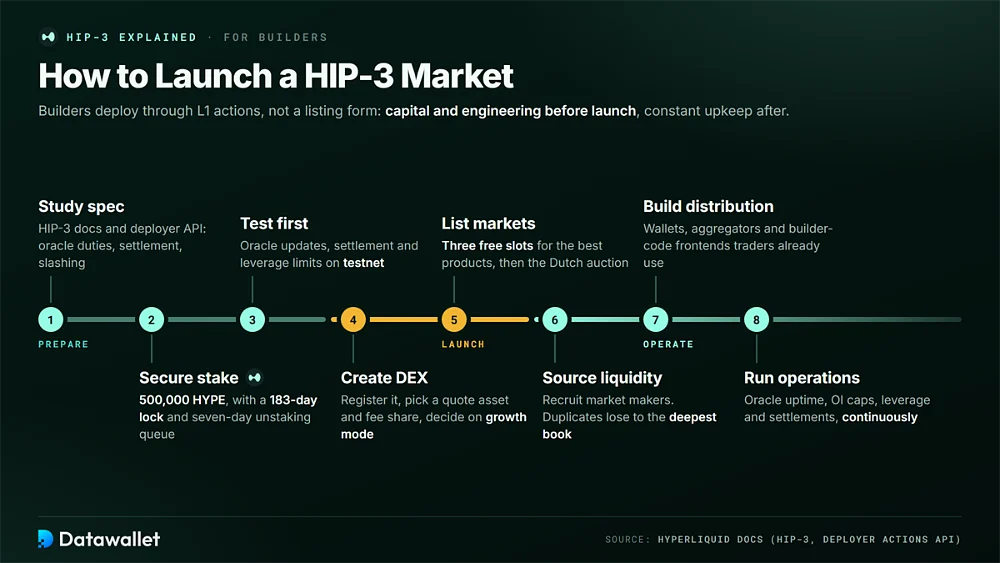
Builders launch HIP-3 markets through Hyperliquid's L1 actions rather than a simple listing interface. A credible deployment therefore requires capital and engineering before launch, along with risk management and a distribution plan once trading starts.
A typical builder launch sequence looks like this:
- Study Spec: Read the HIP-3 specification and deployer actions API. Pay close attention to oracle duties, settlement rules, cross-margin eligibility and slashing guidelines.
- Secure Stake: Acquire and stake 500,000 HYPE directly or through pooled vehicles. Account for the minimum 183-day lock and the seven-day unstaking queue that follows.
- Test First: Deploy on testnet to test oracle updates, settlement logic and leverage limits. Validators assess slashable behavior by protocol impact rather than deployer intent.
- Create DEX: Register the perp DEX, select a quote asset and choose a fee share. Decide whether growth mode should be used to attract early liquidity through lower trading costs.
- List Markets: Allocate the three free slots to the strongest products. Additional assets require participation in the shared Dutch auction or use of reserve deployments for time-sensitive listings.
- Source Liquidity: Recruit market makers or provide liquidity directly. Duplicate contracts generally lose most activity to the deepest existing order book, as smaller deployers experienced in 2026.
- Build Distribution: Integrate with wallets, aggregators and builder-code frontends, or develop a separate interface. Markets need to appear in the applications traders already use.
- Run Operations: Watch oracle uptime, open interest caps, leverage and settlements continuously. The deployer remains responsible for every market for as long as it is trading.
Types of Hyperliquid HIP-3 Markets
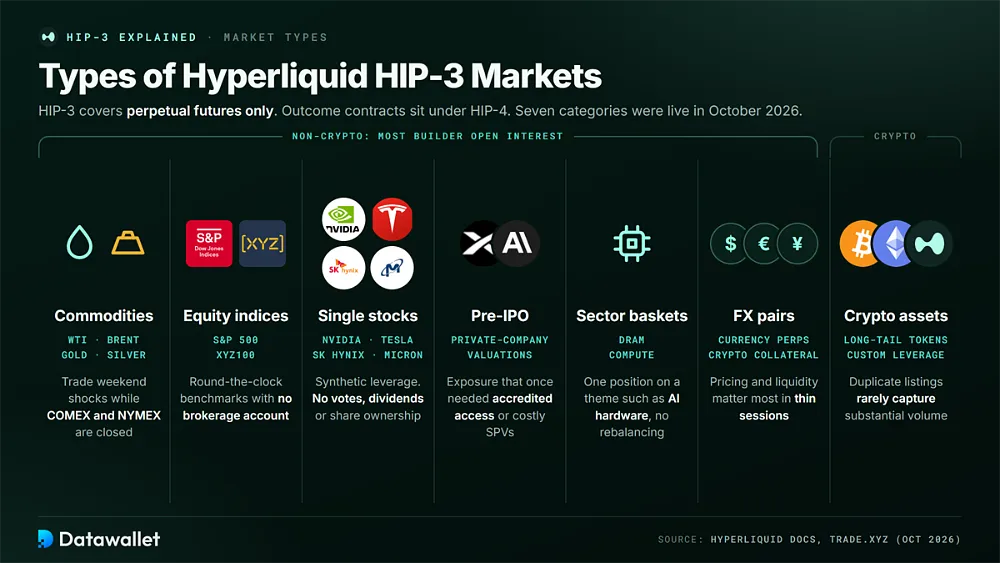
HIP-3 applies only to perpetual futures; outcome contracts sit under HIP-4. Within the perpetual format, builders have expanded into a broad range of underlyings, with non-crypto contracts now accounting for most builder open interest.
The main HIP-3 market categories live in October 2026:
- Commodities: WTI and Brent crude, silver and gold perps powered HIP-3's early breakout. They let traders react to geopolitical shocks during weekends when COMEX and NYMEX are closed.
- Equity Indices: Contracts such as the licensed S&P 500 perpetual and XYZ100, which tracks large US companies, provide round-the-clock benchmark exposure without a traditional brokerage account.
- Single Stocks: Perps on NVIDIA, Tesla, SK Hynix and Micron provide leveraged synthetic exposure. Unlike tokenized stocks, they confer no voting rights, dividends or legal ownership of shares.
- Pre-IPO Companies: These perps let traders speculate on implied private-company valuations, exposure that previously depended on accredited access, secondary markets or costly special-purpose vehicles.
- Sector Baskets: Thematic indices, including DRAM and compute-focused baskets, enable positions on broader industries such as AI hardware without selecting individual companies or managing rebalancing.
- FX Pairs: Currency perps offer leveraged foreign exchange exposure settled in crypto collateral. Reliable pricing and sufficient liquidity are especially important during thin trading sessions.
- Crypto Assets: Builders may still deploy long-tail tokens or alternative versions of existing crypto perps with custom leverage and oracle settings, although duplicate listings rarely capture substantial volume.
HIP-3 Impact on Hyperliquid's HYPE Token
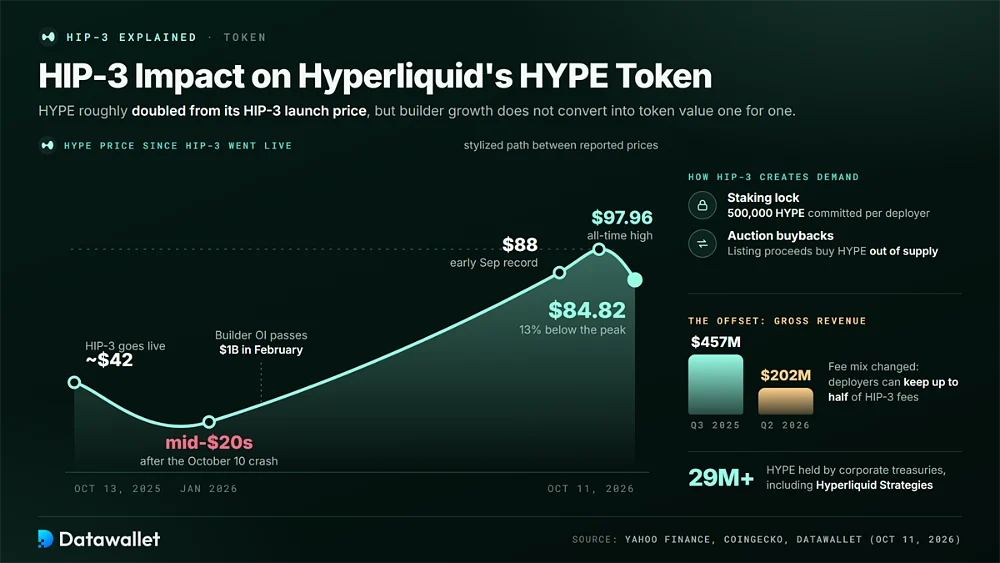
HIP-3 went live on October 13, 2025, while HYPE traded near $42 following an 11% daily gain. The token then declined sharply during the deleveraging that followed the October 10 crash. By January 2026, Yahoo Finance data showed HYPE in the mid-$20s, roughly 40% below its launch-period price.
Its recovery broadly coincided with rising HIP-3 adoption. Builder open interest tripled during January and exceeded $1 billion by February. HYPE later climbed to a record $88 in early September as Hyperliquid's total open interest neared its pre-crash peak. CoinGecko now records the all-time high at $97.96.
On October 11, 2026, HYPE was trading around $84.82, approximately twice its HIP-3 launch price and about 13% below that peak. Corporate treasuries including Hyperliquid Strategies now hold more than 29 million HYPE. Those holdings can be followed through Datawallet's Hyperliquid treasury tracker, alongside the live HYPE price.
HIP-3 adoption does not translate into HYPE value in a simple linear way. Builder markets create staking demand and auction-funded buybacks, but deployers can retain up to half of fees. Hyperliquid's gross revenue also declined from $457 million in Q3 2025 to $202 million in Q2 2026 as the fee mix changed.
How HIP-3 Creates Demand for HYPE
Two mechanisms connect HIP-3 directly with HYPE. Deployers must commit 500,000 HYPE before launching, while proceeds from auctions for additional market listings are used to buy back the token and remove it from circulating supply. Both mechanisms grow alongside builder participation and listing activity.
Fee economics work differently from native perpetual markets, however. Builders can keep as much as half of HIP-3 fees, while native crypto perps direct roughly 97% toward HYPE buybacks. That difference helps explain why growth in builder volume does not translate one-for-one into token value accrual.
Hyperliquid HIP-3 vs HIP-2 vs HIP-1
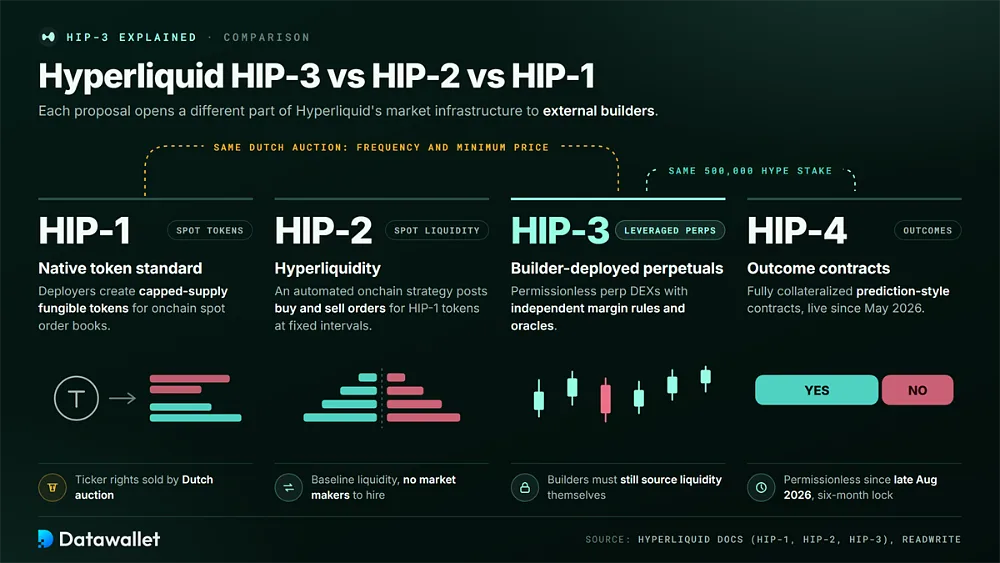
HIP-1, HIP-2 and HIP-3 open different parts of Hyperliquid's market infrastructure to external builders. HIP-1 governs token issuance and spot order books. HIP-2 supplies automated spot liquidity, while HIP-3 extends permissionless deployment to leveraged perpetual futures with independent margin rules and oracles.
HIP-1 is Hyperliquid's native token standard. Deployers can create capped-supply fungible tokens for onchain spot order books, with ticker rights allocated through a Dutch auction. HIP-3 later adopted the same auction structure, including its frequency and minimum price, for additional perp listings.
HIP-2, known as Hyperliquidity, adds an automated onchain strategy that posts buy and sell orders for HIP-1 tokens at fixed intervals. It provides newly launched spot assets with baseline liquidity without requiring deployers to hire market makers, a problem HIP-3 builders still need to solve.
HIP-3 serves as the derivatives counterpart, with HIP-4 now operating alongside it. HIP-4 has been live since May 2026 and covers fully collateralized outcome and prediction-style contracts. Permissionless deployment opened in late August 2026 under the same 500,000 HYPE stake and six-month lock already used by HIP-3 deployers.
Risks of Hyperliquid HIP-3
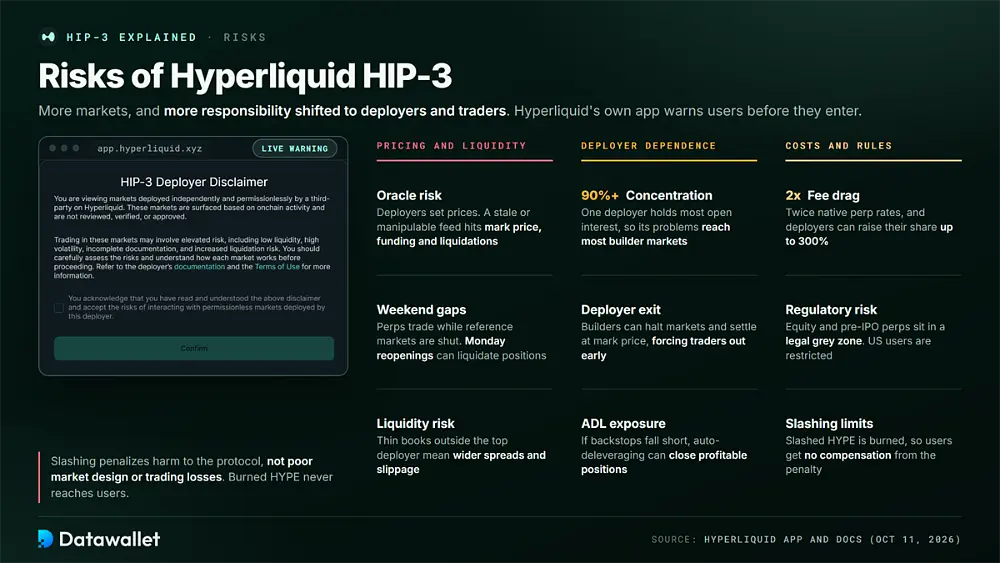
HIP-3 expands the range of markets available on Hyperliquid while shifting more responsibility toward deployers and traders. The largest risks involve oracle quality, limited liquidity, deployer concentration, collateral choices and unresolved regulation surrounding equity-linked derivatives.
Key risks to weigh before trading or deploying on HIP-3:
- Oracle Risk: Deployers determine oracle prices. A stale, manipulable or badly specified feed can affect mark prices, funding and liquidations, particularly when the underlying market is closed.
- Weekend Gaps: Stock and commodity perps trade continuously even when their reference markets are shut. Monday reopenings can cause sharp repricing and liquidate leveraged weekend positions.
- Liquidity Risk: Many HIP-3 order books outside the dominant deployer remain thin. Wider spreads and shallow depth increase slippage and make large exits more expensive in volatile conditions.
- Concentration Risk: One deployer controls more than 90% of HIP-3 open interest. Operational problems, hedging failures or regulatory action affecting it could therefore reach most builder markets simultaneously.
- Deployer Exit: Builders can halt markets and settle positions at mark price, and several have closed operations entirely. Traders may consequently be forced out earlier than intended.
- ADL Exposure: If backstop liquidators cannot absorb losses, auto-deleveraging may close profitable positions. The exposure is greater on isolated-margin assets without onchain backstop liquidator coverage.
- Slashing Limits: Slashing penalizes behavior that harms the protocol, not poor market design or trading losses. Because slashed HYPE is burned, users do not receive compensation from the penalty.
- Fee Drag: Standard HIP-3 fees are twice native perp rates. Deployers can also raise their share up to 300%, allowing costs to erode short-term and high-frequency strategies quickly.
- Regulatory Risk: Equity and pre-IPO perps remain in a legal grey zone, while Hyperliquid's terms restrict US users. Regulatory changes could lead to delistings, geoblocking or narrower interface access.
Final Thoughts
A year after activation, HIP-3 has expanded Hyperliquid beyond crypto perpetuals into a 24/7 venue for oil, metals, indices, chip stocks, and private-company valuations. Builder markets reached over $4.4 billion in record open interest and briefly surpassed native crypto perps in August 2026 monthly volume.
The limitations are clear. Permissionless listings have produced heavy deployer concentration, high entry costs for smaller builders, and fee economics that return less value to HYPE than native markets. Proposed tiered stakes and fee-recovery reforms will test whether broader competition can emerge.
For traders, the practical approach is to use the Hyperliquid app, favor liquid contracts, and verify each deployer’s oracle and margin settings. Position sizing should account for weekend gaps, while US decisions on equity perps will likely shape HIP-3’s next phase.
Hyperliquid’s roadmap now has two parallel tracks. HIP-3 enables open-ended perpetual exposure, while HIP-4 covers bounded outcome contracts. Both use staked HYPE as a quality bond, and their growth will depend on market-structure reforms and the CLARITY Act debate.