







What is Ethena?
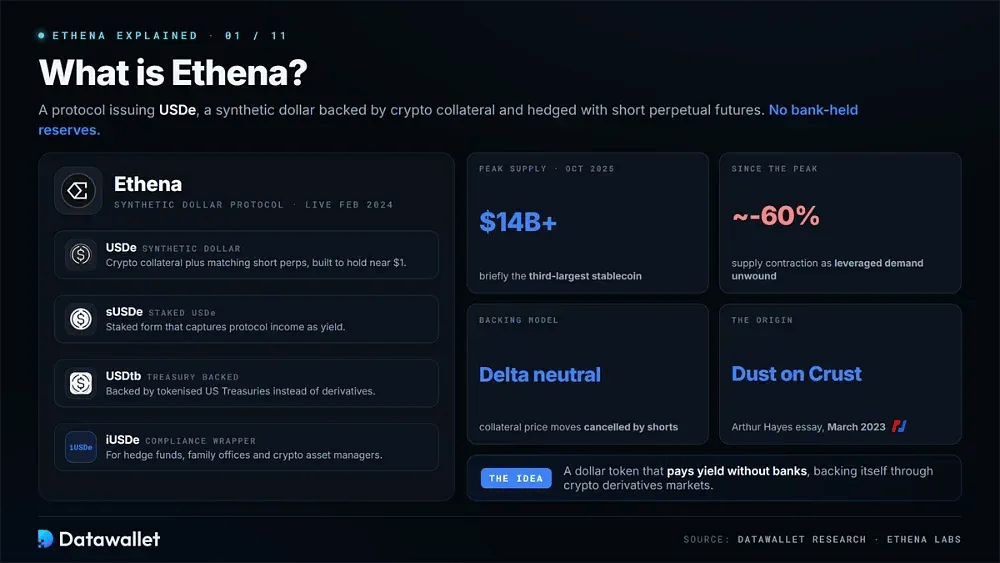
Ethena offers a dollar-denominated token that can pay yield without relying on bank-held reserves. Its USDe synthetic dollar is backed by crypto collateral and hedged with equivalent short positions in perpetual futures markets.
Ethena Labs launched USDe in February 2024. Rather than using bank reserves, the token backs itself through crypto derivatives, drawing on an idea from Arthur Hayes' Dust on Crust essay from March 2023.
Along with USDe and its staked form, sUSDe, Ethena issues USDtb backed by tokenised Treasuries. It also offers iUSDe, a compliance-wrapped version aimed at hedge funds, family offices and crypto-native asset managers.
At its October 2025 peak, USDe passed $14 billion in circulating supply and briefly became the third-largest stablecoin. Supply then contracted by around 60% as leveraged demand unwound and funding income weakened.
How USDe Works
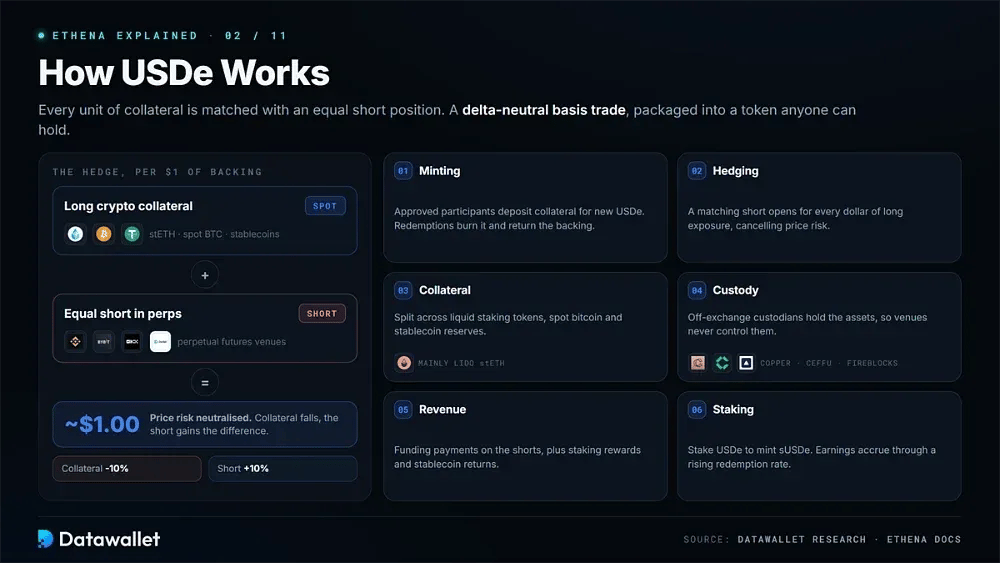
Every unit of crypto collateral backing USDe is matched with an equal short position intended to cancel the collateral's price movement. If the collateral loses value, the short gains, offsetting the decline and helping USDe remain near a dollar.
This is a delta-neutral basis trade, a strategy hedge funds and market makers have used for years, packaged into a token that anyone can hold.
The mechanics work as follows:
- Minting: Approved participants deposit collateral such as stablecoins or staked ETH in exchange for newly issued USDe. Redemptions burn the token and return the underlying collateral.
- Hedging: Ethena opens a matching short in perpetual futures for every dollar of long crypto exposure, using venues including Binance, Bybit, OKX and Deribit to neutralise price risk.
- Collateral: Backing is split across liquid staking tokens, mainly Lido stETH, spot bitcoin and stablecoin reserves. The staked portion also earns Ethereum rewards.
- Custody: Collateral remains with off-exchange custodians such as Copper, Ceffu and Fireblocks, preventing exchanges from taking direct control of the assets securing USDe.
- Revenue: The protocol earns funding payments on its short positions. Staking rewards and returns on stablecoin reserves held as backing provide additional income.
- Staking: USDe holders can stake their tokens to mint sUSDe. Protocol earnings accrue through a rising redemption rate rather than new tokens being deposited into the holder's wallet.
Ethena's documentation provides diagrams covering each step for anyone looking for the full mechanical picture.
How sUSDe Earns Yield
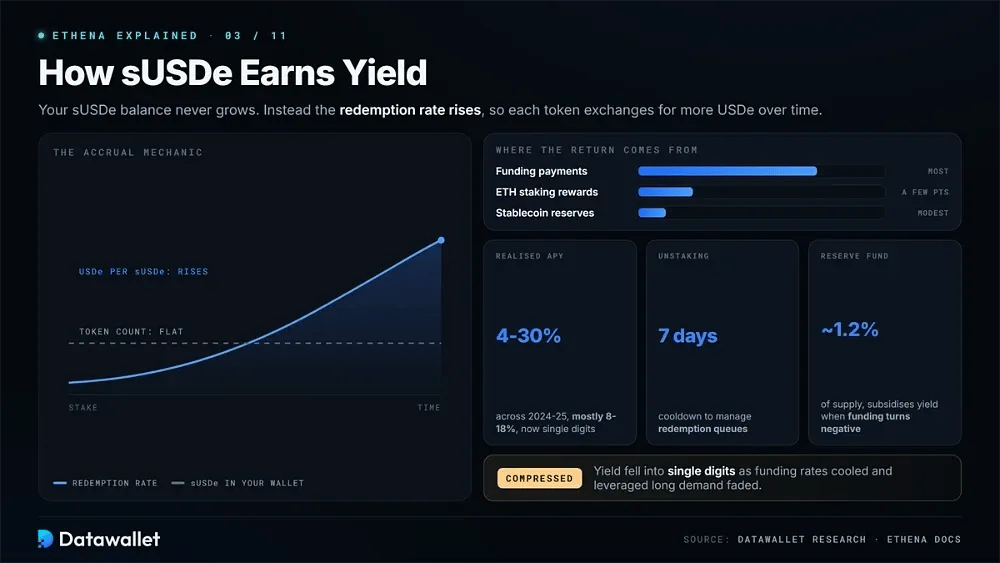
When USDe is staked, it converts to sUSDe and begins capturing protocol income. The number of sUSDe tokens in your balance stays the same. Instead, the redemption rate rises so that each sUSDe can be exchanged for more USDe over time.
Most of the return comes from funding payments collected on short perpetual positions. Ethereum staking rewards on the collateral add a few percentage points, while stablecoin reserves provide a modest fixed return.
The yield has compressed substantially. Realised APY ranged from roughly 4% to 30% across 2024 and 2025, with most periods between 8% and 18%. It later fell into single digits as funding rates cooled and demand for leveraged long positions faded.
Unstaking is subject to a seven-day cooldown, introduced to manage redemption queues during periods of stress. Ethena also keeps part of its revenue in a reserve fund near 1.2% of supply. That fund can subsidise the headline rate when funding becomes negative.
Why the Yield Fell
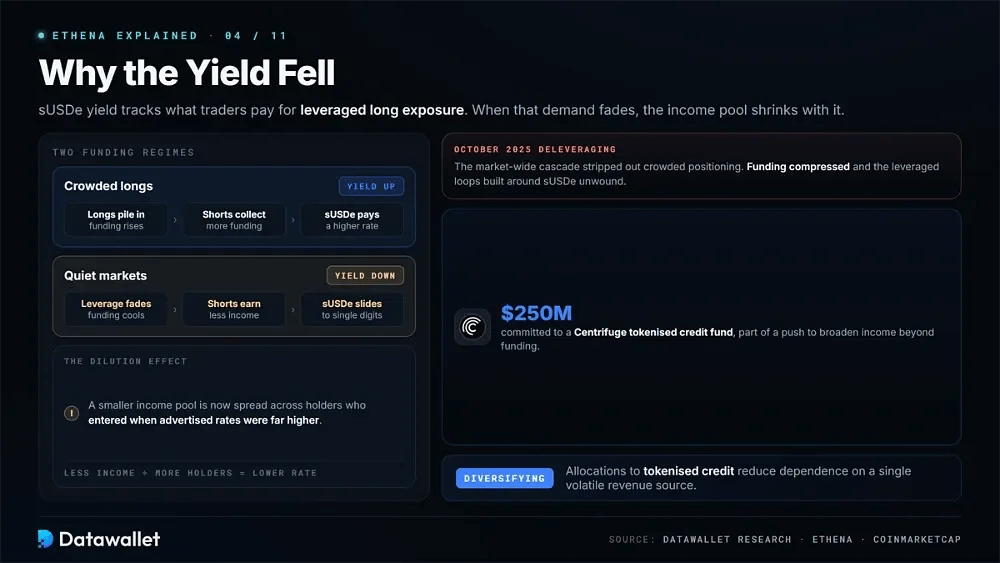
sUSDe yield largely follows what traders are willing to pay for leveraged long exposure. Crowded long positions drive funding rates higher, allowing Ethena's shorts to collect more and sUSDe to pay more. In quieter markets, the effect reverses.
The October 2025 deleveraging stripped out much of that positioning. Funding rates compressed and leveraged loops built around sUSDe unwound. At the same time, a smaller income pool was spread across holders who had entered when advertised rates were far higher.
Ethena has since broadened its sources of income. The protocol has been allocating capital to tokenised credit, including a $250 million commitment to a Centrifuge fund, reducing its dependence on a single volatile revenue source.
What is USDtb?
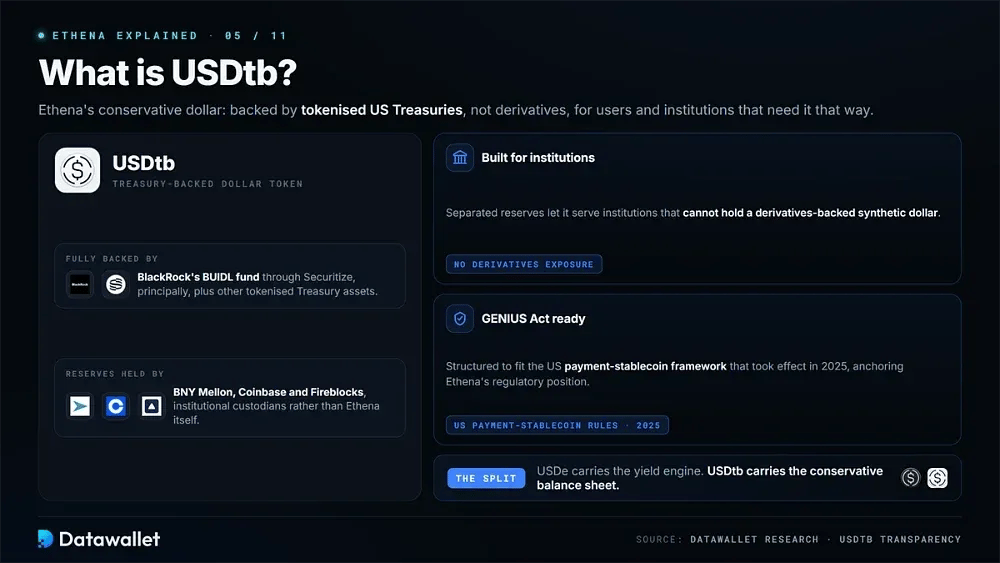
USDtb is Ethena's more conservative product for users who prefer a dollar token backed by Treasuries rather than derivatives. It is fully backed by tokenised US Treasury assets, principally BlackRock's BUIDL fund through Securitize.
Institutional custodians including BNY Mellon, Coinbase and Fireblocks hold the reserves rather than Ethena itself. This separation allows USDtb to serve institutions that cannot hold a derivatives-backed synthetic dollar.
The product also supports Ethena's regulatory positioning in the United States. USDtb is structured to fit the GENIUS Act framework for payment stablecoins that took effect in 2025.
How USDe Compares to Other Stablecoins
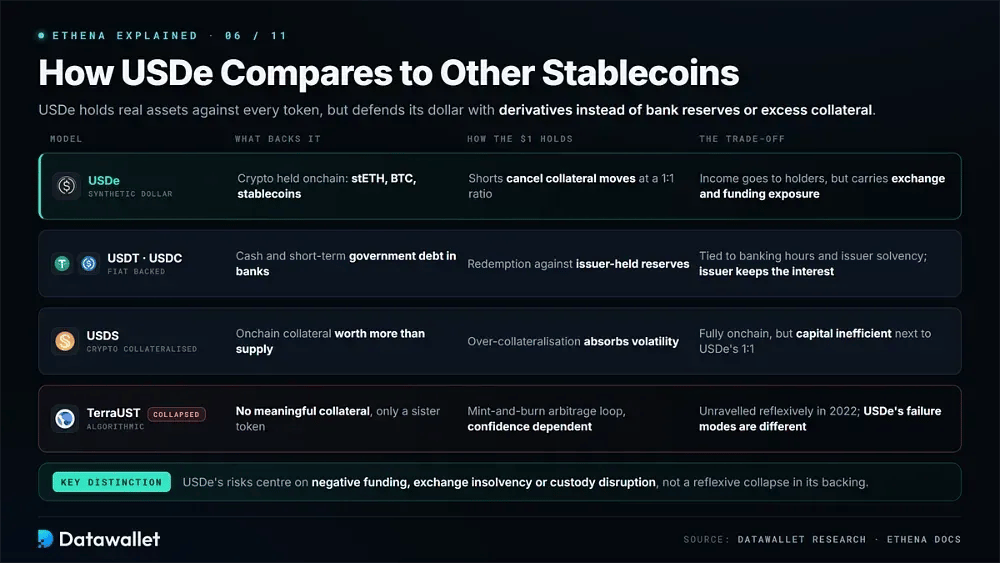
USDe belongs to a different category from the stablecoins most people already hold. Comparing their structures makes the trade-offs clearer.
USDe vs Fiat-Backed Stablecoins
USDT and USDC keep cash and short-term government debt in bank accounts, tying them to banking hours, jurisdictions and issuer solvency. USDe instead holds crypto onchain and offsets its price exposure through derivatives.
Fiat-backed issuers retain the interest generated by their reserves. Ethena passes its income to sUSDe holders, but USDe also carries exchange and funding exposure that USDC does not.
USDe vs Crypto-Collateralised Stablecoins
Sky's USDS, formerly MakerDAO's DAI, requires users to deposit more collateral than the value of the stablecoins they mint. USDe can operate at a one-to-one ratio because its hedge neutralises volatility rather than relying on an over-collateralisation buffer.
That structure improves capital efficiency. It also means Ethena depends on centralised exchanges to maintain its hedges, creating counterparty exposure that a fully onchain collateral vault avoids.
USDe vs Algorithmic Stablecoins
Comparing USDe with TerraUST misses a key difference in the designs. Terra had no meaningful collateral and relied on a mint-and-burn arbitrage loop with a sister token to defend its peg. That system unravelled when confidence collapsed.
USDe holds real assets against every token it issues. Its failure modes therefore centre on prolonged negative funding, exchange insolvency or custodial disruption rather than a reflexive collapse in its backing.
ENA Tokenomics
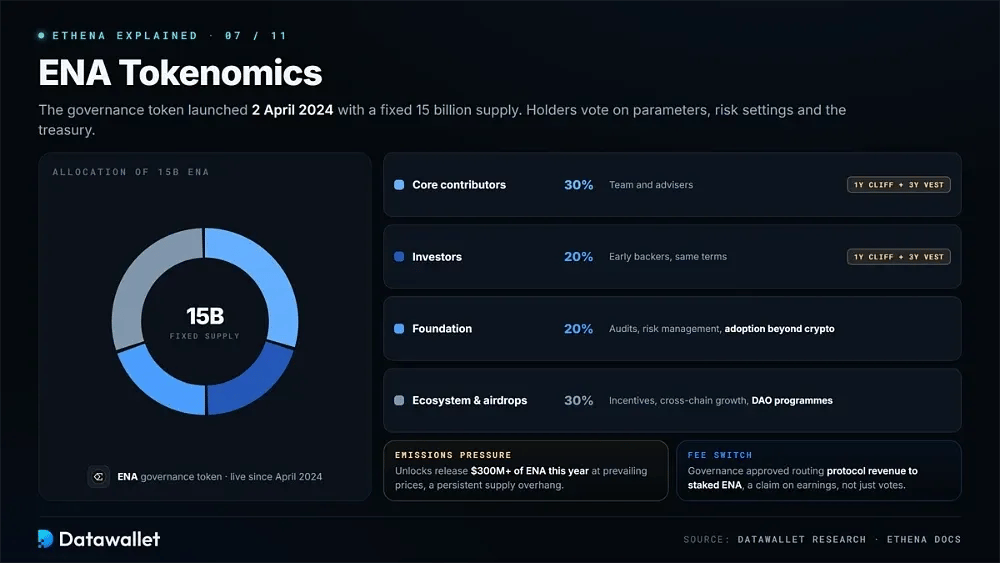
ENA is Ethena's governance token. It launched on 2 April 2024 with a fixed supply of 15 billion, and holders vote on protocol parameters, risk settings and treasury decisions.
The allocation splits four ways:
- Core contributors (30%): Reserved for the Ethena Labs team and advisers, with a one-year cliff followed by three years of linear vesting.
- Investors (20%): Allocated to early backers under identical cliff and vesting terms, matching their timeline with the protocol's development.
- Foundation (20%): Used for audits, risk management and efforts to expand USDe adoption beyond crypto-native markets.
- Ecosystem and airdrops (30%): Supports incentive campaigns, cross-chain expansion, exchange partnerships and later DAO-controlled programmes.
- Emissions pressure: Scheduled unlocks are set to release more than $300 million of ENA across the current year at prevailing prices, creating a persistent supply overhang for the token.
- Fee switch: Governance approved sending protocol revenue to staked ENA, giving the token a mechanism designed to provide a claim on earnings rather than votes alone.
ENA Price and the Fee Switch
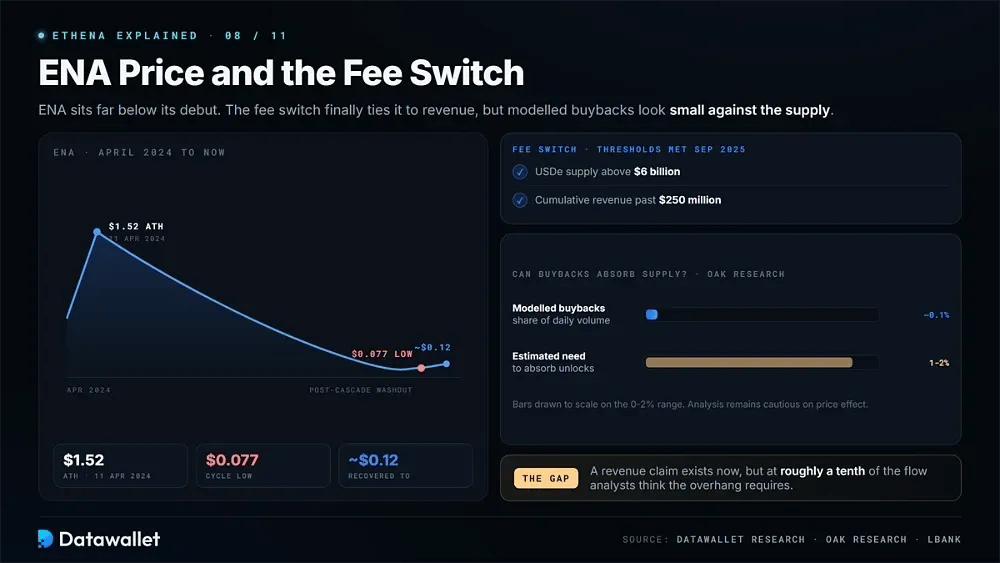
ENA is far below its debut levels. The token reached an all-time high of $1.52 on 11 April 2024. Two years later, during the post-cascade washout, it bottomed near $0.077 before recovering to around $0.12.
The fee switch addresses the token's previous lack of a direct connection to revenue. Activation required USDe supply to exceed $6 billion and cumulative protocol revenue to pass $250 million, thresholds Ethena said it had reached in September 2025.
Independent analysis remains cautious about the potential price effect. OAK Research modelled the buybacks at about 0.1% of daily ENA volume, well below the 1% to 2% it estimated would be needed to absorb supply.
Converge and Institutional Expansion
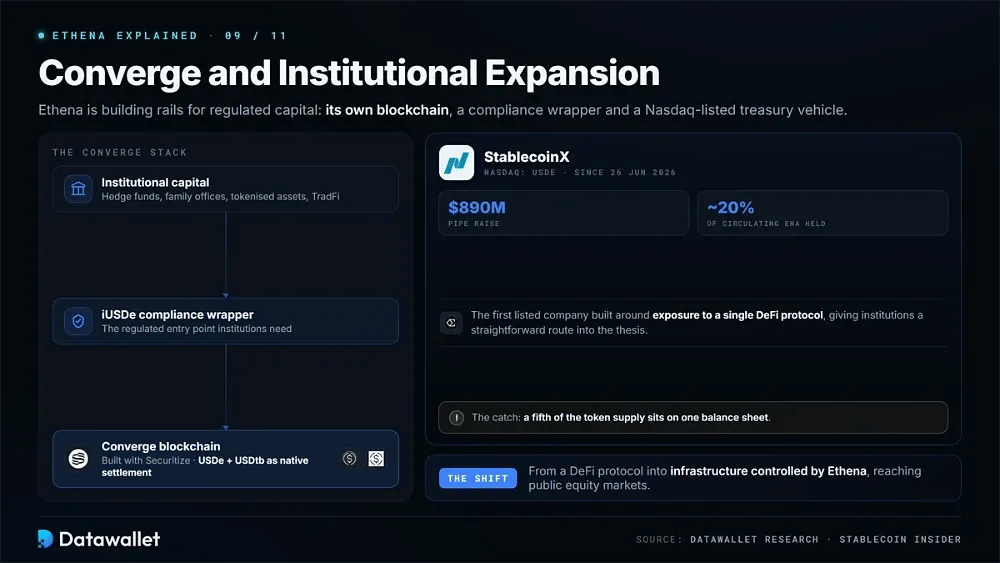
Converge extends Ethena from a protocol into infrastructure. Built with tokenisation firm Securitize, the blockchain is intended to bring regulated institutional capital onto rails controlled by Ethena.
USDe and USDtb serve as the chain's native settlement assets. That places tokenised assets and traditional finance capital alongside Ethena's existing DeFi presence, while iUSDe provides the compliance wrapper institutions need to participate.
Ethena also has a separate connection to public equity markets. StablecoinX began trading on Nasdaq under the ticker USDE on 26 June 2026 after an $890 million PIPE raise. Its treasury holds roughly 20% of circulating ENA.
That concentration is central to the debate around the vehicle. A listed company built around exposure to a single DeFi protocol gives institutions a straightforward route into the thesis, but it also places a fifth of the token supply on one balance sheet.
Ethena Risks
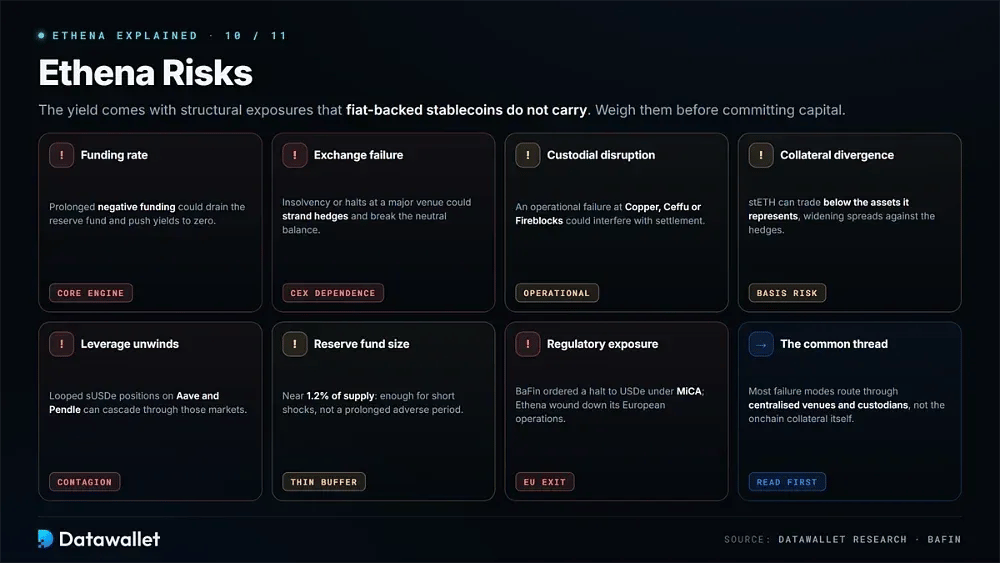
Ethena's yield introduces structural exposures that ordinary fiat-backed stablecoins do not carry. Consider them before committing capital:
- Funding rate risk: Returns depend on positive funding from short perpetual positions. A prolonged period of negative funding could drain the reserve fund and push sUSDe yields towards zero.
- Exchange failure: Ethena's hedges operate on centralised venues. Insolvency or trading suspensions at a major exchange could strand positions and disrupt the delta-neutral balance.
- Custodial disruption: Off-exchange custodians hold the collateral. An operational failure involving Copper, Ceffu or Fireblocks could interfere with settlement even though exchanges do not control the assets.
- Collateral divergence: Liquid staking tokens such as stETH can trade below the value of the assets they represent, increasing spreads against the derivatives used for hedging.
- Leverage unwinds: Large sUSDe positions are used in looped lending strategies on platforms such as Aave and Pendle. A rapid unwind can cascade through those markets.
- Reserve fund size: The buffer for negative funding remains near 1.2% of supply, enough to absorb shorter shocks rather than a prolonged adverse period.
- Regulatory exposure: Germany's BaFin ordered Ethena GmbH to stop offering USDe under MiCA rules, leading the protocol to wind down its European operations.
What the October 2025 Depeg Showed
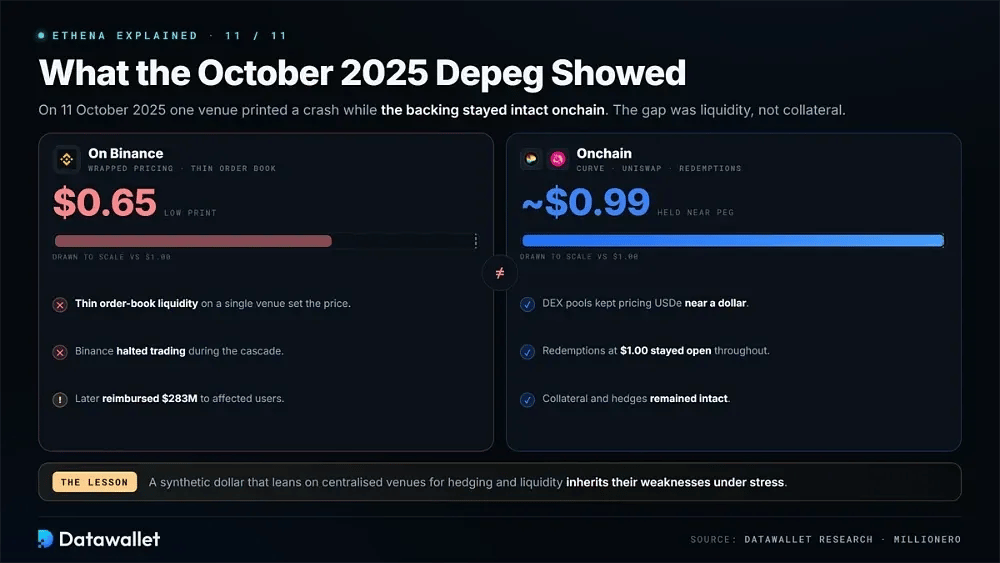
During a violent market-wide selloff on 11 October 2025, USDe printed as low as $0.65 on Binance. Onchain markets told a different story: USDe remained near $0.99 on Curve and Uniswap and could still be redeemed at a dollar.
The price gap resulted from thin order-book liquidity and wrapped-token pricing on a single venue rather than a failure of USDe's backing. Binance halted trading and later reimbursed $283 million to affected users.
Even with intact onchain collateral, a synthetic dollar that depends on centralised venues for hedging and secondary liquidity remains exposed to their weaknesses during periods of stress.
Final Thoughts
Ethena presents a trade-off rather than a free lunch. In exchange for a dollar token that pays holders instead of its issuer, users accept derivatives exposure, exchange counterparty risk and variable income.
That bargain was tested over the past year. Supply fell around 60% from its peak, yields moved into single digits and a European regulator pushed the protocol out of that market. Through those events, the mechanism held.
The next phase depends on whether Converge, USDtb and tokenised credit can generate income that is less tied to the broader DeFi leverage cycle. Anyone holding sUSDe should continue tracking funding rates and compare its returns with other stablecoin yields.
