Compare Real World Asset Projects
1. Ondo
Ondo Finance ranks first for the breadth of its live products. It has become the largest issuer across both tokenized US Treasuries and tokenized stocks, while OUSG and USDY together hold roughly $2 billion. Those products give global investors continuous exposure to short-term government debt yields.
Ondo Stocks became the larger 2026 story. The platform surpassed $1 billion in value locked within eight months of launch and now lists more than 450 tokenized US equities and ETFs across Ethereum, Solana, and BNB Chain. That scale gives Ondo the majority of the tokenized equity market.
Other milestones include the Ondo Network execution layer, FINRA clearance for its Oasis Pro broker-dealer, and tokenized portfolios based on BlackRock model strategies. Our full Ondo Finance breakdown explains how the individual products work.
Pros
- Largest provider of both tokenized Treasuries and tokenized stocks.
- Tokenized equities track total return, including dividend payments.
- SEC closed its investigation into Ondo with no charges.
Cons
- Most products remain unavailable to US retail investors.
- Governance uncertainty followed a dispute over company control.
- Primary minting requires accreditation and high minimum amounts.
2. Robinhood
Robinhood Chain takes second place because it combines a public RWA blockchain with a large existing consumer distribution network. Its Arbitrum-based Ethereum Layer 2 moved to public mainnet on July 1, 2026. New Stock Tokens are available to eligible Robinhood Wallet users in more than 120 countries and support 24/7 onchain trading, subject to local restrictions.
Robinhood had already launched more than 200 US stock and ETF tokens for European customers in June 2025, then expanded its Classic Stock Token catalog to roughly 2,000 by the fourth quarter. The newer Robinhood Chain Stock Tokens are ERC-20 tokenized debt securities that provide economic exposure to underlying shares or ETFs without granting legal or beneficial rights in those securities.
Adoption on the new chain has moved quickly. By September 4, Robinhood Chain supported more than 190 Stock Tokens and $149.4 million in tokenized value. Current DeFiLlama data puts active RWA AUM near $295 million and DeFi TVL above $1 billion. Uniswap, Alchemy, BitGo, and Chainlink are among the infrastructure and liquidity integrations around the network.
Pros
- Public RWA chain connects tokenized stocks with Robinhood distribution.
- Stock Tokens use standard ERC-20 infrastructure and onchain pricing.
- Mainnet supports trading, lending, borrowing, and self-custody workflows.
Cons
- Stock Tokens are unavailable to US persons and restricted elsewhere.
- Holders do not receive ownership rights in the underlying securities.
- Public mainnet has operated only since July 2026.
3. Canton
Canton Network ranks third for institutional adoption rather than retail distribution. Digital Asset and a group of major market participants announced Canton in May 2023. Its Global Synchronizer and native Canton Coin, or CC, went live on July 1, 2024, creating a privacy-enabled interoperability layer for regulated financial applications.
The network reports more than $6 trillion in tokenized real-world assets, over $300 billion in daily US Treasury repo trades, and more than 700 connected firms. Canton allows regulated applications to synchronize transactions while keeping sensitive data private, a structure designed for capital markets where public-by-default ledgers can be difficult to use.
Institutional workflows moved beyond pilots in 2026. DTCC used Canton for production alongside its private Besu network in transactions involving tokenized securities, while Tradeweb completed a real-time US Treasury trade on Canton using tokenized cash. In August, Tradeweb, Virtu Financial, and M1X Global also completed a fully onchain repo using a sovereign digital bond as collateral.
Pros
- Privacy and interoperability are built for regulated financial markets.
- DTCC and Tradeweb use Canton in live tokenization workflows.
- Network activity includes large-scale institutional repo and tokenized assets.
Cons
- Applications are written in Daml rather than standard EVM smart contracts.
- Much of the network activity centers on institutional market infrastructure.
- Canton Coin has a shorter public-market history than established crypto assets.
4. Chainlink
Chainlink sits at the connective layer of tokenization, supplying price data, reserve verification, and cross-chain messaging for RWA issuers. CCIP has become the standard route for moving tokenized assets between public chains and private blockchain environments.
Institutional integration deepened during 2026. The DTCC integrated Chainlink into its Collateral AppChain for 24/7 collateral management. A separate corporate-actions initiative with Swift, Euroclear, and UBS advanced into production-grade testing across two dozen major financial firms.
Chainlink also anchors Project Pangea, a cross-border settlement initiative involving more than 50 banks, and continues supplying data to the Canton Network used by institutional ledgers. For many allocators, LINK serves as broad exposure to the tokenization infrastructure layer rather than a single asset category.
Pros
- Proof of Reserve verifies collateral behind tokenized assets automatically.
- CCIP connects institutional ledgers with dozens of public chains.
- Adopted by DTCC, Swift, and Euroclear for live workflows.
Cons
- Token value capture from enterprise deals develops relatively slowly.
- Running node infrastructure demands significant LINK staking commitments.
- Complex product suite creates a steep learning curve for developers.
5. Pendle
For yield strategies, Pendle separates yield-bearing tokens into principal and yield components, allowing users to build fixed-rate or leveraged positions around tokenized assets. The protocol has become the default venue for pricing stablecoin and RWA yields across decentralized finance.
Its markets now extend far beyond crypto-native collateral. Tokenized treasury products and yield-bearing stablecoins now dominate deposits, while Boros introduced margin trading on funding rates. That addition broadens Pendle's revenue base beyond the maturity-driven markets that powered its earlier growth.
Around 40% of circulating PENDLE is locked in the vePENDLE system, tying holders to protocol fees and governance incentives. Our guide to how Pendle Finance works covers the principal-token and yield-token mechanics in more detail.
Pros
- Lock fixed yields on tokenized treasury and stablecoin pools.
- Boros expands revenue through funding rate trading with margin.
- vePENDLE locking directs protocol fees toward long-term holders.
Cons
- Yield tokens decay to zero value at market maturity.
- TVL swings sharply when incentive programs end or rotate.
- Leveraged looping strategies amplify losses when spreads turn negative.
6. Ethena
Institutional momentum is the main reason Ethena ranks here. USDe, its synthetic dollar, grew into one of the largest stablecoins in circulation with supply near $6 billion. Yield is generated through delta-neutral derivatives positions and reserves held partly in tokenized instruments.
USDtb provides a more direct RWA connection because it is backed primarily by BlackRock's BUIDL fund. In June 2026, BlackRock integrated USDe into its Aladdin risk platform and launched a $100 million BUIDL liquidity facility with Securitize.
Janus Henderson made a strategic ENA investment, Coinbase Ventures took its first stake, and Kraken now custodies USDe reserves. For more context on the structure and trade-offs, see our explainer on what Ethena is and our guide to the safest stablecoins.
Pros
- USDtb reserves sit primarily in BlackRock's tokenized BUIDL fund.
- Staked USDe distributes yield without traditional banking intermediaries.
- Deep integrations across Aave, Pendle, and major exchanges.
Cons
- Yields compress or turn negative when funding rates flip.
- Synthetic design carries derivatives and exchange counterparty exposure.
- Peg stability depends on hedges performing during market stress.
7. Maple
Maple Finance runs the largest onchain lending business and ranks here for institutional credit exposure. By September 2026, it reported $4.8 billion in assets under management and $7.4 billion in year-to-date loan originations. Its rebuilt risk framework now requires every loan to be overcollateralized.
Retail users reach that credit engine through syrupUSDC and syrupUSDT, liquid tokens that pass institutional lending yields to depositors. The newer syrupUSDG product expanded onto Robinhood Chain, giving Maple distribution within a rapidly growing consumer-focused crypto ecosystem.
The SYRUP token replaced legacy MPL and receives 25% of protocol revenue through buybacks and the strategic fund. Our roundup of the best stablecoin interest rates covers comparable ways to earn yield on dollar-denominated balances.
Pros
- Every loan is overcollateralized with transparent onchain accounting.
- Syrup tokens make institutional credit yields accessible to anyone.
- Protocol revenue funds recurring SYRUP buybacks under governance rules.
Cons
- Credit decisions still rely on off-chain underwriting teams.
- Withdrawals can queue during periods of heavy loan utilization.
- Past credit losses show borrower defaults remain a real risk.
What are Real World Assets (RWA)?
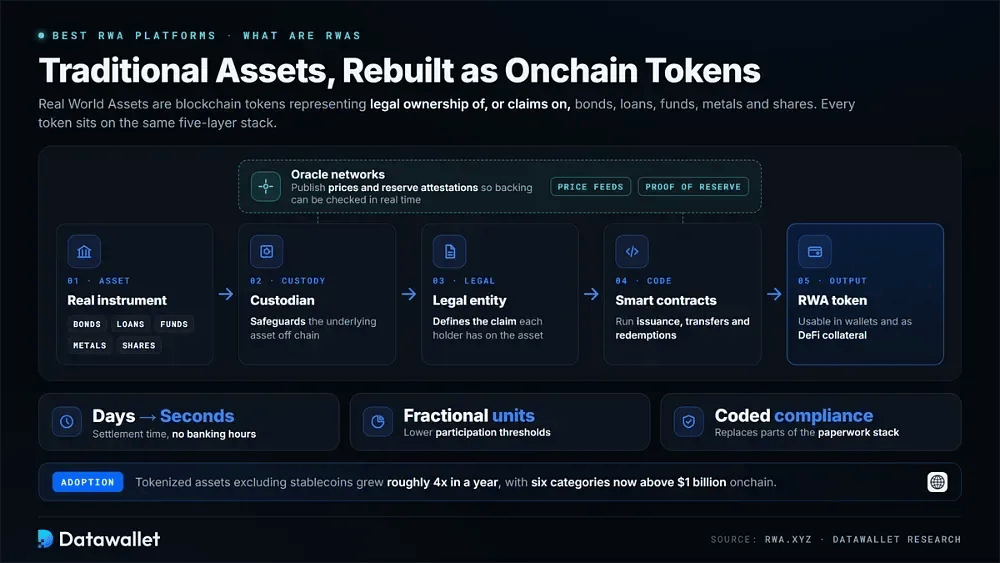
Real World Assets are blockchain tokens representing legal ownership of, or claims on, instruments outside crypto. Bonds, loans, funds, metals, and shares all fit within the category. Putting those claims onchain can open markets that were previously constrained by brokers, banking hours, or geographic access.
A typical RWA structure has a custodian safeguarding the underlying asset and a legal entity defining the holder's claim. Smart contracts manage issuance, transfers, and redemptions. Oracle networks can then publish prices and reserve attestations, allowing backing to be checked in real time.
The commercial case centers on efficiency. Settlement that once took days can complete in seconds, fractional units lower participation thresholds, and programmable compliance can replace parts of the manual paperwork stack. A regulated fund share can therefore function as a DeFi collateral asset without becoming a separate instrument.
Adoption data reflects that shift. Tracking from rwa.xyz shows tokenized assets excluding stablecoins multiplying roughly fourfold over the past year, with six separate categories now above $1 billion onchain. Our tokenization statistics page follows those figures as the market changes.
Types of Real World Asset Projects
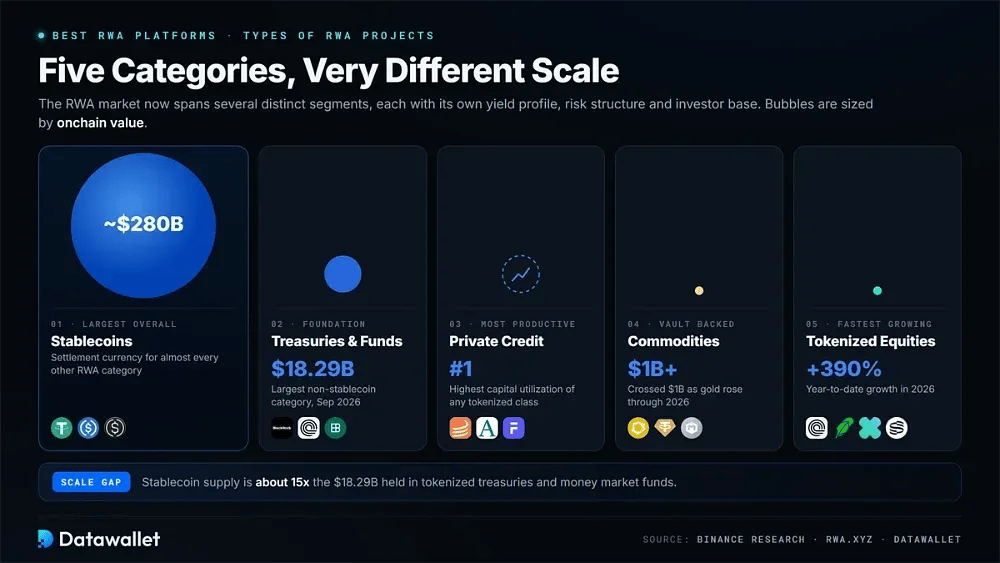
The RWA market now spans several distinct categories rather than one dominant product. Each segment comes with a different yield profile, risk structure, and typical investor base.
1. Tokenized Treasuries & Funds
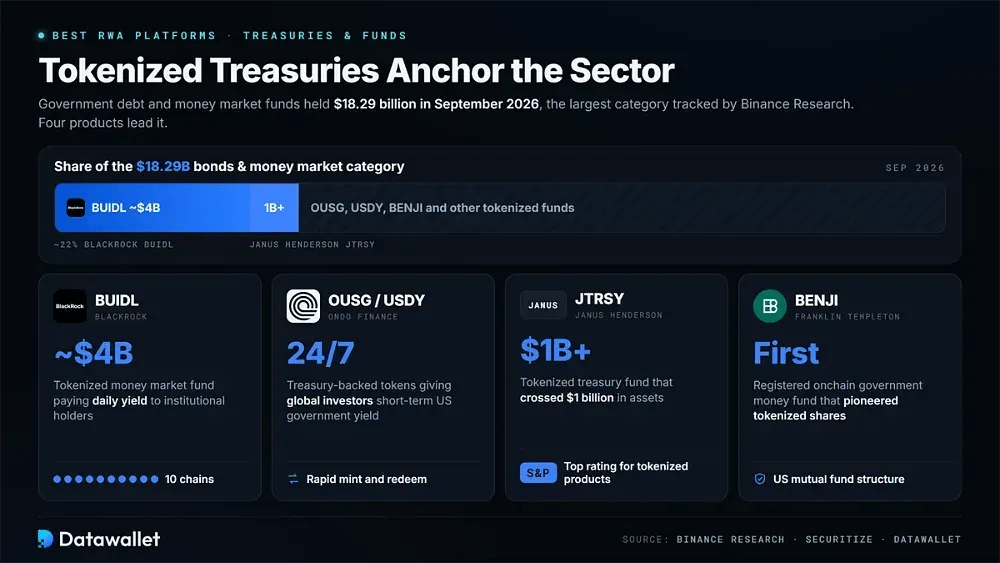
Government debt and money market funds remain the sector's foundation. Bonds and money market products held around $18.29 billion in September 2026, making them the largest category tracked by Binance Research.
Leading products in this category include:
- BlackRock BUIDL: A tokenized money market fund holding roughly $4 billion, distributing daily yield to institutional holders across ten blockchain networks.
- Ondo OUSG/USDY: Treasury-backed tokens giving global investors continuous access to short-term US government yields with rapid minting and redemption.
- Janus Henderson JTRSY: A tokenized treasury fund that crossed $1 billion and carries the highest S&P rating given to tokenized products.
- Franklin Templeton BENJI: A registered onchain government money fund that pioneered tokenized shares within a US-regulated mutual fund structure.
2. Stablecoins
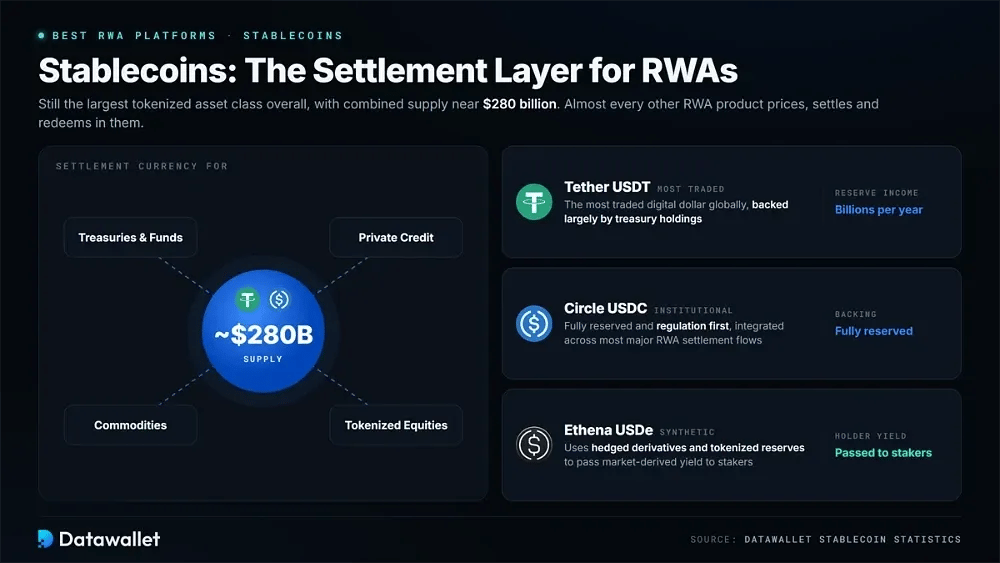
Stablecoins are still the largest tokenized asset class overall. Combined supply sits near $280 billion, and these assets serve as the settlement currency for almost every other RWA product category.
Top issuers shaping this segment are:
- Tether USDT: The most traded digital dollar globally, backed largely by treasury holdings and generating billions in annual reserve income.
- Circle USDC: A fully reserved, regulation-first stablecoin preferred by institutions and integrated across most major RWA settlement flows worldwide.
- Ethena USDe: A synthetic dollar using hedged derivatives and tokenized reserves to pass market-derived yield directly through to stakers.
Our stablecoin statistics dashboard breaks down supply, chains, and issuer market share in more detail.
3. Private Credit
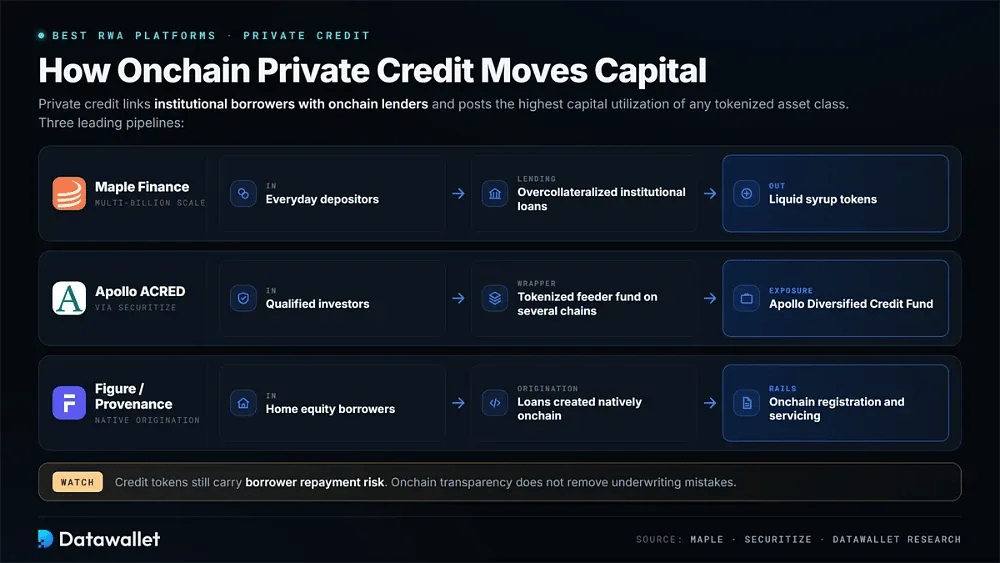
Private credit has become one of the most productive RWA segments, linking institutional borrowers with onchain lenders and posting the highest capital utilization rates of any tokenized asset class.
Recommended platforms for credit exposure include:
- Maple Finance: Runs overcollateralized institutional lending at multi-billion scale, packaging loan yields into liquid syrup tokens for everyday depositors.
- Apollo ACRED: A tokenized feeder fund giving qualified investors onchain access to Apollo Diversified Credit Fund across several blockchain networks.
- Figure/Provenance: Originates home equity loans natively onchain, processing billions in consumer credit through blockchain-based registration and servicing rails.
4. Commodities
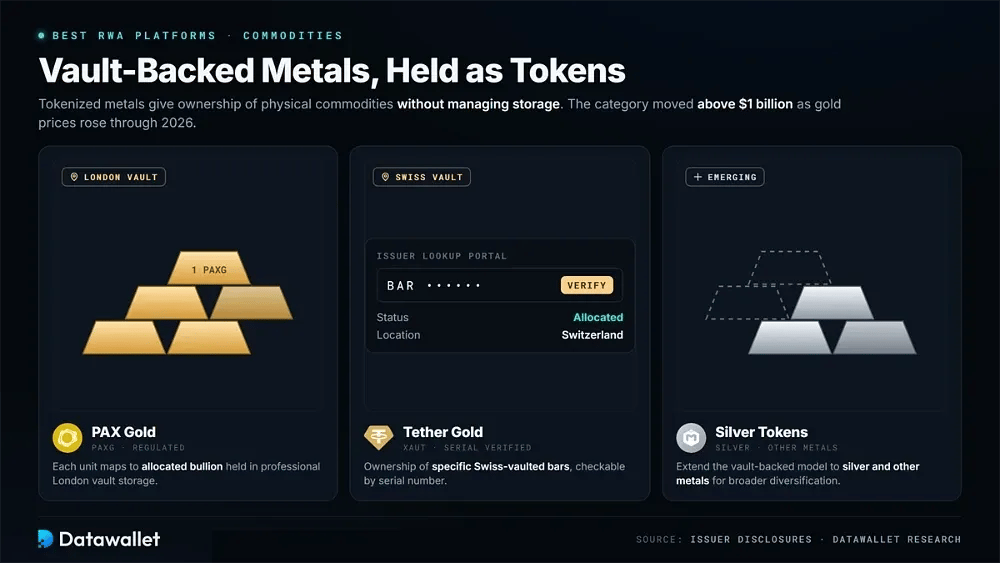
Tokenized metals provide vault-backed ownership of physical commodities without requiring investors to manage storage. The category moved above $1 billion as gold prices rose through 2026.
Major players in tokenized commodities are:
- PAX Gold: A regulated gold token where each unit maps to allocated bullion held in professional London vault storage.
- Tether Gold: Represents ownership of specific Swiss-vaulted gold bars, verifiable by serial number through the issuer's lookup portal.
- Silver tokens: Emerging products extending the vault-backed model to silver and other metals for broader commodity diversification.
Compare the leading options in our guides to the best gold-backed cryptocurrencies and the best tokenized silver assets.
5. Tokenized Equities
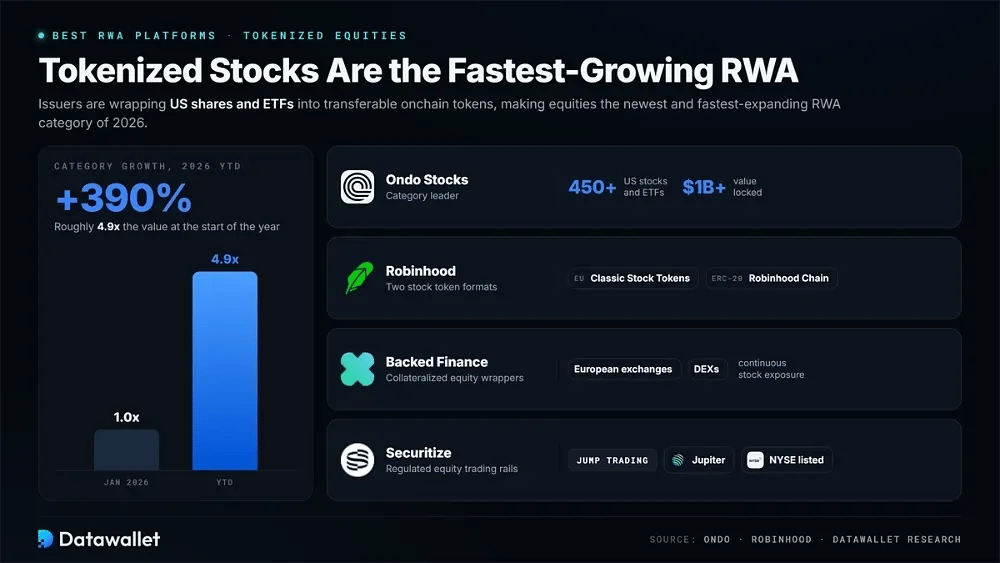
Stocks are the newest and fastest-expanding RWA category, growing roughly 390% year-to-date in 2026 as issuers wrapped US shares and ETFs into transferable onchain tokens.
Key names driving equity tokenization include:
- Ondo Stocks: The category leader with over 450 tokenized US stocks and ETFs and more than $1 billion in value locked.
- Robinhood Stock Tokens: Offers tokenized US stock exposure through Classic Stock Tokens in Europe and composable ERC-20 Stock Tokens on Robinhood Chain.
- Backed Finance: Issues collateralized equity wrappers used across European venues and decentralized exchanges for continuous stock exposure.
- Securitize: Building regulated tokenized equity trading infrastructure with Jump Trading and Jupiter following its own public listing.
See our comparison of the best tokenized stock trading exchanges for where to trade these products.
What RWA Projects is BlackRock Investing in?
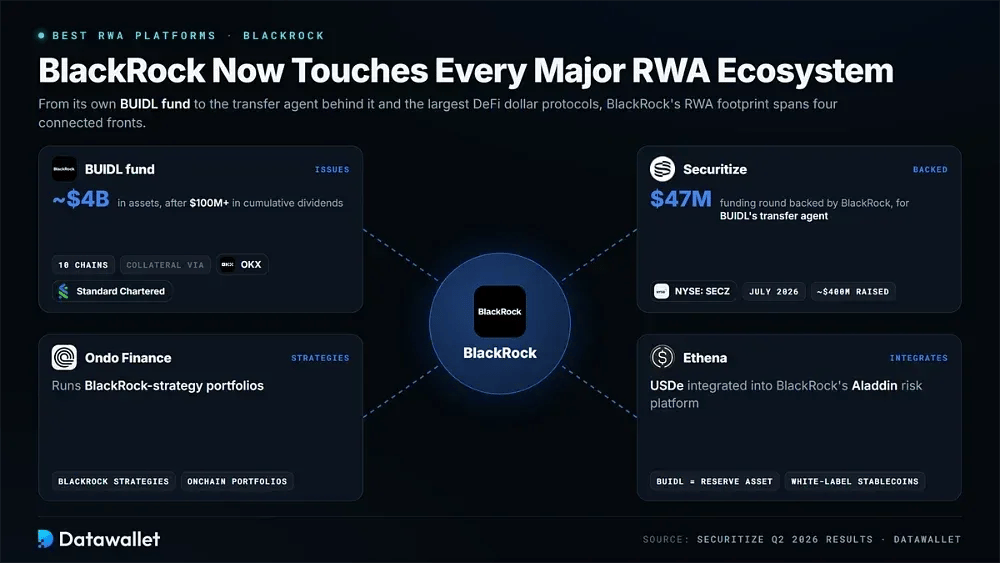
BlackRock's BUIDL fund has grown to roughly $4 billion in assets, according to Securitize's Q2 2026 results, after passing $100 million in cumulative dividends. The fund settles across ten blockchains and is accepted as trading collateral through frameworks involving OKX and Standard Chartered.
Securitize, the transfer agent BlackRock backed through a $47 million funding round, went public on the NYSE in July 2026 under the ticker SECZ and raised around $400 million. That listing gave public-market investors their first direct equity exposure to tokenization infrastructure.
BlackRock also expanded its DeFi exposure by integrating Ethena's USDe into the Aladdin risk platform and making BUIDL the reserve asset for Ethena's white-label stablecoins. Together with Ondo's BlackRock-strategy portfolios, those relationships mean the firm now touches nearly every major RWA ecosystem.
How to Invest in RWA Projects
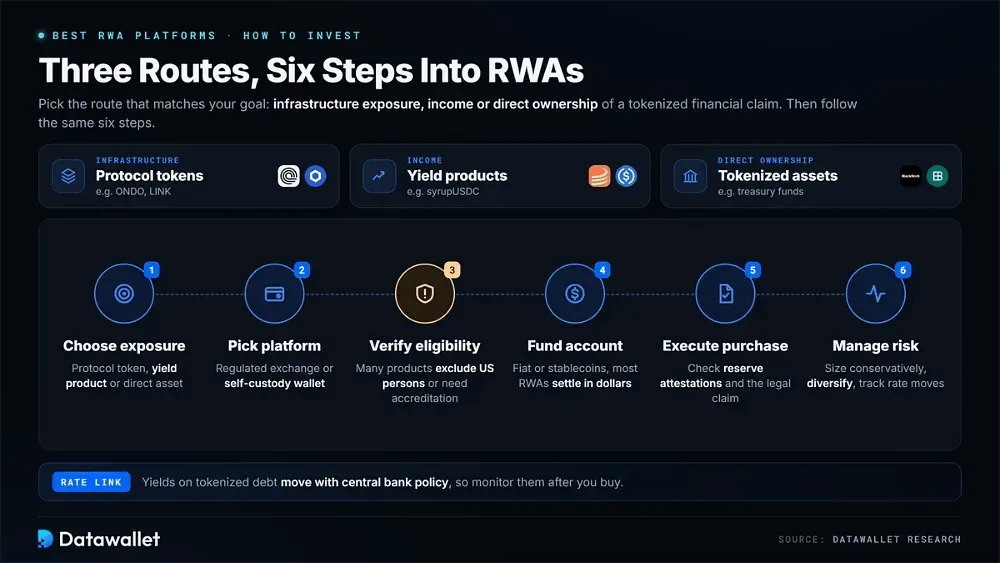
Exposure to the RWA sector generally comes through one of three routes: protocol tokens, yield products, or the tokenized assets themselves. The right route depends on whether the goal is infrastructure exposure, income, or direct ownership of a tokenized financial claim.
Follow these steps to build your RWA position:
- Choose exposure: Decide between protocol tokens like ONDO or LINK, yield products like syrupUSDC, and direct tokenized assets such as treasury funds.
- Pick platform: Open an account with a regulated exchange listing RWA tokens, or connect a self-custody wallet for onchain products.
- Verify eligibility: Check regional restrictions carefully, since many tokenized treasury and equity products exclude US persons or require accreditation checks.
- Fund account: Deposit fiat or stablecoins, keeping settlement currency in mind because most RWA products price and redeem in dollars.
- Execute purchase: Buy your chosen tokens, confirm reserve attestations where available, and review the legal claim each token actually represents.
- Manage risk: Size positions conservatively, diversify across categories, and monitor yields, since rates on tokenized debt move with central bank policy.
Risks and Challenges for RWAs
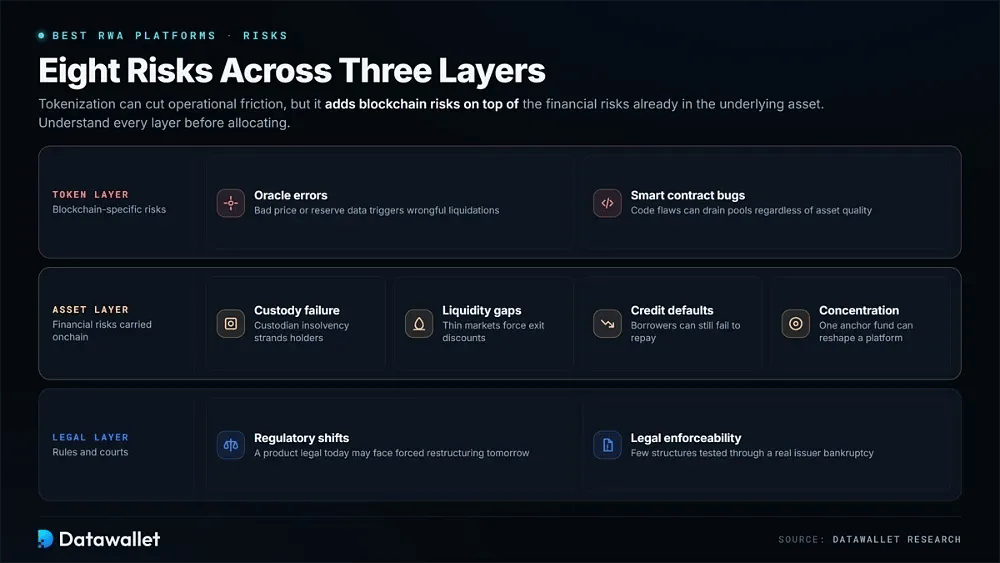
Tokenization can reduce operational friction, but it adds blockchain-specific risks to the financial risks already present in the underlying asset. Investors need to understand both layers before allocating capital.
Essential risk factors to consider include:
- Regulatory shifts: Securities rules differ across jurisdictions and continue evolving, meaning a product legal today could face restrictions or forced restructuring tomorrow.
- Custody failure: Tokens are only as sound as the custodian holding the underlying asset, and insolvency there can strand token holders entirely.
- Oracle errors: Faulty price or reserve data can trigger wrongful liquidations or hide undercollateralization until losses have already become unavoidable for participants.
- Liquidity gaps: Many tokenized instruments trade thinly on secondary markets, so exiting sizable positions during stress may require accepting significant discounts.
- Smart contract bugs: Code vulnerabilities can drain pools regardless of asset quality, which is why audits from reputable smart contract auditing firms matter.
- Credit defaults: Private credit tokens carry borrower repayment risk, and past cycles show onchain transparency does not eliminate old-fashioned underwriting mistakes.
- Legal enforceability: Token holder claims must survive real-world courts, and few structures have been stress-tested through an actual issuer bankruptcy yet.
- Concentration exposure: Several platforms depend on one or two anchor funds or allocators, so a single redemption decision can reshape their entire economics.
RWA Market Size Forecast
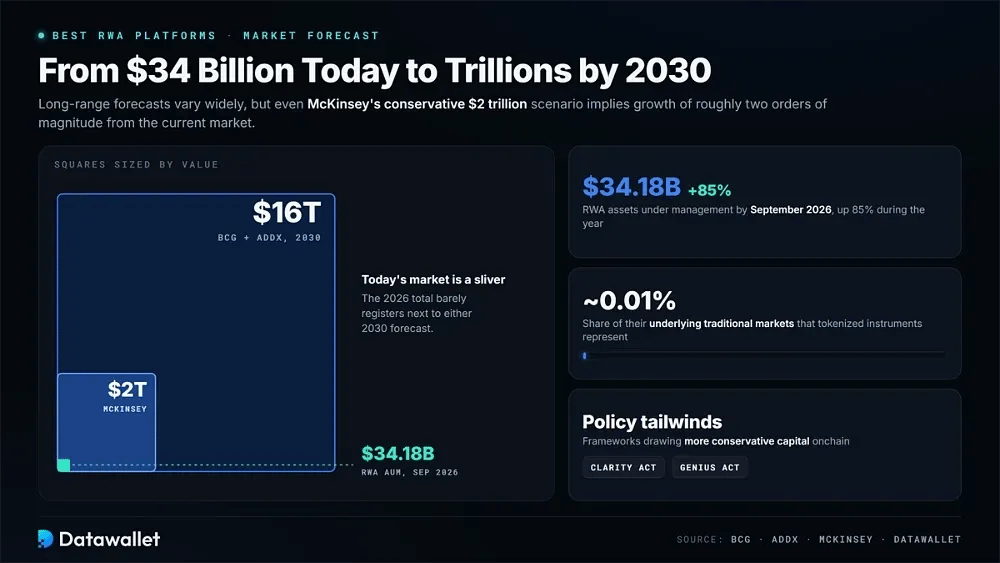
Long-range forecasts vary widely. Boston Consulting Group and ADDX estimate tokenized assets could reach $16 trillion by 2030, while McKinsey's more conservative modeling is around $2 trillion. Even the lower scenario would imply growth of roughly two orders of magnitude from the current market.
Near-term data gives those forecasts context. RWA assets under management rose 85% during 2026 to $34.18 billion by September, yet tokenized instruments still represent only about 0.01% of their underlying traditional markets. Regulatory frameworks such as the CLARITY Act and the GENIUS Act continue to draw more conservative capital onchain.
Final Thoughts
Tokenization has moved from pilot programs into production finance. DTCC, BlackRock, Janus Henderson, Robinhood, and other large financial firms now operate or support live onchain products. The question is no longer whether RWAs can scale, but which infrastructure will capture the flow across issuance, distribution, settlement, data, and liquidity.
The seven projects in this ranking each hold a defensible position in that stack. Ondo focuses on tokenized securities, Robinhood on global consumer distribution, Canton on institutional settlement, Chainlink on data and interoperability, Pendle on yield markets, Ethena on synthetic dollars, and Maple on credit. Those functions need dedicated infrastructure, and diversifying across the layers remains preferable to relying on a single project.
Investors should still separate platform adoption from token value capture. Revenue mechanics, regional access rules, legal structure, and regulatory developments deserve close attention because those details will distinguish durable RWA investments from short-lived narrative trades.