
Compare the Best DeFi Projects in 2026
Project | Rating | Category | Token | Standout Metric | Best For |
|---|---|---|---|---|---|
 Hyperliquid | 4.9/5 | Perp DEX + L1 | HYPE | ~58% of onchain perp OI (Q3) | Onchain perpetuals |
 Aave | 4.8/5 | Lending | AAVE | ~$15.5B TVL; #1 lender | Blue-chip lending |
 Lido | 4.7/5 | Liquid staking | LDO / stETH | ~21% of all staked ETH | Liquid ETH staking |
 Uniswap | 4.7/5 | Spot DEX | UNI | $4.5T+ lifetime volume | Token swaps |
 Morpho | 4.6/5 | Modular lending | MORPHO | ~$11B TVL; #2 lender | Curated vault lending |
 Sky Protocol | 4.5/5 | Stablecoin + savings | SKY / USDS | ~$10B USDS supply | Savings-rate stablecoins |
 Ethena | 4.4/5 | Synthetic dollar | ENA / USDe | ~$4.95B USDe; 101% backed | Funding-rate dollar yield |
1. Hyperliquid (HYPE)
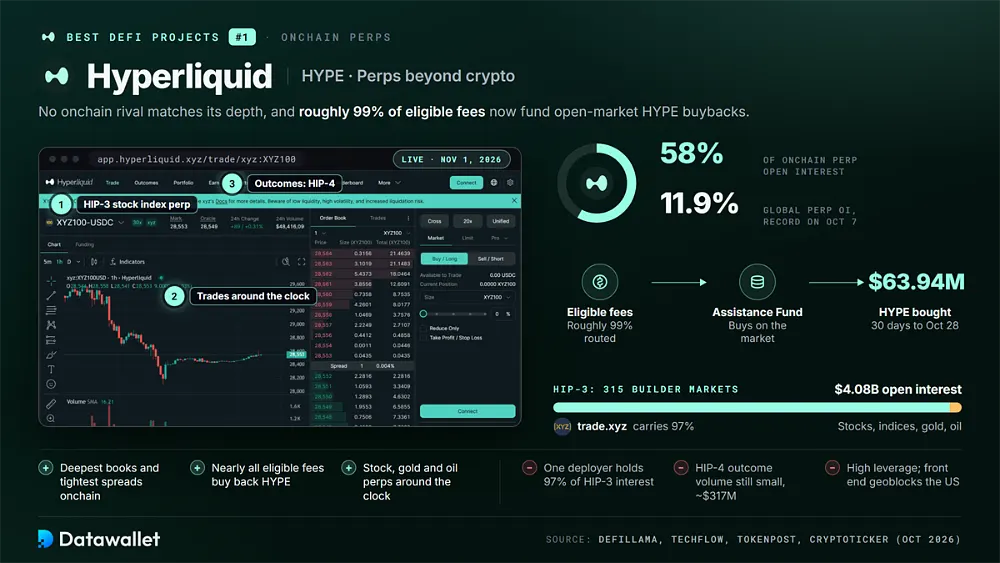
Hyperliquid keeps first place because no onchain venue matches its depth. A TechFlow Q3 report credits it with 58% of onchain perpetual open interest, and TokenPost logged a record 11.9% share of global perp open interest, centralized exchanges included, on October 7. Our Hyperliquid statistics page tracks the live numbers.
Growth now comes from beyond crypto. HIP-3 lets builders who stake 500,000 HYPE run their own markets, and by October 28 there were 315 such markets on stocks, indices, gold and oil, holding $4.08 billion in open interest. HIP-4 adds prediction-style outcome contracts on the same margin account.
Value accrual is unusually direct: roughly 99% of eligible fees fund Assistance Fund buybacks of HYPE, worth $63.94 million in the thirty days to October 28 on DefiLlama. Leverage and liquidations remain the core risks, and the front end blocks US users. Compare rivals in our decentralized perpetuals exchanges guide.
Pros
- Holds the majority of onchain perpetual open interest, giving traders the deepest books and tightest spreads outside centralized exchanges.
- Routes nearly all eligible fees into open-market HYPE buybacks, now supplemented by yield on its USDC reserves.
- Offers tokenized stock, index, gold and oil perpetuals around the clock through permissionless HIP-3 markets.
Cons
- One deployer, trade.xyz, carries 97% of HIP-3 open interest, concentrating the new markets' liquidity in a single operator.
- HIP-4 outcome markets remain small, with about $317 million in lifetime volume against far larger prediction-market rivals.
- High leverage and a front end that geoblocks the US and several regions limit who can use it safely.
2. Aave (AAVE)
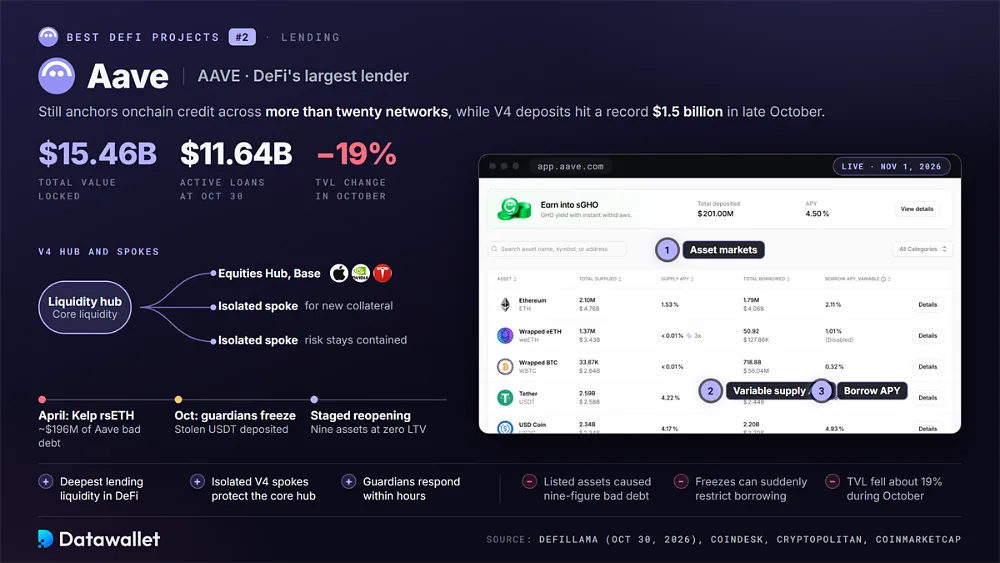
Aave remains DeFi's largest lender, holding $15.46 billion in total value locked and $11.64 billion in active loans on DefiLlama at October 30. That is about a third of its October 2025 peak, yet Aave still anchors onchain credit, with suppliers earning variable interest across more than twenty networks.
Aave V4 is where the momentum sits. Its hub-and-spoke design launched in March, deposits passed a record $1.5 billion in late October, and an Equities Hub on Base accepts tokenized Apple, Nvidia and Tesla shares as collateral for non-US users. Revenue-funded AAVE buybacks tie the token to protocol earnings.
Stress tests have been public. April's Kelp DAO rsETH exploit left roughly $196 million of Aave bad debt. In October, guardians froze markets after the Binance hacker deposited stolen USDT, then reopened them with nine assets, including USDT and USDC, at zero loan-to-value.
Pros
- Offers the deepest lending liquidity in DeFi, so large deposits and withdrawals move rates less than on smaller markets.
- V4 adds isolated spokes for new collateral types, including tokenized equities, without endangering the core liquidity hub.
- Guardians and risk stewards respond within hours, as the October freeze and staged reopening showed.
Cons
- Listed-asset failures created nine-figure bad debt in 2026, even though Aave's own contracts were never exploited.
- Emergency freezes and zero-LTV changes can suddenly restrict borrowing against assets users already hold.
- TVL fell about 19% during October, reflecting withdrawals and lower prices across the wider market.
3. Lido (LDO / stETH)
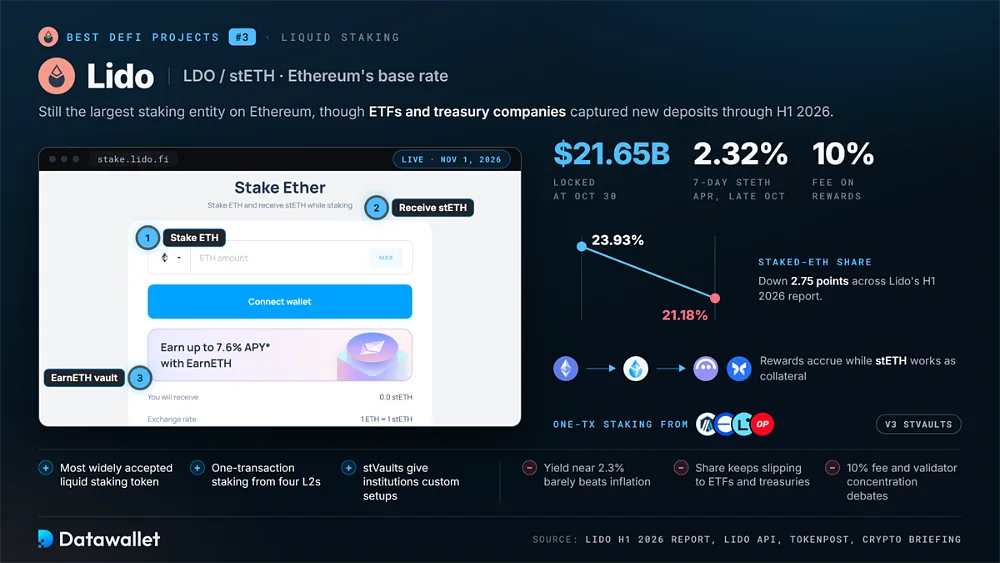
Lido is still the largest staking entity on Ethereum, with about $21.65 billion locked on October 30. Deposit ETH and you receive stETH, a liquid token that accrues validator rewards while serving as collateral on Aave, Morpho and dozens of other venues. Our Lido explainer covers the mechanics.
Its share is shrinking, though. Lido's own H1 2026 report shows staked-ETH market share falling from 23.93% to 21.18% as treasury companies and ETFs captured new deposits. Lido responded with V3 stVault partners like Stakely and one-transaction staking from Arbitrum, Base, Linea and Optimism.
Yield is modest: Lido's API showed a seven-day stETH APR of about 2.32% in late October, after a 10% fee on rewards. Treat it as Ethereum's base rate rather than a trade, and compare alternatives in our liquid staking platforms guide and Ethereum staking statistics.
Pros
- stETH is the most widely accepted liquid staking token, usable as collateral across nearly every major Ethereum lending market.
- Users on four major layer 2 networks can now stake in one transaction and receive wstETH instantly.
- stVaults let institutions build custom validator, custody and fee setups while still tapping stETH liquidity.
Cons
- Staking yield near 2.3% barely beats inflation and trails tokenized Treasury funds and many stablecoin savings rates.
- Market share keeps slipping to ETFs and treasury companies, weakening LDO's growth story.
- A 10% fee on rewards and ongoing validator-concentration debates remain recurring criticisms.
4. Uniswap (UNI)
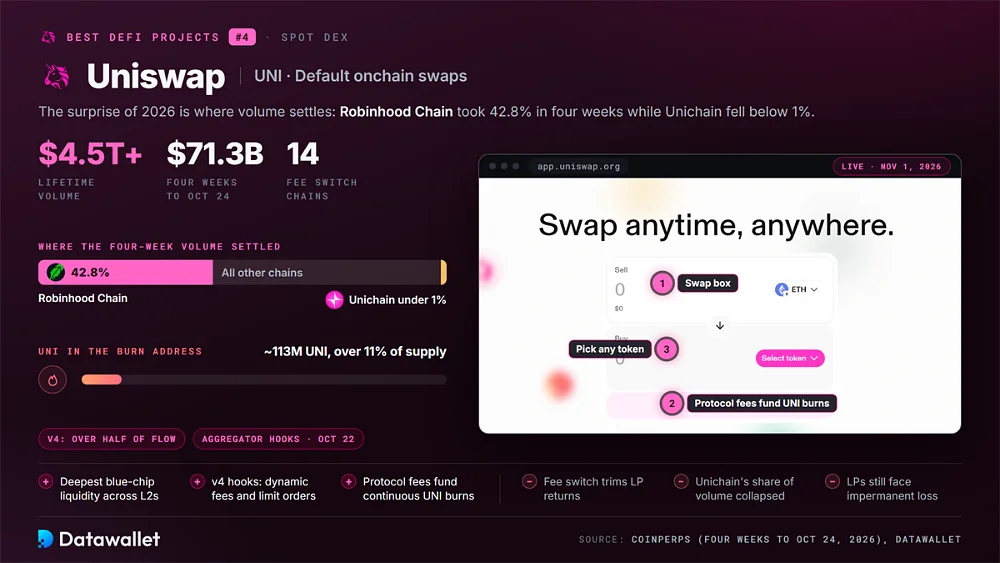
Uniswap remains the default venue for onchain swaps, with more than $4.5 trillion in lifetime volume by October 2026. Defillama data shows about $71.3 billion traded in the four weeks to October 24, and v4 pools now carry over half that flow thanks to hooks and custom fee logic.
The surprise of 2026 is where volume settles. Robinhood Chain handled 42.8% of Uniswap volume over that window, while Unichain fell below 1%. On October 22, Uniswap launched aggregator hooks that route through rival liquidity and send the resulting external routing fees to UNI burns.
The UNIfication fee switch, live since late December 2025, burned 100 million UNI from the treasury and now runs on 14 chains. Roughly 113 million UNI, over 11% of supply, sits in the burn address. Compare competing venues in our decentralized exchanges guide.
Pros
- Offers the deepest blue-chip liquidity across Ethereum and its layer 2 networks, keeping slippage low on large swaps.
- v4 hooks support dynamic fees, limit orders and aggregator routing, making pools far more programmable.
- Protocol fees fund continuous UNI burns, directly linking token supply to how much the exchange is used.
Cons
- The fee switch trims liquidity provider returns, which can push some LPs toward competing venues.
- Unichain's share of volume has collapsed, weakening one of the original UNIfication growth arguments.
- Liquidity providers still face impermanent loss on volatile pairs, which can outweigh fees collected.
5. Morpho (MORPHO)
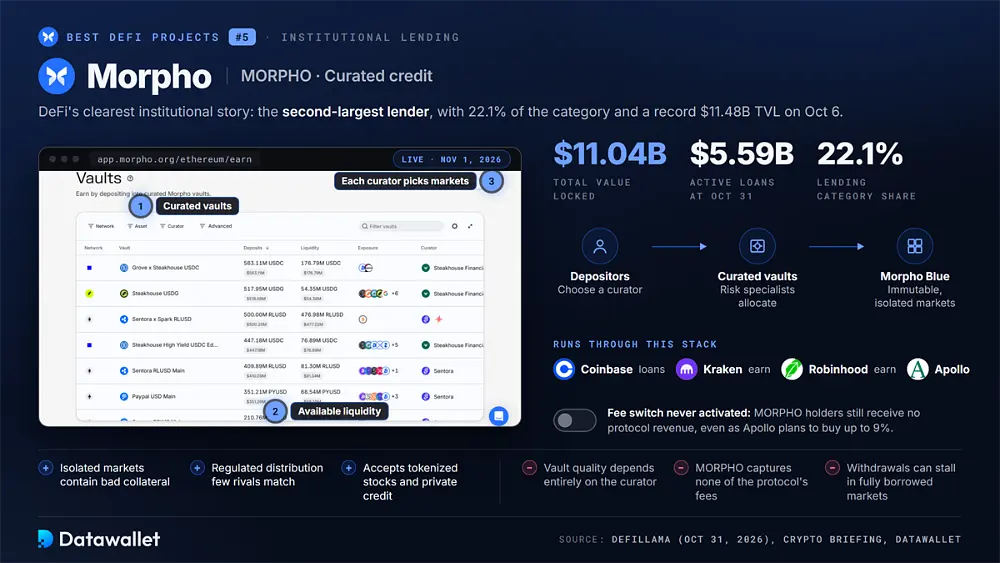
Morpho is DeFi's clearest institutional story. DefiLlama shows $11.04 billion in total value locked and $5.59 billion in active loans at October 31, making it the second-largest lender with 22.1% of the category. Its TVL also set a record of $11.48 billion on October 6.
The design explains the demand. Morpho Blue offers immutable isolated markets, while curated vaults let risk specialists allocate deposits. Coinbase loans, Kraken and Robinhood earn products, Apollo's plan to buy up to 9% of MORPHO, and September's tokenized-stock lending on Base all run through that stack.
Choosing Morpho means choosing a curator, much like picking a fund manager, so read each vault's collateral list and limits. The token remains the weak point: governance has never activated its fee switch, so MORPHO holders still receive no protocol revenue. Compare options in our crypto lending platforms guide.
Pros
- Isolated markets stop one bad collateral asset from contaminating every other market on the protocol.
- Powers lending inside Coinbase, Kraken and Robinhood, bringing regulated distribution few DeFi rivals can match.
- Accepts tokenized stocks and private credit, positioning it for the next wave of real-world collateral.
Cons
- Vault quality depends entirely on the curator, and loose parameters can still produce losses for depositors.
- MORPHO captures none of the protocol's fees until governance activates the dormant fee switch.
- Withdrawals can be delayed when the markets a vault uses are fully borrowed.
6. Sky Protocol (SKY / USDS)
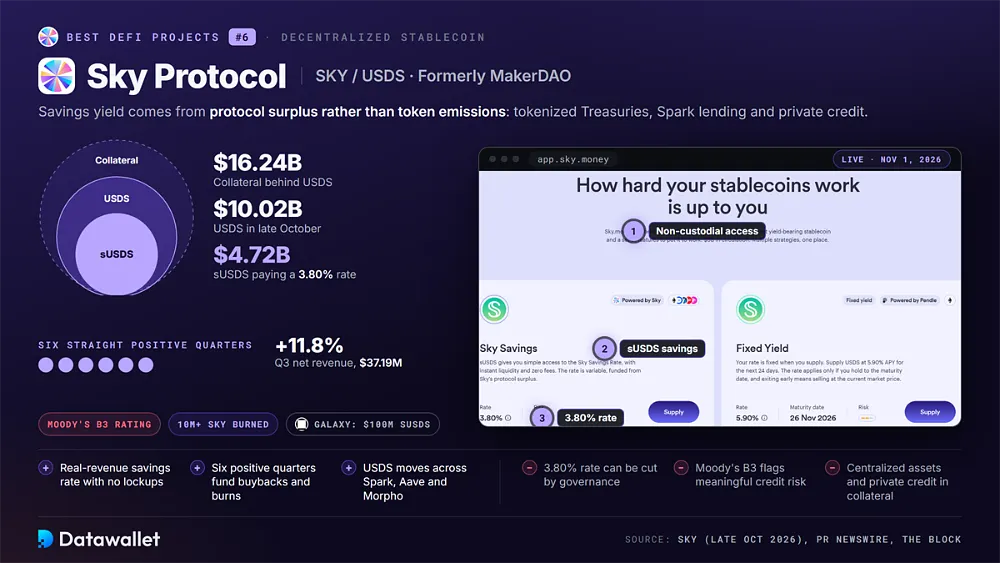
Sky, formerly MakerDAO, joins our list as DeFi's largest decentralized stablecoin issuer. Its homepage showed roughly $10.02 billion of USDS backed by $16.24 billion in collateral in late October, while sUSDS, the savings version, held about $4.72 billion on October 21 and paid a 3.80% Sky Savings Rate.
The yield comes from protocol surplus rather than token emissions. Sky deploys reserves into tokenized Treasuries, DeFi lending through Spark and private credit, and Q3 net revenue rose 11.8% to $37.19 million, its sixth straight positive quarter. Galaxy added $100 million of sUSDS to its balance sheet.
SKY holders benefit through buybacks, staking rewards and, since September, programmatic burns totaling more than 10 million SKY. Moody's assigned Sky a B3 issuer rating in October, a reminder that governance and collateral concentration remain real risks for depositors.
Pros
- sUSDS pays a governance-set savings rate funded by real revenue, with no lockups or withdrawal fees.
- Six consecutive quarters of positive net revenue fund buybacks, staking rewards and programmatic SKY burns.
- USDS integrates across Spark, Aave and Morpho, so savers can move between protocols easily.
Cons
- The 3.80% savings rate trails many lending yields and can be cut by governance at any time.
- Moody's B3 rating flags meaningful credit risk compared with fiat-backed stablecoins like USDC.
- Collateral includes centralized assets and private credit, adding counterparty exposure behind the dollar peg.
7. Ethena (ENA / USDe)
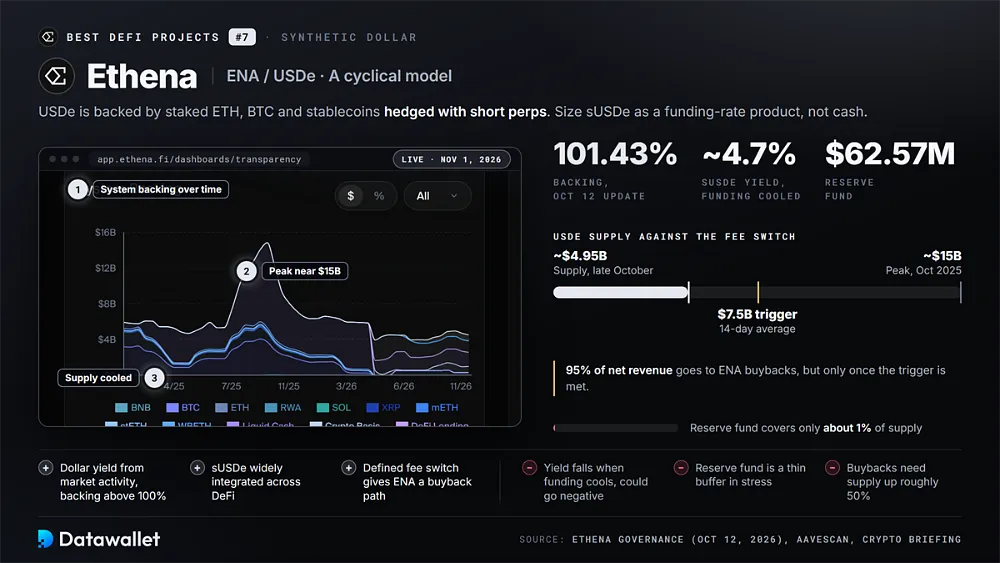
Ethena issues USDe, a synthetic dollar backed by staked ETH, BTC and stablecoins hedged with short perpetual futures. Its October 12 governance update reported 101.43% backing and a $62.57 million reserve fund against 4.76 billion USDe, with circulating supply near $4.95 billion by late October.
The model is cyclical. USDe peaked near $15 billion in October 2025, and sUSDe now earns about 4.7% because funding rates have cooled, roughly level with tokenized Treasuries. Ethena is broadening demand through Ethena Pay, a native X Layer deployment with Aave, and plans for equity perpetual hedges.
For ENA, governance approved a fee switch that routes 95% of net revenue into buybacks, but only once USDe's 14-day average supply tops $7.5 billion. Size sUSDe as a funding-rate product, not a cash equivalent. Our Ethena explainer covers the hedge in detail.
Pros
- Generates dollar yield from market activity rather than bank deposits, with backing published regularly above 100%.
- sUSDe is widely integrated as collateral and in fixed-yield markets across major DeFi protocols.
- A defined fee switch gives ENA a clear path to revenue-funded buybacks if supply recovers.
Cons
- Yield falls sharply when funding rates cool and could turn negative in prolonged bearish markets.
- The reserve fund covers only about 1% of supply, a thin buffer during stress.
- ENA buybacks remain dormant until USDe supply grows roughly 50% from current levels.
Biggest DeFi Trends Shaping Late 2026
Three shifts explain why this year's list looks different from last year's. Real-world assets keep moving onchain, protocols increasingly pay holders through buybacks, and security incidents now originate as often at bridges and exchanges as inside smart contracts.
Tokenized Stocks and Real-World Assets Go Onchain
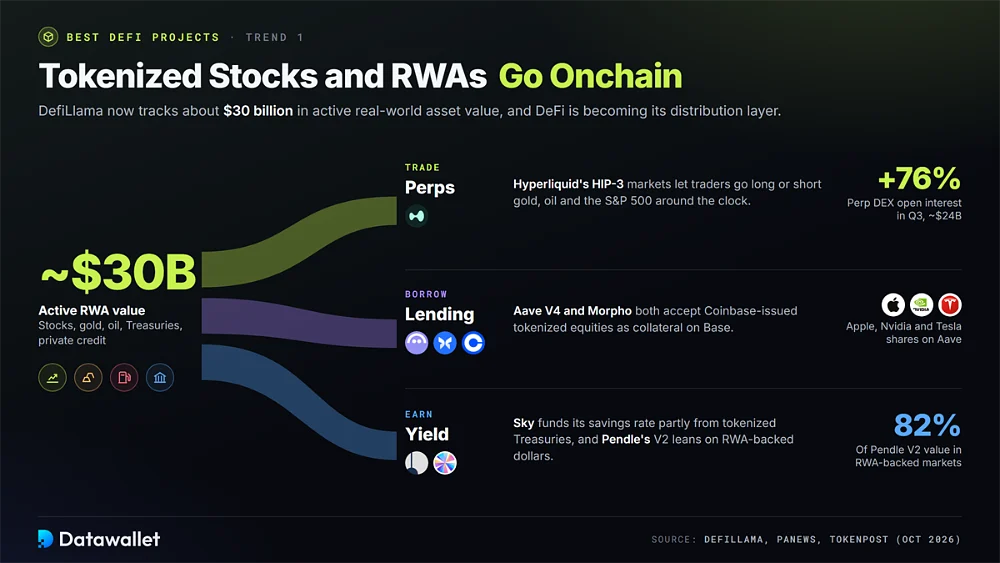
DefiLlama now tracks about $30 billion in active real-world asset value, and DeFi is becoming its distribution layer. Hyperliquid's HIP-3 markets let traders go long or short gold, oil and the S&P 500 around the clock, while perp DEX open interest rose 76% in Q3 to roughly $24 billion.
Lending followed. Aave V4 and Morpho both accept Coinbase-issued tokenized equities on Base, Pendle reports that 82% of its V2 value sits in RWA-backed dollar markets, and Sky funds its savings rate partly from tokenized Treasuries. For background, see our guides to RWA projects and tokenized stock exchanges.
Value Accrual and Security Lessons From 2026
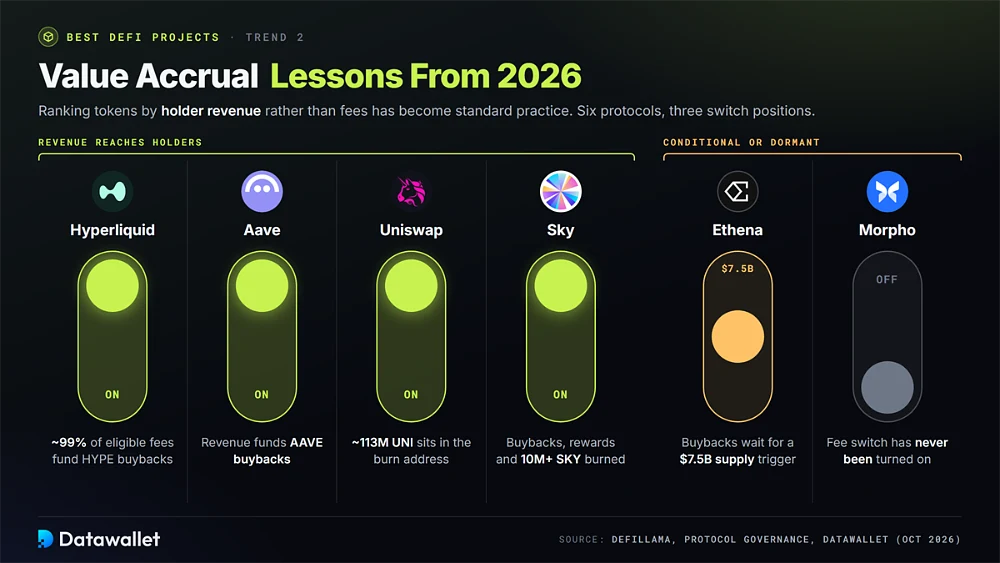
Two forces now separate durable protocols from fragile ones: whether revenue reaches token holders, and how well systems survive attacks that start elsewhere. October 2026 tested both at once, with clear lessons for users.
The developments worth tracking before you deposit anywhere this quarter:
- Buybacks: Hyperliquid, Aave, Uniswap and Sky all route revenue into token purchases or burns, so ranking tokens by holder revenue rather than fees has become standard practice.
- Conditional switches: Ethena and Morpho show the opposite pattern: Ethena's buybacks wait for a $7.5 billion supply trigger, while Morpho's fee switch has never been turned on.
- Exchange risk: TRM Labs attributes the October 29 Binance theft of roughly $6.36 billion to North Korea's TraderTraitor, the largest crypto hack on record, about four times Bybit's 2025 loss.
- Contagion: The attacker deposited stolen USDT on Aave and borrowed WETH before guardians froze markets, proving that DeFi protocols can be dragged into centralized incidents within hours.
- Bridge exploits: April's $292 million Kelp DAO rsETH exploit came through a cross-chain bridge, not a lending contract, yet lenders absorbed the bad debt, so collateral quality matters most.
- AI-found bugs: The so-called Black October wave of AI-discovered software flaws, including PHP2Shell, showed vulnerabilities now surface faster, which raises the bar for audits and rapid patching.
Honorable Mentions Worth Watching
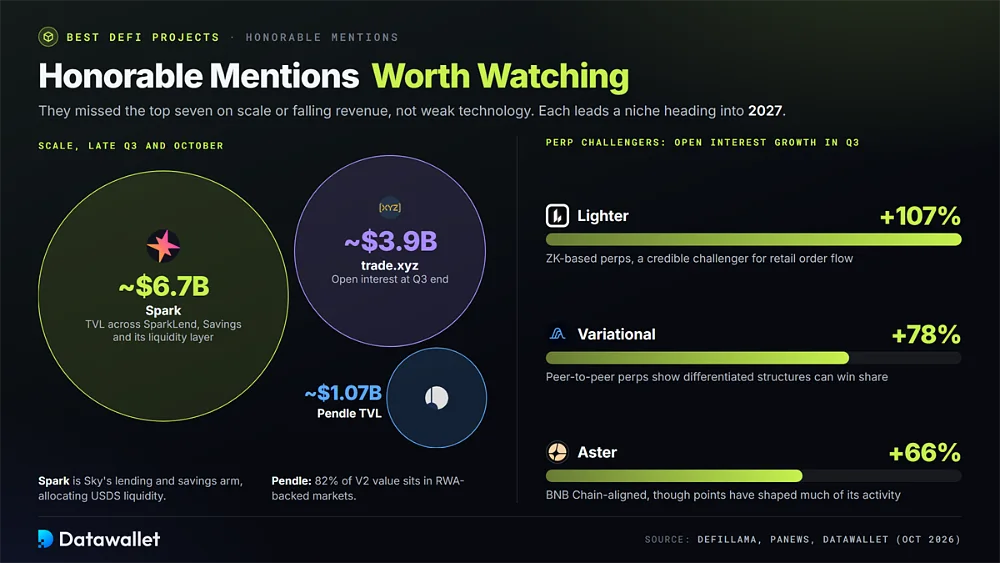
Several protocols narrowly missed our top seven, usually because of smaller scale or falling revenue rather than weak technology. Each still leads a niche and could climb back into contention during 2027.
The projects we are monitoring most closely heading into 2027:
- Pendle: The leading yield-tokenization venue dropped from our list after TVL fell to about $1.07 billion, though 82% of its V2 value now sits in RWA-backed markets.
- Spark: Sky's lending and savings arm held roughly $6.7 billion in TVL in late October, allocating USDS liquidity across SparkLend, Spark Savings and its cross-chain liquidity layer.
- trade.xyz: The dominant HIP-3 deployer on Hyperliquid ended the third quarter with about $3.9 billion of open interest across tokenized stock, index and commodity perpetuals. See our trade.xyz explainer.
- Lighter: This ZK-based perpetuals exchange more than doubled its open interest during Q3, growing about 107%, and remains one of Hyperliquid's most credible challengers for retail order flow.
- Variational: Variational's peer-to-peer perpetuals design grew open interest about 78% in Q3, showing that differentiated market structures can still win share from larger incumbent venues.
- Aster: The BNB Chain-aligned perp DEX lifted open interest roughly 66% in the third quarter, though points-based incentives have historically shaped much of its trading activity.
What Is DeFi (Decentralized Finance)?
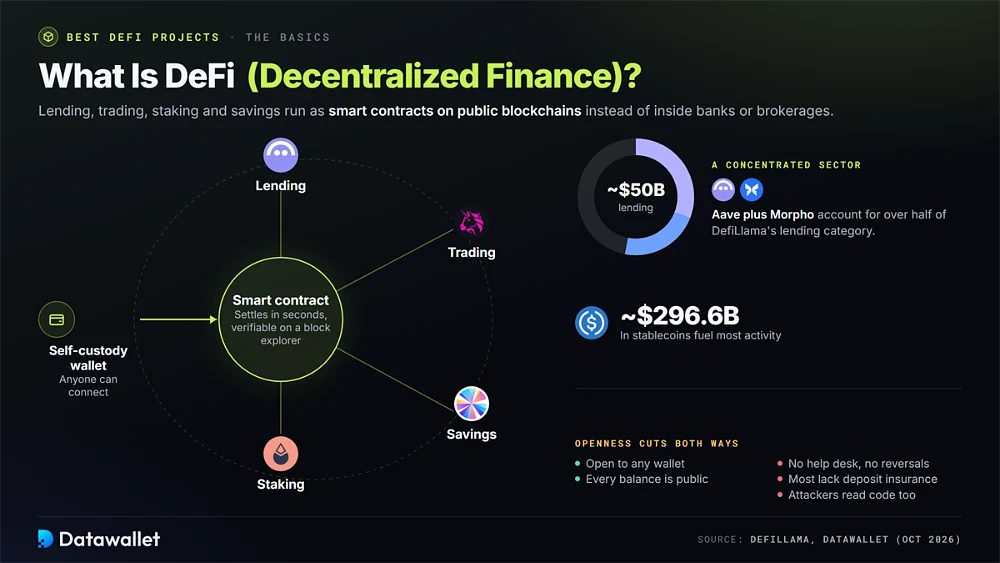
Decentralized finance describes lending, trading, staking and savings products that run as smart contracts on public blockchains instead of inside banks or brokerages. Anyone with a self-custody wallet can interact directly, positions settle onchain in seconds, and every balance, loan and liquidation can be verified through a block explorer.
Openness cuts both ways. There is no help desk to reverse a mistaken transfer, most protocols lack deposit insurance, and a published contract can be studied by attackers as easily as by auditors. Track record, audit history and incident response therefore matter more than any headline APY a protocol advertises.
The sector is concentrated: DefiLlama's lending category holds about $50 billion, and Aave plus Morpho account for over half. Stablecoins worth roughly $296.6 billion fuel most activity, so choosing a reliable dollar token matters as much as choosing the protocol itself.
How Do DeFi Protocols Generate Yield?
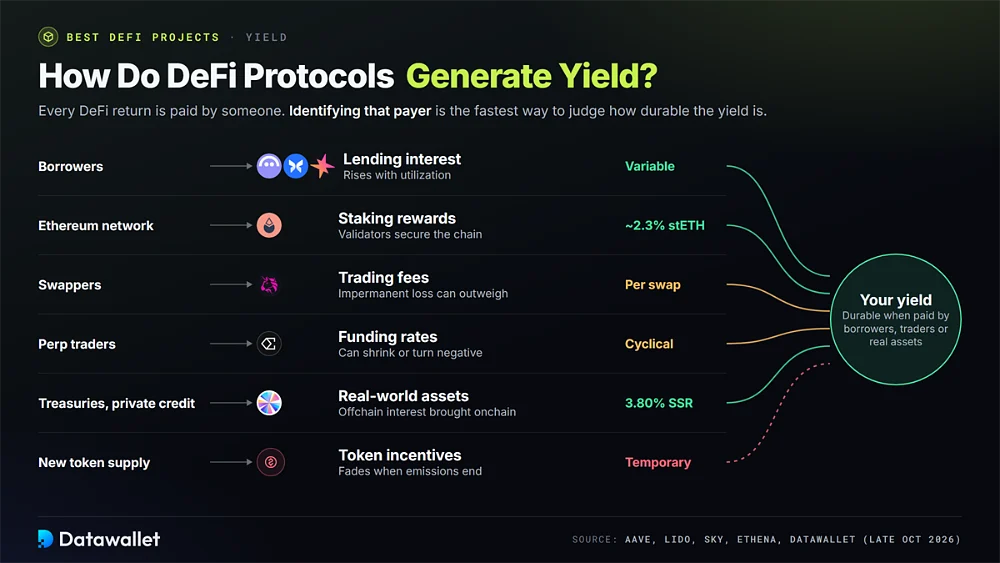
Every DeFi return is paid by someone, and identifying that payer is the fastest way to judge durability. Sustainable yields come from borrowers, traders or real-world assets, not from freshly printed governance tokens.
The six main sources behind onchain yield in 2026:
- Lending interest: Borrowers on Aave, Morpho and Spark pay variable or fixed rates, and that interest flows to suppliers, rising when utilization spikes and falling when demand cools.
- Staking rewards: Ethereum pays validators for securing the network, and liquid staking tokens such as stETH pass those rewards through, currently around 2.3% after Lido's fee.
- Trading fees: Liquidity providers on Uniswap earn a share of every swap in their pool, but price moves can create impermanent loss that outweighs the fees collected.
- Funding rates: Perpetual futures pay periodic funding between longs and shorts, which Ethena captures for sUSDe holders; when traders turn bearish, that income shrinks or turns negative.
- Real-world assets: Tokenized Treasuries and private credit bring offchain interest onchain, and protocols like Sky blend that income into savings rates such as the current 3.80% SSR.
- Token incentives: Some protocols top up yields with their own tokens, which inflates headline APYs temporarily and usually disappears once emissions end or the token price falls.
How to Start Using DeFi Safely
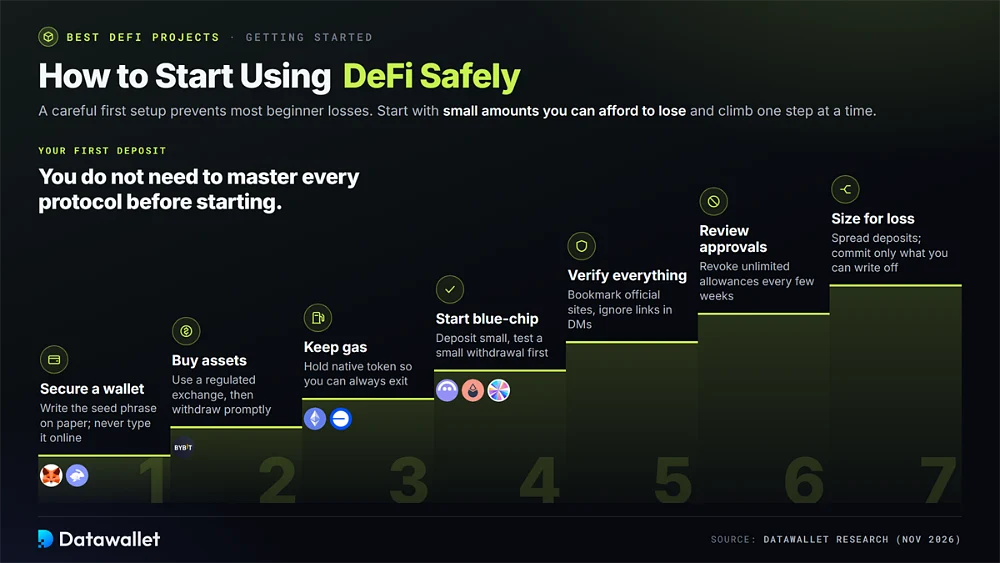
You do not need to master every protocol before starting, but a careful first setup prevents most beginner losses. Begin with small amounts you can afford to lose while learning how wallets, approvals and gas work.
A practical sequence for your first DeFi deposit:
- Secure a wallet: Install a reputable self-custody wallet, record the recovery phrase on paper, and never type it into a website, chat or support form claiming to help.
- Buy assets: Use a regulated exchange such as Bybit to purchase the stablecoins or ETH you need, then withdraw promptly rather than leaving balances in exchange hot wallets.
- Keep gas: Hold a small reserve of the network's native token, such as ETH on Ethereum or Base, so you can always exit positions or revoke approvals quickly.
- Start blue-chip: Make your first deposit on an established protocol like Aave, Lido or Sky, and test a small withdrawal before committing larger amounts or using leverage.
- Verify everything: Bookmark official sites, compare contract addresses against project documentation, and ignore links arriving by direct message, since fake front ends remain a leading cause of wallet drains.
- Review approvals: Check token permissions every few weeks and revoke unlimited allowances you no longer use, so a compromised contract cannot pull funds from your wallet later.
- Size for loss: Assume any single protocol, bridge or stablecoin can fail, spread deposits across venues, and never commit more than you could write off while learning.
Is DeFi Legal Around the World?
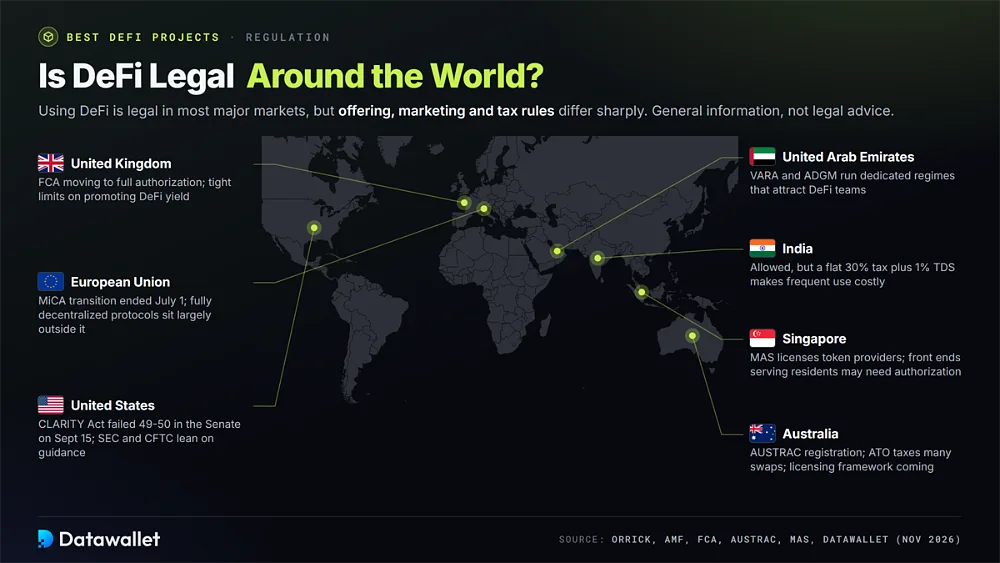
Using DeFi is legal in most major markets, but rules on offering, marketing and taxing it differ sharply, and front ends increasingly restrict access by location. This overview is general information, not legal advice.
Where key jurisdictions stand on DeFi as of November 2026:
- United States: The CLARITY Act failed a 49-50 Senate vote on September 15, so the SEC and CFTC are shaping rules through guidance while many perp front ends block Americans.
- European Union: MiCA's transitional period ended on July 1, 2026, so only authorized providers may serve EU clients, though fully decentralized protocols still sit largely outside its scope. See our MiCA-licensed exchanges list.
- United Kingdom: The FCA is bringing cryptoasset activities into a full authorization regime and tightly limits how DeFi yield products can be promoted to retail customers.
- Australia: Exchanges must register with AUSTRAC, the ATO treats many DeFi swaps and deposits as taxable events, and lawmakers are finalizing a licensing framework for digital asset platforms.
- Singapore: MAS licenses digital payment token providers under the Payment Services Act, and interfaces actively serving residents may require authorization even when the underlying protocol does not.
- United Arab Emirates: Dubai's VARA and Abu Dhabi's ADGM operate dedicated virtual asset regimes, which is why many DeFi foundations and trading teams choose to base operations there.
- India: Crypto use is permitted, but a flat 30% tax on gains plus 1% tax deducted at source on transfers makes frequent DeFi activity expensive to manage.
Risks of Using DeFi Projects
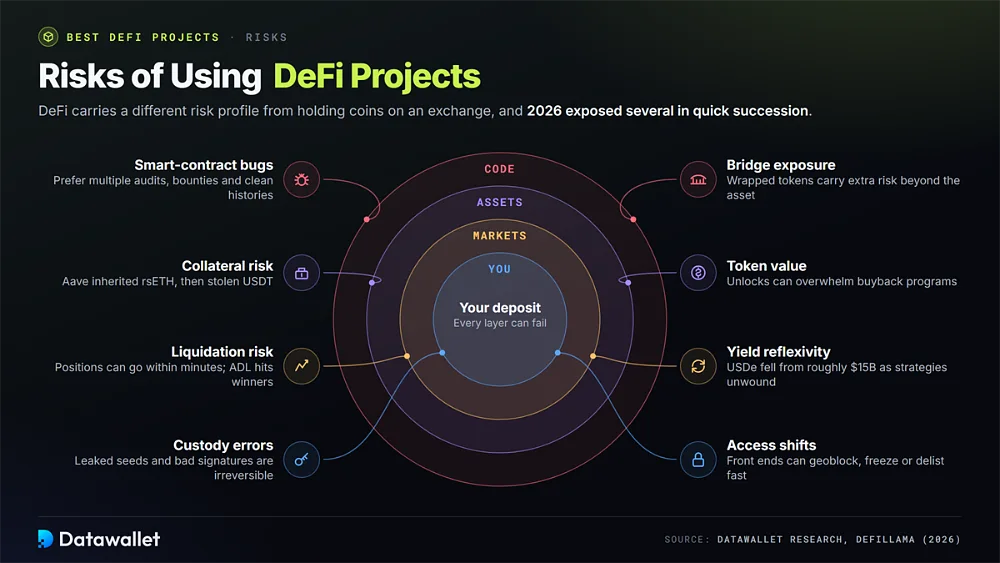
DeFi carries a different risk profile from holding coins on an exchange, and 2026 exposed several of those risks in quick succession. Review each category below before committing capital to any protocol on this list.
The main risks to weigh before depositing in 2026:
- Smart-contract bugs: A flaw in code can drain a protocol even when its blockchain works perfectly, so prefer contracts with multiple audits, bug bounties and long incident-free histories.
- Collateral risk: Lenders inherit weaknesses in every asset they accept, as Aave learned when compromised rsETH became bad debt, then again when stolen USDT entered its markets.
- Bridge exposure: Cross-chain bridges concentrate value and have produced some of the largest exploits, so wrapped or bridged tokens carry extra risk beyond the underlying asset.
- Liquidation risk: Borrowing and leveraged perps can be liquidated within minutes during sharp volatility, and venues may use auto-deleveraging that closes even profitable positions with little warning.
- Yield reflexivity: Funding-rate and looping strategies can unwind fast when markets flip, shrinking supply and yields together, as USDe's fall from roughly $15 billion clearly demonstrated.
- Custody errors: Self-custody means a leaked seed phrase, malicious signature or poisoned address is usually irreversible, and no protocol can restore funds sent to the wrong place.
- Access shifts: Front ends can geoblock your country, freeze markets or delist assets with little notice, as Aave's emergency freeze after the Binance breach briefly showed.
- Token value: A thriving protocol does not guarantee a rising token, because some route little or no revenue to holders, and unlocks can overwhelm buyback programs.
Final Thoughts
The best DeFi projects of 2026 are the ones still earning when incentives fade. Hyperliquid leads by making onchain derivatives competitive with centralized venues, while Aave and Morpho dominate lending, Lido anchors staking, Uniswap handles swaps, Sky offers a savings-rate dollar and Ethena supplies a market-driven synthetic alternative.
None are risk-free, and this year proved that threats can arrive from bridges and exchanges as easily as from code. Match each protocol to a specific goal, start small, keep assets in self-custody, and treat every advertised yield as a question about who ultimately pays it. Track sector flows on our TVL dashboard.
Our Methodology
We assessed DeFi protocols with live mainnet products and public onchain data as of October 31, 2026, using six criteria.
- Rating: Scores out of 5 weigh scale, revenue quality, security history, incident response, decentralization of control and how consistently each protocol delivers its core product.
- Usage and scale: Total value locked, active loans, trading volume and open interest came from DefiLlama, CoinGecko, CoinMarketCap and each protocol's own dashboards and governance reports.
- Revenue and value accrual: We compared trailing fees with the share reaching token holders through buybacks, burns or staking rewards, and noted dormant or conditional fee switches.
- Security record: We reviewed audits, bug bounties, backstop funds and 2026 incidents, including the Kelp DAO exploit and the Binance hack's spillover into DeFi lending markets.
- Resilience under stress: Protocols earned credit for staying solvent, communicating quickly and restoring normal operations during the April and October 2026 shocks.
- Access and regulation: We checked geoblocking, front-end restrictions and how US, EU and other regulatory developments affect retail users' ability to participate.
Protocols lacking a live product, transparent data or a sustainable source of yield were excluded. Ratings reflect independent research and are not investment advice. Our editorial methodology explains the full review process.